

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: MAA Market to Reach USD 1,733M by 2032 at 4.23% CAGR

Methacrylic Acid (MAA) Market — Strategic Outlook for 2026 (PW Consulting)
Executive preview
The Methacrylic Acid (MAA) market has entered a phase of steady expansion underpinned by derivative-driven demand and continued technical substitution across coatings, adhesives and specialty polymers. By our base year (2025) the global market reached approximately USD 1,290 million and, with a compound annual growth rate of roughly 4.23% through our forecast horizon, is projected to approach the upper USD‑millions range by 2032. For commercial leaders and strategic planners making capital, sourcing, or M&A decisions in 2026, this research is designed as a decisioning toolkit: it synthesizes macro momentum, cost dynamics, supplier economics and a competitor heatmap into executable options while intentionally withholding granular segment tables to preserve the commercial premium of the full intelligence set.
Methacrylic Acid (MAA) (CAS 79-41-4) Market
Why this matters for 2026 decision-makers
-
Timing of capital deployment — given the market’s predictable mid-single-digit CAGR and the stepwise capacity additions being considered across incumbent producers, the 2026 planning window is a critical inflection point for greenfield investments, debottlenecking and capacity optimization. Our modelling shows that early-mover positions can capture disproportionate margin uplift where feedstock sourcing and logistic advantages are secured.
Methacrylic Acid (MAA) (CAS 79-41-4) Market -
Procurement and feedstock strategy — MAA production economics are highly correlated with upstream feedstocks (notably isobutylene and tert-butanol) and intermediates. Volatility in these raw material inputs—driven by crude oil swings and refinery operational cycles—translates directly into variable cost profiles. A 2026 procurement playbook should embed dynamic hedging, dual-sourcing and optionality in feedstock conversion routes.
Methacrylic Acid (MAA) (CAS 79-41-4) Market -
Product and route differentiation — technological pathways (acetone cyanohydrin routes, ethylene-based processes, dehydration/hydrolysis of MMA intermediates and proprietary high‑purity grades) create distinct cost, quality and regulatory footprints. For players considering portfolio expansion or premiumization, understanding these trade-offs is material to pricing power and customer segmentation in 2026 and beyond.
-
M&A and partnership windows — subdued but consistent growth creates attractive bolt-on opportunities for incumbents that can improve geographic reach or feedstock integration without committing to large scale greenfield capital. Our scenario work identifies where bolt-on acquisitions deliver the fastest payback and where vertical integration materially de-risks feedstock exposure.
Market trajectory — headline numbers without the drilldown
From a quantitative standpoint, MAA’s global market scale has expanded from a baseline in the early 2020s to roughly USD 1.29 billion in 2025. Under our central case—reflecting demand growth in construction-related additives, performance coatings and specialty resins—the market grows at an approximate 4.23% CAGR through our forecast window to reach roughly USD 1.73 billion by the end of the horizon. These headline figures reflect aggregate demand, pricing behavior and expected capacity churn; the full report provides the month-by-month demand-supply balances and pricing curves required to run a transaction or investment model.
Dynamics shaping supply and margins
-
Feedstock linkage and volatility — MAA production is materially dependent on isobutylene and tert-butanol for oxidation routes, and on acetone‑related intermediates in certain process variants. Crude-derived feedstock price swings and refinery maintenance cycles introduce periodic margin compression. Our sensitivity analyses quantify margin impact scenarios under differing crude price paths and feedstock disruptions.
-
Route economics and quality segmentation — producers operating different chemical routes report divergent operating costs, impurity profiles and suitability for high-purity applications (e.g., superplasticizers, specialty coatings). This heterogeneity underpins premium product strategies; it also creates pockets of arbitrage where lower-cost feedstock access can be monetized.
-
Regulatory and sustainability pressure — tighter emissions standards, solvent regulation and customer sustainability mandates are driving demand for lower-carbon feedstocks and more predictable supply chains. The economic impact of compliance and potential emissions-related tariffs is explicitly modelled in our investment cases.
-
Downstream sensitivity — demand drivers for MAA are concentrated in coatings, adhesives, polymers and construction chemicals. Changes in construction cycles, automotive production or paint formulations (for performance or VOC regulation reasons) have an outsized effect on utilization and short-term pricing dynamics.
Competitive landscape — who matters and why
The sector exhibits a classic mix of global integrators and technical specialists. Leading incumbent producers operate differentiated process routes and commercial playbooks:
-
Mitsubishi Chemical Corporation (Tokyo) — a long-established supplier leveraging the acetone cyanohydrin route; strength lies in integration with MMA and established downstream methacrylate customers in coatings and adhesives.
-
Kuraray Co., Ltd. (Tokyo) — focuses on dehydration/hydrolysis pathways and offers logistical flexibility across packaged and bulk formats; its channel access into concrete admixtures and specialty paints is a commercial advantage.
-
Evonik Industries AG (Darmstadt) — positions through high‑purity grades and branded methacrylate monomers, serving performance applications such as superplasticizers and specialty adhesives where quality premium is extractable.
-
BASF SE (Ludwigshafen) — offers ethylene-route products with scale economics and a broad application set; its global footprint supports large-volume industrial users and polymer producers.
Our report contains plant-level benchmarking, route-level cost curves, and a strategic heatmap that juxtaposes these suppliers’ technical strengths, geographic reach and customer channel control. That heatmap is intentionally summarized here to demonstrate the kind of insight available without reproducing commercially sensitive allocation tables.
What the report contains — practical modules for 2026 action
-
A validated market-sizing engine (historical 2020–2025 and monthly baselines) plus three scenario forecasts to 2032, enabling stress-tested investment appraisals.
-
Supply chain and plant-level economics, including breakdowns of feedstock consumption, conversion yields, variable and fixed cost stacks, and breakeven sensitivity to feedstock price swings.
-
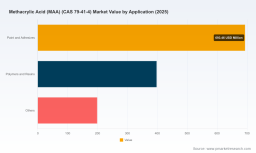
Waterfall of demand by end-use (coatings, adhesives, polymers and others) and adoption curves for premium grades—presented qualitatively here and quantified in the full report.
-
Competitor profiles and strategic playbooks: route differentiation, commercial positioning, likely capacity moves and M&A appetite mapping.
-
Regulatory and ESG overlay with scenario-based compliance cost projections and decarbonization levers.
-
Actionable annexes: supplier due diligence checklist, commercial negotiation templates, and investment memo templates for board presentation.
Strategic recommendations for 2026
-
Institutionalize feedstock optionality — secure medium-term offtakes or tolling agreements with either isobutylene or tert-butanol suppliers and evaluate co-located steamcracker/refinery tie-ups to dampen cost volatility.
-
Prioritize route-based product segmentation — separate commercial streams for high‑purity specialty MAA versus commodity grades and align sales incentives accordingly.
-
Use targeted M&A to buy market access rather than volume alone — look for assets that provide access to underserved downstream channels or feedstock integration rather than simply increasing capacity.
-
Create dynamic pricing mechanisms with key accounts — index contracts to transparent feedstock baskets with floors/ceilings to stabilize margins while maintaining competitiveness.
-
Integrate ESG into the product story — customers increasingly favor suppliers with verified lower-carbon feedstocks; a credible roadmap to reduced scope‑1/2 emissions will unlock premium contracts.
How to use this intelligence in practice
-
Investment committees: run the report’s scenario models during capital approval to quantify downside risk and payback under varying feedstock price regimes.
-
Commercial teams: deploy the packaging of route-differentiated value propositions and the negotiation playbook to accelerate conversion of strategic accounts.
-
Sourcing and operations: use the plant-level cost curves and supplier due diligence annex to rework contracts and contingency plans ahead of the next crude cycle disruption.
Closing — what you gain and next step
PW Consulting’s Methacrylic Acid (MAA) Market study is crafted as a practical, board-ready intelligence asset for 2026 decisioning. It pairs headline market scale (USD ~1.29 billion in 2025, growing at ~4.23% CAGR to a high‑single‑billion figure by 2032) with the tactical playbooks that procurement, commercial and corporate development teams need to act. The analysis demonstrates where margin pools will shift, which route and product plays offer defensible premiums, and the specific levers to mitigate feedstock volatility. To preserve the commercial advantage for subscribers, granular regional/application breakdowns and plant-level financials are reserved for the full report.
Contact PW Consulting to access the complete dataset, scenario models and the supplier heatmap required to execute the recommended 2026 actions.
For detailed analysis of this topic, please visit the official page: Methacrylic Acid (MAA) (CAS 79-41-4) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com