

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Zirconia Market Set to Grow at 6.98% CAGR Through 2032

Zirconia Market: Strategic Imperatives for 2026 Decision‑Makers
Executive snapshot
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise strategic orientation for executive teams preparing capital, sourcing, product and M&A decisions in 2026. Our proprietary market model shows the global zirconia market advancing from a base-year value of USD 215.0 Million (2025) and growing at a compound annual growth rate (CAGR) of 6.98% through the 2026–2032 forecast window, reaching an anticipated market size in the mid-300s (USD Million) by 2032. That trajectory reflects steady demand expansion, structural shifts in downstream applications, and intensifying supply‑chain friction that together create both risk and opportunity for suppliers, materials processors and OEMs.
Zirconia Market
Why this matters for 2026 planning cycles
- Capital prioritization: A near-7% CAGR suggests that volume-driven capital projects (capacity expansion, automation, downstream integration) can deliver attractive payback profiles if timed to market inflection points.
- Procurement strategy: Raw material tightness and concentrated import sources mean that procurement teams must move from transactional buying to contractual security — blending long-term supply agreements, option capacity and geographically diversified sourcing.
- Portfolio choices: End-markets are exhibiting divergent growth rates and margin structures; product managers must choose between premium, high-margin formulations and commoditized grades where scale matters more than margin per unit.
- M&A and partnerships: Market concentration metrics indicate a fragmented supplier base (limited top-three/top-five share), increasing the strategic value of bolt-on acquisitions, capacity alliances and selective vertical integration into powder and feedstock supply.
Market dynamics shaping the 2026–2032 opportunity set
Three dynamics dominate the near-term horizon: supply-side volatility, differentiated end‑market demand, and technology-driven product migration. Collectively these create asymmetric outcomes across players depending on strategic posture.
Zirconia Market
- Supply-side volatility. Global mine production of zirconium mineral concentrates contracted meaningfully in 2025, reflecting operational disruptions and inventory adjustments upstream. At the same time, new recovery initiatives in North America — including recovery of zircon as a co‑product from heavy‑mineral sands and processing of mineral sands tailings — signal that non‑traditional supply sources are emerging. For companies reliant on finely specified zirconia powders, this means an elevated near‑term risk of feedstock price spikes and quality variance, and a longer-term opening to secure differentiated domestic or near‑shore feedstock.
- Regulatory and trade friction. Recent tariff schedules and evolving trade policies have increased landed cost volatility for zirconium compounds. Executives must assume periodic policy shocks as a baseline scenario when stress‑testing 2026 procurement and pricing plans.
- Downstream technology and product mix. The material is no longer a single‑use commodity: multi‑layered and doped zirconia grades have taken share in premium dental and technical ceramic applications. This drives an innovation premium for suppliers with R&D, powder refinement and quality control capabilities — and it creates a clear segmentation in margin profiles across product families.
Competitive landscape: what the next 12–24 months will reveal
The zirconia value chain spans high‑purity powder producers, block and semi‑finished manufacturers, dental and medical OEMs, and specialty ceramic part fabricators. While market share is relatively dispersed — creating an environment where nimble scale players can establish meaningful regional advantages — several firms and recent transactions deserve special attention for strategic planning:
Zirconia Market
- Tosoh Corporation and Imerys. Tosoh’s reported growth in advanced materials underscores the premium attached to high‑quality zirconia powder and fine ceramics. Imerys’ recent acquisition activity to shore up minerals and refractory inputs signals consolidation aimed at securing upstream continuity and improving margin capture. For strategic buyers, these developments highlight the value of aligning with powder producers or acquiring upstream assets to hedge feedstock risk and extract more value from the vertical chain.
- Dental‑focused leaders (Ivoclar Vivadent, Dentsply Sirona, 3M ESPE, Kuraray Noritake, VITA Zahnfabrik). These firms combine product innovation (multi‑layer blocks, aesthetic systems) with established CAD/CAM supply relationships. Capacity expansions and product launches from dental incumbents demonstrate two threads: continued premiumization of dental zirconia and the importance of integrated systems that lock in lab and clinic pathways. Strategic partners and new entrants must therefore consider whether to compete on raw material cost, product differentiation, or integration with digital dentistry ecosystems.
- Specialty and custom manufacturers (Saint‑Gobain ZirPro, Imerys, Astro Met, C‑Mac International). These players serve technical ceramics and industrial markets where fabrication precision and material properties drive procurement decisions. In a fragmented environment, service excellence and custom capability can command a margin premium, creating attractive niches for specialized machine shops and contract manufacturers.
What the PW Consulting Zirconia Market report delivers (practical content)
This study is structured to support actionable decision-making in 2026. Key deliverables include:
- Macroeconomic and demand model calibrated to 2020–2025 history and stress‑tested for 2026–2032 scenarios, including base, upside and downside paths that quantify revenue and volume impacts under alternative recovery and supply disruption assumptions.
- Supply‑chain mapping and risk heatmaps that identify single‑point failures, vendor concentration, logistics chokepoints and tariff exposure across major trade lanes.
- Competitive playbooks with capability matrices for the leading suppliers, including technology differentiation, manufacturing footprint, and likely strategic moves over the next 18 months.
- Practical procurement and inventory playbooks — contractual templates, hedge‑style approaches and a phased inventory ladder for raw material build‑outs aligned with CAPEX timelines.
- M&A screening tool and valuation framework calibrated to zirconia-specific multiples, margin dynamics and integration cost sensitivities to help prioritise target types and geographies.
- Go‑to‑market strategies and commercialization paths for product innovations (e.g., multi‑layer aesthetic blocks, high‑purity powders) with recommended pilot partners and commercial milestones.
- Appendices with vendor dossiers, a curated list of public sources and a model workbook (editable) to re-run scenarios against bespoke input assumptions.
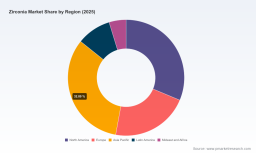
Note: The full report contains the granular segment and regional breakdowns that underpin the above outputs. To preserve the predictive value of our proprietary segmentation and to encourage data‑driven conversations, we present here synthesis and strategic conclusions rather than all source-level segment tables. The complete dataset and interactive model are accessible through our publication portal.
Strategic recommendations for 2026 decision cycles
- Lock in strategic feedstock access. Enter multi-year offtake or JV arrangements with powder producers or miners, and evaluate near‑shore processing investments to reduce exposure to import concentration and trade shocks.
- Pursue selective vertical integration or partnerships. Given fragmented market concentration, targeted acquisitions (powder producers, specialty grinding/atomization assets) or capacity-sharing agreements can capture margin and control quality.
- Prioritize modular, scalable capacity additions. Instead of large single‑site builds, favor cell-based production and local finishing capabilities that can be scaled with demand — reducing capital at risk if demand shifts across end‑uses.
- Differentiate through specifications and service. Invest in R&D for multi‑layered, doped and application‑specific grades; complement this with lab and clinical support for dental customers or engineering partners for industrial end‑uses.
- Hedge policy and price risk. Incorporate tariff scenarios into product pricing, and use a combination of contractual instruments and inventory timing to mitigate raw material spikes. Maintain a contingency buffer in both pounds and processing capability, sized to survive at least one full procurement cycle disruption.
- Monitor consolidation signals. Watch for additional upstream M&A and non‑traditional entrants exploiting tailings recovery or processing technologies — these moves will change feedstock economics and can be either competitive threats or acquisition targets.
Competitive moves to watch in 2026
- Additional upstream consolidation and asset purchases by mineral processors and refractory specialists seeking feedstock security.
- Capacity expansions and product launches from dental incumbents that further raise the bar on aesthetic performance and CAD/CAM compatibility.
- New entrants leveraging recycled or tailings‑sourced zircon as a cost and sustainability differentiator.
Concluding view
The zirconia market entering 2026 is characterized by robust top‑line expansion (a roughly mid‑single digit CAGR through 2032), pronounced upstream fragility and meaningful product segmentation at the downstream edge. These dynamics create a landscape where strategic moves made in 2026 — particularly around supply security, selective vertical integration and product differentiation — will disproportionately influence competitive position and profitability over the next seven years. For leaders who translate this market intelligence into disciplined procurement, focused R&D and opportunistic consolidation, the payoff will be sustainable margin expansion and stronger resilience to future shocks.
For decision teams seeking the full dataset, segment-level tables and the interactive scenario model referenced here, PW Consulting’s full Zirconia Market report and model workbook are available on our publication page — they contain the detailed inputs you will need to finalize 2026 capital, sourcing and M&A plans.
For detailed analysis of this topic, please visit the official page: Zirconia Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com