

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Portable Lighting Market Set for 5.5% CAGR Through 2032

Portable Lighting Market 2026 Strategic Preview — A PW Consulting Industry Brief
As organizations prepare budgets and strategic roadmaps for 2026, the Portable Lighting market presents a pragmatic mix of steady growth, evolving technology vectors, and competitive realignment. PW Consulting’s latest market research — anchored on a 2025 base year and projecting through 2032 — synthesizes demand forecasts, competitive intelligence, regulatory shifts, and execution-ready playbooks designed to inform C-suite and business unit decisions. This brief outlines the strategic value of that research, the logic underpinning our forecast (CAGR 5.5% over the forecast window), and the ways senior leaders should reposition to capture value without revealing the granular splits reserved for subscribers.
Portable Lighting Market
Why this research matters for 2026 decision cycles
-
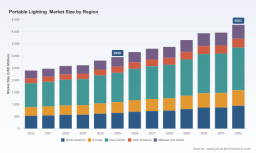
Actionable growth horizon. Our model shows the market expanding from a mid‑2025 baseline (USD 2,950 Million) to an explicitly modelled opportunity set through 2032 (USD 4,283 Million). The implied compound annual growth rate of 5.5% is conservative relative to many adjacent consumer‑electronics categories, but it reflects durable demand driven by replacement cycles, professional procurement, and product premiumization.
Portable Lighting Market -
Decision relevance across functions. The research was constructed to support capital allocation (manufacturing footprint, tooling, battery supply), product portfolio triage (premium vs. value, rechargeable vs. disposable), go‑to‑market choices (direct DTC, specialist distributors, channel partnerships), and M&A screening (technology tuck‑ins, contract manufacturers, alternative energy/battery tech).
Portable Lighting Market -
Risk‑aware growth. We quantify strategic risks that are becoming operational realities in 2026: components and LED die concentration in Asia, the accelerating policy landscape favoring LEDs and restricting legacy lamp types, and rising expectations for sustainability and circularity from both retail partners and institutional buyers.
Market trajectory and practical implications
The compiled historical series (2020–2025) and our forecast (2026–2032) illustrate a market that is resilient yet increasingly differentiated. From an operational standpoint, the growth trajectory signals three intersecting themes that should shape 2026 plans:
-
Premiumization and feature convergence. Buyers are paying up for runtime, integrated smart features (battery management, wireless charging, app connectivity), and ruggedization. Manufacturers that translate these attributes into clear total cost of ownership benefits for industrial and professional customers will capture disproportionate value.
-
Sustainability as a marketable capability. Product innovations that demonstrate durability, repairability (user‑replaceable batteries), and reduced packaging waste are moving from “nice to have” into procurement checklists. Recent product releases emphasizing plastic‑free packaging and replaceable power modules underscore this point.
-
Channel fragmentation and premium DTC. Retail shelves remain important, but direct channels enable richer margins and closer learnings on consumer usage. Success requires a disciplined omnichannel playbook that balances broad reach with high‑margin specialty segments (outdoor, tactical, professional safety).
Competitive landscape — who matters and what they signal
The sector remains moderately fragmented. Market concentration metrics indicate the top three vendors account for roughly one‑third of the market, and the top five approach half — a competitive structure that supports both scale plays and nimble niche specialists. Below we summarize how select incumbents are positioning and what that implies for competitors and investors.
-
Streamlight, Inc. — Known for tactical, industrial, and safety‑rated LED products, Streamlight’s product evolution emphasizes lumen performance, rugged IP ratings, and extended runtimes. Their mid‑2025 tactical launch (a high‑output model with IP67 endurance) exemplifies a focus on professional buyers who prioritize reliability and spec‑led procurement. For competitors, this raises the bar on durability and professional certifications.
-
Olight Group — Olight’s 2026 releases underline two industry trends: modularity (user‑replaceable batteries) and sustainability (metal unibody designs, plastic‑free packaging). These moves increase product lifecycles and reduce downstream waste; OEMs that cannot match modular serviceability risk being outcompeted in premium segments.
-
Fenix Lighting , Nitecore , and Ledlenser — These brands emphasize high‑performance rechargeable designs and engineering pedigree. Their investments in manufacturability, thermal management, and warranty positioning indicate an arms race around reliability claims and product warranties — factors that tilt purchasing toward established OEMs for mission‑critical applications.
-
Petzl , Maglite , NEBO , and COAST — Each of these firms leverages brand heritage or specialized use cases (climbing, tactical, hunting, work lighting) to maintain margins despite increasing competition on price. Strategic partnerships with safety equipment distributors and professional channels will remain a core defense.
Regulatory and supply‑chain dynamics that will shape 2026 outcomes
Two regulatory and supply realities deserve special attention. First, policy developments in certain jurisdictions are accelerating the phase‑out of legacy lighting technologies, which effectively channel demand toward LED‑based portable lighting. Second, LED die and package manufacturing continues to be concentrated in Asia, constraining options for localized supply expansion without substantial capital investment.
-
Policy tailwinds for LED adoption create a window to upsell LED replacements and smart features — but they also raise compliance complexity for exporters. Product testing, certification costs, and packaging compliance will be non‑trivial line items in 2026 planning.
-
Supply concentration of critical components elevates supply‑chain risk. Companies must choose between outsourcing cost advantages and vertically securing critical inputs. Options include long‑term supplier contracts, dual‑sourcing strategies, or targeted investments into alternative suppliers and contract manufacturing closer to end markets.
What the PW Consulting report contains — practical outputs for 2026
The full Portable Lighting Market research combines quantitative rigor with operational utility. Subscribers receive:
-
Proprietary forecasts (2026–2032) with scenario modeling and sensitivity analysis around pricing, raw‑material shocks, and regulatory transitions.
-
Commercial playbooks: market entry, premiumization vs. volume strategies, channel optimization, and distributor scorecards customized for leading geographies.
-
Competitive intelligence dossiers on key manufacturers, including product roadmaps, patent footprints, margin proxies, and recent go‑to‑market moves.
-
Operational toolkits: supplier‑risk matrices, recommended inventory buffers, battery and electronics qualification checklists, and unit‑economics templates for new product introductions.
-
M&A and partnership screening: a prioritized list of target archetypes, valuation heuristics, and integration playbooks for 2026‑era roll ups and technology partnerships.
-
Data deliverables: downloadable models (USD, Million), executive dashboards, and CSV exports of the historical and forecast series for custom scenario work.
Note: this brief intentionally omits the granular regional, type, and application splits contained in the full report to preserve the value of the detailed intelligence and to comply with our “trailer” principle — the full segmentation, including market-by-region, market-by-type, and market-by-application breakdowns, is available to registered subscribers.
Strategic recommendations for executives planning 2026
-
Prioritize modular, serviceable designs. Introduce or accelerate user‑replaceable power modules and accessible repair pathways to capture premium pricing and support sustainability claims demanded by procurement teams.
-
Rebalance channel investments. Grow DTC capabilities for premium lines while retaining deep relationships with professional distributors. Invest in digital analytics to monetize product usage data and inform product lifecycle strategies.
-
Hedge supply risk with a tiered sourcing strategy. Establish strategic supplier partnerships and conditional local assembly options for critical components to minimize disruption without committing to costly upstream capex prematurely.
-
Embed sustainability in product economics. Rework cost models to internalize packaging reduction, repairability, and battery take‑back programs, then present lifecycle cost savings to procurement buyers as part of the sales pitch.
-
Use M&A selectively. Look for bolt‑on technologies (battery management systems, IoT-enabled controls, or advanced optics) that accelerate time‑to‑market for higher‑margin product segments rather than broad geographic rollups alone.
How to use our forecast in your 2026 planning
Integrate the PW Consulting forecast into three planning layers:
-
Strategic (18–36 months): Use the forecast to set portfolio priorities, capex envelopes, and geographic investment sequencing aligned to projected demand growth and regulatory timing.
-
Tactical (6–18 months): Calibrate SKUs, channel launches, and promotional calendars to exploit near‑term demand pockets identified in our scenario runs.
-
Operational (0–6 months): Implement supplier safeguards, inventory buffers, and certification roadmaps to ensure the business is resilient to component and regulatory shocks expected through 2026.
Closing perspective
For executives and investors, 2026 is a year to move from reactive product cycles to proactive structurally aligned strategies. With market expansion projected at a 5.5% CAGR through 2032 and demonstrable momentum in premium, sustainable, and serviceable product attributes, winners will be those who pair product engineering with disciplined channel and supply‑chain decisions.
To access the full dataset, detailed segmentation, and the operational toolkits described above, PW Consulting invites you to download the complete Portable Lighting Market report and associated data appendices. Our subscribers receive the full forensic segmentation and executable roadmaps that translate the high‑level signals presented here into board‑level actions and 2026 implementation plans.
For detailed analysis of this topic, please visit the official page: Portable Lighting Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com