

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: AdBlue Market Poised for 5.5% CAGR to 2032

AdBlue Market 2026: Strategic Preview for Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise yet substantive preview of our new AdBlue Market study — intentionally designed as a high-fidelity “trailer” for executives who must make calibrated decisions in 2026. This briefing synthesizes the structural facts shaping the market today, the directional forecasts through our analytic horizon (2026–2032), and the practical decision-support elements we include in the full report. We show enough to build confidence in our methodology and to orient strategy, while reserving proprietary segmentation detail to the full release.
AdBlue Market
Why AdBlue is a 2026 Strategic Priority
AdBlue (DEF) is no longer a niche afterthought. It sits at the nexus of emissions regulation, heavy-vehicle operational reliability, and commodity-linked supply chains. For suppliers, OEMs, fleet operators, and investors, small shifts in feedstock or logistics capacity can cascade into materially different cost and service outcomes. Our market model — anchored to a 2025 base year and a historical baseline of 2020–2025 — projects compound growth through 2032 at a 5.5% CAGR. Under this trajectory, the global market value rises from a mid‑market 2025 base to a materially larger 2032 position, underscoring a stable, investable sector with recurring demand drivers.
AdBlue Market
Snapshot: Macroeconomic Picture and Near-Term Trajectory
-
Base-year and forecast anchoring: Our base year is 2025 with a multi-year historical series, and our formal forecast window runs 2026–2032. The modelling integrates fleet electrification scenarios, diesel fleet replacement rates, and regulatory tightening to produce a probabilistic range of demand outcomes.
AdBlue Market -
Growth profile: The market’s mid‑cycle CAGR of 5.5% reflects steady demand in regulated transport and industrial SCR (selective catalytic reduction) applications, tempered by substitution dynamics in passenger light vehicles and non-road sectors.
-
Concentration and structural potency: The market displays measurable concentration at the top end — the three largest suppliers control a clear majority share and the top five aggregate an even larger portion — a fact that shapes pricing power and logistics bargaining in many regions.
Dynamics: Raw Materials, Pricing, and Regulatory Shocks
Three operational vectors dominate short- and medium-term volatility.
-
Feedstock volatility: Urea feedstock remains the principal cost driver. Through 2025, global urea traded in a constrained band reflecting seasonal agricultural demand and gas-feedstock exposure; forward-looking indicators show a similar, slightly elevated band for 2026. This price sensitivity propagates quickly into finished AdBlue pricing and can create intermittent supply stress for buyers operating lean inventory models.
-
Regulatory pressure and second-order effects: Tighter emissions enforcement across many markets sustains baseline demand, but regulation also exposes buyers to supply shocks when upstream fertilizer/urea markets tighten. We have observed price shocks in specific European corridors and consequent spot-market distortions — a pattern likely to reoccur under gas-market disruptions.
-
Packaging and channel economics: AdBlue’s unit economics differ markedly by packaging format (bulk, intermediate, consumer packs) and by distribution channel (direct‑to‑fleet, fuel-station retail, aftermarket). Margins and service expectations vary accordingly; savvy suppliers optimize a mix of bulk contracts and premium packaged SKUs to smooth earnings.
Competitive Landscape — What the Leading Players Signal
The competitive topology blends large incumbent producers with specialized regional players and integrated energy companies. Each type offers distinct strategic signals:
-
Global incumbents with integrated supply chains: Producers with multiple, geographically distributed high-purity facilities and significant storage/logistics redundancy are positioned to command premium offtake terms and to absorb episodic feedstock shocks. Their playbooks prioritize security of supply for large fleet customers and OEM tie-ins.
-
Chemical and energy majors: Firms with petrochemical scale and R&D capability are leveraging product differentiation (e.g., low-carbon variants and certification-backed supply chains) to service OEMs and fleets with sustainability mandates.
-
Specialist regional producers: Agile regional producers and distributors focus on tailored logistics, localized service, and rapid certification (e.g., VDA accreditation) to capture export niches and spot growth corridors.
Key corporate developments in 2024–2025 further illustrate market direction: capacity additions and logistics centres opened near major demand clusters, accreditation of new plants to global standards, and launches of bio‑based or mass‑balance product variants. These moves indicate three strategic priorities among suppliers: secure regional redundancy, introduce sustainability-labelled product lines, and broaden last‑mile access for large fleets.
Strategic Implications for Stakeholders in 2026
-
Fleet operators: Expect procurement friction in scenarios where feedstock-driven price spikes occur. Tactical steps include multi-source contracts with variable replenishment profiles, indexed pricing clauses, and modest buffer inventory calibrated against working capital tolerance. Our supplier scorecards — included in the full report — help prioritize counterparty resilience metrics beyond headline price.
-
Suppliers and distributors: The premium on supply security favors investment in storage, regional co‑packing capabilities, and certifications for sustainability claims. Upside capture comes from differentiated services (e.g., scheduled bulk delivery, mobile dispensing) and from premium channels targeting OEM warranty ecosystems.
-
Investors and M&A teams: Consolidation economics remain compelling where scale delivers logistics leverage and feedstock sourcing power. However, regulatory and reputational risk lines around carbon intensity and feedstock origin are increasingly due-diligence priorities; assets with decarbonized supply chains or credible transition pathways command valuation premiums.
-
OEMs and regulators: Coordinated procurement or pooled storage solutions among OEMs or large fleet consortia can materially reduce supply risk. Regulators contemplating tighter emissions enforcement should expect second-order market adjustments; policy design that supports supply resilience will reduce systemic market volatility.
What PW Consulting’s Full Study Delivers (Practical, Actionable)
Our full AdBlue Market report is built to be used. Highlights include:
-
Proprietary demand scenarios calibrated to vehicle parc dynamics, retrofit rates, and regional regulatory timelines, with sensitivities for fuel-price and feedstock shocks.
-
Supplier benchmarking and a downloadable supplier scorecard framework covering manufacturing footprint resilience, certification status, and logistics redundancy.
-
Commercial playbooks for procurement teams: contract clause templates, inventory buffer models, and decision trees for onshore vs. cross‑border sourcing.
-
Capex and investment models for producers considering new plants, storage hubs, or logistics expansion — with clear ROI banding under conservative and aggressive demand assumptions.
-
Risk matrices linking upstream commodity volatility to price transmission and to regional availability, plus recommended hedging and contractual mitigants.
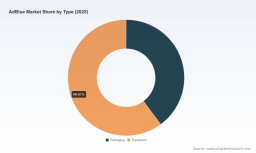
We intentionally withhold granular public disclosure of several segmentation matrices in this preview. The full report contains the actionable split analytics by region, by packaging and equipment type, and by application — data that is regularly used by clients to renegotiate supply contracts, to prioritize investment, and to size commercial pilots. This is purposeful: those splits inform tactical decisions and are thus distributed within the subscription or single‑purchase report.
How to Use This Preview for 2026 Decisions
-
Prioritize supply resilience actions now: execute supplier audits, review storage and logistics capabilities, and add contractual flexibility for feedstock‑driven price pass‑through.
-
Evaluate sustainability positioning: if your customers demand low‑carbon AdBlue variants, map supplier claims and certification trails. Early positioning yields pricing and contractual leverage as OEMs formalize low‑carbon sourcing mandates.
-
Align capex plans with demand banding: use conservative demand scenarios to stress-test new capacity investments; ensure break‑even assumptions account for volatile urea feedstock.
-
Engage with PW Consulting: our deliverables expedite procurement renegotiations, investment committees, and operational contingency planning with slide‑ready analysis and executable templates.
Final Note — What We Don’t Give Away Here
This preview is designed to make you operationally smarter without replacing the detailed playbooks and numerical matrices contained in our full study. We have provided the market’s growth orientation, concentration dynamics, raw-material sensitivities, and a stratified view of supplier archetypes — enough to set immediate priorities for 2026. The full report unlocks the segmentation grids, supplier-by-region scorecards, and downloadable models you will use to execute.
For executives who need rapid, executable intelligence: secure access to the complete PW Consulting AdBlue Market report. It is designed for procurement directors, corporate strategy teams, private-equity desk leads, and OEM sourcing heads who must translate market signals into defensible, revenue-accretive action plans.
For detailed analysis of this topic, please visit the official page: AdBlue Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com