

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Recombinant Trypsin Market Poised for 6.98% CAGR Through 2032

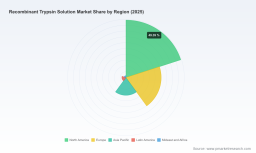
Recombinant Trypsin Solution Market: Strategic Preview for 2026 Decision‑Makers
As senior advisors at PW Consulting, we present a focused executive preview of our full Recombinant Trypsin Solution Market study — designed specifically to inform strategic decisions entering 2026. This preview highlights the market’s macro trajectory, the structural forces that will shape supplier economics and buyer behavior, and the competitive contours that matter most for commercial, R&D, and M&A strategies. We deliberately show analytical depth while holding back the granular segment-by-segment tables and proprietary scenario outputs reserved for subscribers to the full report.
Recombinant Trypsin Solution Market
Market snapshot: trajectory and scale
The recombinant trypsin solutions market has moved from an early specialty reagent footprint into a predictable, mid-sized bioprocess input. On a historical basis, the market expanded from roughly USD 163 million in 2020 to about USD 215 million in 2025 (base year), reflecting steady demand from cell culture, vaccine and biologics manufacturing workflows. Looking forward, our forecast horizon (2026–2032) projects a compound annual growth rate (CAGR) of approximately 6.98%, taking the market to roughly USD 345 million by 2032 under the base scenario.
Recombinant Trypsin Solution Market
Two macro takeaways matter for 2026 planning: first, this is a growth market large enough to support multi-player competition but not so large as to render scale advantages irrelevant; second, the mid-single-digit-to-high-single-digit CAGR allows for disciplined investments in capacity, quality systems and customer-centric service offerings with reasonable payback horizons.
Recombinant Trypsin Solution Market
Why this preview matters for decisions in 2026
- Capital allocation and capacity planning: Firms making capacity investments in 2026 will be locking in utilization curves across the forecast window. With predictable demand growth, CAPEX choices should prioritize agility and compliance rather than raw scale alone.
- Product strategy and portfolio management: Buyers increasingly differentiate on animal‑free, GMP‑grade and excipient‑controlled enzyme products. Suppliers must choose where to invest — premium GMP offerings, broader catalogue breadth, or cost‑competitive standard reagents — to align with their go‑to‑market position.
- M&A and partnership timing: Market concentration metrics indicate a moderately consolidated industry. Strategic buyers and PE sponsors should use 2026 as an inflection year to consolidate niche capabilities (e.g., animal‑free GMP lines, specialty packaging, single‑use compatibility) before commoditization accelerates.
Structural dynamics shaping supplier economics
The market is governed by a set of recurring, high‑impact dynamics that translate directly into pricing power, margin stability and customer switching costs. Our full study models each of these inputs quantitatively; below is a condensed qualitative synthesis.
- Feedstock and fermentation economics: Recombinant trypsin production is fermentation‑intensive. Microbial fermentation feedstock volatility and R&D intensity are principal cost drivers. Firms that secure backward integration, long‑term raw material contracts, or proprietary expression systems can materially lower unit costs.
- Regulatory and quality barriers: FDA and EMA expectations for traceability, batch consistency and documented supply chains are non‑negotiable for suppliers targeting biopharma manufacturing accounts. High upfront compliance costs create defensible moats for suppliers with established GMP systems and validated QC workflows.
- Certification as a commercial gatekeeper: GMP accreditation and ISO 13485 (where relevant) have become de facto purchasing prerequisites for pharmaceutical buyers. Certification timelines affect time‑to‑market for entrants and create near‑term opportunities for incumbent vendors to monetize validated supply relationships.
- Labor and technical expertise constraints: Sophisticated recombinant DNA and downstream purification know‑how limit rapid geographic arbitrage. High production costs in developing regions constrain penetration absent technology transfer, licensing, or local regulatory acceptance.
Competitive landscape — who to watch
The market’s competitive frame blends multinational life science majors with specialized biotech enzyme manufacturers. The report’s competitive assessment includes strategic profiles, technology positioning, and go‑to‑market footprints for leading players.
- Established life science leaders: Firms with integrated portfolios for bioprocessing (e.g., major suppliers of reagents, consumables and analytics) are leveraging cross‑sell opportunities into large GMP manufacturing accounts. Their strength lies in brand trust, distribution scale, and bundled offering potential.
- Specialized enzyme manufacturers: Companies focused on enzyme R&D and manufacturing are differentiating through product purity, animal‑free claims, and process robustness. Recent new product launches underscore competition around GMP‑grade, animal‑free alternatives suitable for clinical and commercial biologics.
- Regional entrants and innovators: A cadre of Asia‑based and niche manufacturers is expanding capacity and pursuing cost‑effective supply models. Their competitiveness hinges on demonstrating consistent quality and regulatory acceptance in mature markets.
Notable recent market activity that signals product and regulatory priorities includes launches of GMP‑grade animal‑free trypsin lines by major and specialist vendors. These product introductions reflect buyer preference shifts toward fully documented, animal‑free inputs for cell dissociation and bioprocessing — a trend with direct implications for procurement specifications and supplier selection in 2026.
Market structure: concentration and implications
Concentration metrics indicate a market that is neither pure commodity nor tightly monopolized. The top three players capture a clear majority share of the market, and the top five widen that lead — a structure that benefits incumbents through established supplier relationships and scale in compliance investment while leaving room for nimble specialists to capture premium niches.
For strategy teams, the implication is straightforward: focus on capability gaps that incumbents under‑service (e.g., customized packaging, small‑batch GMP runs, local regulatory support), or build scale and certification to compete for major supply contracts.
Report contents and practical deliverables
The full PW Consulting report converts the above strategic framing into operational tools for 2026 action. Highlights include:
- Validated market sizing (historical and forecast) and scenario analysis based on alternative adoption and regulatory timelines.
- Granular segmentation (product form, application, region) with qualitative drivers for each cell and an executive matrix identifying high‑opportunity microsegments. Note: segment tables and discrete regional splits are withheld from this preview and available only in the full report.
- Supply chain heat maps and a unit cost model that isolates feedstock, fermentation, downstream processing and overhead to quantify margin levers.
- Regulatory pathway maps and procurement checklists for pharma and contract manufacturing organizations (CMOs), aligned to FDA/EMA expectations on traceability and batch consistency.
- Commercial playbooks: pricing strategies, contract structures, and partnership archetypes (distribution, OEM supply, co‑development) tailored to supplier scale and aspiration.
- Competitive scorecards and a prioritized M&A target list with due‑diligence templates focused on tech validation, capacity fit and regulatory posture.
High‑level strategic recommendations for 2026
- For incumbents: Double down on GMP/quality differentiation and long‑term supply contracts with biologics manufacturers. Introduce modular capacity investments (single‑use, flexible suites) to respond to spot demand without overcommitting CAPEX.
- For challengers and regional players: Pursue focused certification (GMP, ISO) and invest in demonstration batches and third‑party validations to shorten buyer acceptance cycles. Consider co‑supply partnerships or licensing with branded distributors to access regulated markets faster.
- For financial sponsors: Target bolt‑on assets that provide regulatory certifications, fill capability gaps (e.g., animal‑free excipient GMP production), or strengthen downstream purification IP to improve margins and exit multiples.
- For biotech and cell therapy developers: Reassess procurement specifications to balance cost and supply security: multi‑sourcing of qualified GMP materials, strategic safety stock policies, and contractual KPIs on batch traceability will mitigate supplier risk.
How to use this research in 2026 planning cycles
Procurement, operations, and corporate development teams should integrate the study into three typical 2026 decision workflows:
- Budgeting and CAPEX approval: Use the forecast scenarios and unit cost model to stress‑test ROI on capacity expansions or new product lines.
- Supplier qualification and sourcing: Apply the regulatory pathway maps and procurement checklists to shorten vendor qualification timelines and reduce audit friction.
- M&A and partnership diligence: Leverage the competitive scorecards and prioritized target list to screen opportunities and focus diligence on quality, regulatory readiness, and scale synergies.
Final word — the strategic value proposition of the full report
Our comprehensive study gives decision‑makers the quantitative forecasts, qualitative insight and executable tools necessary to move from tactical responses to proactive positioning in 2026. It translates macro growth assumptions (a projected mid‑high single digit CAGR across 2026–2032) into clear commercial levers: where to invest, which capabilities to buy, and how to negotiate supply and service terms with increasing buyer sophistication.
This preview is intended to orient and provoke the right strategic questions. The full report delivers the proprietary segment tables, regional and application breakouts, pricing curves and supplier scorecards that operational teams will need to act with confidence. Contact PW Consulting to obtain the complete study and the accompanying decision support pack, including model files and an implementation roadmap tailored to your organization’s role in the value chain.
For detailed analysis of this topic, please visit the official page: Recombinant Trypsin Solution Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com