

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Herbal Extracts Market to reach USD 77.0 Billion by 2032 at 8.4% CAGR — PW Consulting Insights

Herbal Extracts Market — 2026 Strategic Briefing
Executive snapshot
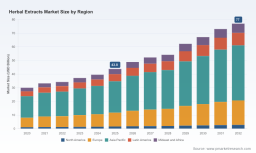
As the global herbal extracts market enters a new phase of structural expansion, PW Consulting’s latest market research (base year 2025, forecast period 2026–2032) frames the business choices that will define winners and laggards in 2026. The sector has expanded from roughly USD 30.0 Billion in 2020 to about USD 43.8 Billion in 2025 and is projected to continue growing at a compound annual growth rate (CAGR) of 8.4% through 2032, reaching an estimated USD 77.0 Billion by the end of the forecast horizon. These headline metrics capture a market that is sizeable, accelerating, and materially reshaping value chains across food & beverage, nutraceuticals, pharmaceuticals, and personal care.
Herbal Extracts Market
Why this research matters for 2026 decision-making
-
Timing: 2026 is a pivot year for investment and sourcing strategies as regulatory scrutiny tightens and premiumization accelerates. Companies that act now will lock better margins and lower compliance risk.
Herbal Extracts Market -
Signal-to-noise separation: Macro growth obscures differential performance at the subsegment level. Our study surfaces high-conviction growth pockets and the operational levers that convert market tailwinds into commercial outcomes.
Herbal Extracts Market -
Actionability: Beyond forecasts, the report provides executable playbooks—supplier due diligence, quality control protocols, regulatory risk heatmaps, and M&A screening models—crafted for 12–36 month execution cycles.
-
Risk mitigation: Recent contamination recalls and evolving EU import controls mean procurement, quality, and regulatory teams must recalibrate their control frameworks immediately.
What the report delivers (practical, non-generic inputs)
-
Market architecture and demand cascades: A layered view of end-markets and the commercial dynamics that shape ingredient selection, formulation preferences, and willingness-to-pay.
-
Historical performance and forward scenarios: A validated time series (2020–2025) and three forecast scenarios (conservative, base, upside) through 2032—anchored to leading indicators such as consumer-health adoption, regulatory tightening, and raw-material availability.
-
Supplier and product playbooks: Due diligence checklists, critical spec matrices, contract clauses for quality and traceability, and an editable supplier-scorecard you can use immediately in procurement cycles.
-
Regulatory & testing toolkit: A prioritized checklist of certifications, testing regimes, and lab-capability investments correlated to market exposure and buyer risk appetite.
-
M&A and partnership frameworks: Screening filters for acquisition targets (technology, sourcing, or market access plays), valuation sensitivities, and integration playbooks.
-
Commercial levers: Price-pack architecture guidance, margin capture tactics for co-developed bioactives, and tactics for private-label vs branded strategies.
Market dynamics you cannot ignore
-
Premiumization and certification premium: Organic credentials (e.g., EU Organic, USDA Organic) now drive price differentials and buyer selection in many developed markets. Brands that secure credible certification and transparent traceability earn both shelf premium and insurer/retailer confidence.
-
Regulatory tightening on imports: The European Union’s stepped-up audit program for non-EU imports and changes to sampling rules (including mycotoxin sampling references) materially increase compliance costs and time-to-market for suppliers outside major trade blocs.
-
Quality incidents are consequential: Recent recalls tied to heavy-metal contamination underscore how supplier lapses can trigger costly recalls and lasting brand erosion—requiring container-level traceability and accelerated testing protocols for at-risk botanicals.
-
Supply-side modernization: New manufacturing capacity and targeted product launches show a bifurcation: some suppliers are moving up the value chain (standardized bioactives, patented extracts) while others compete on scale and price. Both strategies co-exist profitably in different parts of the value chain.
-
Fragmented supplier base: Market concentration is low by ingredient-standards—meaning niche specialists, regional champions, and vertically integrated players all co-exist. This fragmentation generates opportunity for targeted M&A and exclusive supply relationships.
Competitive landscape — strategic takeaways
The market is populated by a mix of specialized botanical extract manufacturers, food-ingredient suppliers, and integrated natural-ingredient companies. Prominent players include manufacturers with roots in traditional extraction and herbology, global natural-ingredient houses serving F&B channels, and nutrition-focused firms developing standardized bioactives.
-
Arjuna Natural Extracts Ltd (Aluva, India): Strong position in standardized extracts and proprietary bioactive development for nutraceuticals and cosmeceuticals. Strategic advantage: deep product development capability and vertical sourcing relationships with spice- and herb-growing regions.
-
Sami Labs International Ltd (Bengaluru, India): Focus on standardized extracts and health-ingredient pipelines. Strategic advantage: combination of R&D-to-manufacturing capability suited to supplement and functional-food clients.
-
Bio-Botanica, Inc. (Scottsdale, USA): Emphasizes food- and beverage-grade botanical extracts and turnkey solutions. Strategic advantage: north-american compliance focus and convenience for F&B manufacturers.
-
Ingex Botanicals (Solan, India): High-quality botanical manufacturer with strengths in raw-material relationships and formulation support for F&B applications.
-
Naturex SA (Avignon, France): Global reach in natural ingredients for F&B with established formulation and distribution networks—well placed to serve multinational brands seeking single-supplier convenience.
-
Indena S.p.A. (Milan, Italy): Premium, standardized extracts with a track-record in nutraceutical and pharmaceutical use—a logical partner for clients seeking clinical-grade ingredients.
-
Kalsec Inc. (Kalamazoo, USA) and Döhler GmbH (Darmstadt, Germany): Suppliers with strong F&B orientation, leveraging herb and spice extract expertise and large-scale ingredient platforms to provide integrated solutions.
Together, these profiles show diversified strategic postures: specialization in bioactives, geographic/regulatory arbitrage, scale-based F&B supply, and premium standardized extracts for regulated markets. Market concentration metrics confirm a fragmented market—creating space for niche specialization and opportunistic consolidation.
Recent signals that change playbooks
-
Contamination-related recalls at retail level (early 2026 events) highlight the reputational and financial impact of supply-chain failures—pushing buyers to demand stronger incoming inspection and third-party laboratory verification.
-
New factory launches and targeted product introductions during 2025–2026 indicate sustained investment in capacity for specific botanical segments and a continuous flow of product-innovation opportunities.
-
Regulatory activity and increased RASFF reported issues in recent cycles should be treated as an operational headwind—one that can be mitigated by investing in sampling regimes, supplier audits, and pre-shipment certification.
A pragmatic 2026 playbook for executives
-
0–90 days: Perform a rapid supplier risk audit (including country-of-origin mapping, certification status, and traceability) for your top 20 SKUs. Tighten contractual quality clauses and establish stop-shipment triggers for out-of-spec results.
-
3–12 months: Invest in a tiered testing regime and a supplier development program that rewards certified and traceable supply. Pilot co-development agreements with 1–2 specialized extract providers to secure innovation advantages and margin capture.
-
12–36 months: Execute targeted M&A or long-term supply partnerships to secure strategic botanicals and proprietary bioactives. Build or partner for local processing capacity in key sourcing regions to shorten supply chains and manage compliance risk.
-
Ongoing: Maintain a regulatory-watch function tied to procurement and R&D so that changes in import controls, sampling rules, or maximum residue limits trigger immediate sourcing and testing adjustments.
Conclusion — where PW Consulting adds value
The herbal extracts market is growing, diverse, and increasingly shaped by regulatory pressure, certification premiums, and innovation in standardized bioactives. Our 2026-focused study translates growth projections and risk signals into operational priorities, commercial levers, and M&A targets. The dataset behind this briefing—detailed subsegment revenue splits, region and application breakouts, supplier maps, and proprietary scoring outputs—is intentionally reserved for the full report to ensure you receive the level of granularity required to make high-stakes decisions with confidence.
To access the full diagnostic dashboards, scenario models, and executable playbooks that support the above conclusions, please visit the PW Consulting report portal for the Herbal Extracts Market 2026 release.
For detailed analysis of this topic, please visit the official page: Herbal Extracts Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com