

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Automobile Carburetor Market to Reach USD 504M by 2032 at 2.8% CAGR

Automobile Carburetor Market: Strategic Outlook for 2026 Decision-Makers
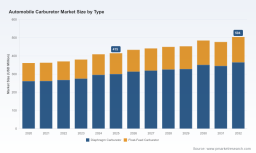
This introduction summarizes PW Consulting’s new market research on the global automobile carburetor market and explains its direct, actionable value for executive decision-making in 2026. Built on a 2020–2025 historical base with a 2026–2032 forecast horizon, the study quantifies market movement, isolates the structural forces reshaping demand, and translates those findings into near-term strategic options. At a macro level, the market expanded from approximately USD 361.0 million in 2020 to about USD 415.0 million in 2025, and — based on our central scenario — is projected to reach roughly USD 504.0 million by 2032, reflecting a compound annual growth rate (CAGR) of 2.8% over the forecast period. These aggregated trends matter for capital allocation, product roadmaps, and M&A prioritization in 2026.
Automobile Carburetor Market
Why this study matters in 2026
- Timing of transition: 2026 is a hinge year for powertrain strategy. Regulators and OEM product cycles are forcing clearer choices between defending legacy technologies and accelerating migration to fuel-injection and electrified architectures.
- Constrained growth, concentrated value: The market is modest in absolute size but presents pockets of profitable demand — notably in specialty, aftermarket, and non-road applications — where margins and brand premium remain accessible.
- Decision-critical inputs: Boards and strategy teams need robust demand scenarios, supplier risk maps, and investment-return estimates to justify near-term capex and M&A bets. Our research supplies those inputs in forms suitable for financial committees.
Core market dynamics
- Demand-side segmentation and persistence:
The headline numbers mask divergent micro-trends. While passenger vehicle adoption of advanced injection systems and electrification reduces carburetor content in new mass-market cars, stable-to-growing demand persists in motorcycles, small off-road machines, legacy vehicle servicing, and performance tuning. These demand pools exhibit different buyer behavior, warranty structures, and pricing elasticity — which is why one-size-fits-all strategies fail.
Automobile Carburetor Market - Regulatory pressure and compliance timelines:
Recent regulatory actions — including tighter emission standards implemented in major markets — accelerate the natural lifecycle decline in carburetor usage for new passenger cars. Policymakers targeting criteria pollutants and lifecycle emissions are compressing timelines for OEMs to retire carburetor architectures, while simultaneously creating aftermarket opportunities for compliance kits, retrofits, and permitted legacy servicing frameworks.
Automobile Carburetor Market - Technology and product evolution:
Manufacturers are bifurcating their product strategies: continuing to refine carburetor designs for niche and performance applications, while developing complementary retrofit or hybrid solutions that blend mechanical carburetion with electronic control elements. This hybrid approach allows suppliers to capture aftermarket replacement revenue and offer smoother transition paths for fleet operators with mixed vehicle portfolios.
- Supply chain and cost dynamics:
Parts commonality, materials selection, and manufacturing scale remain determinative of competitiveness. Suppliers with diversified metalworking, precision machining, and assembly footprints are better positioned to defend margins as volumes compress in core automotive segments. At the same time, aftermarket distribution and technical support networks drive lifetime value and recurring revenue streams.
Regulatory context shaping strategy
- China’s upgraded light-duty vehicle emission standards and Europe’s phased Euro 7 implementation are hastening the decline of carburetors in passenger car applications and raising the cost of non-compliance for OEMs.
- Subnational rules, such as California’s evolving zero-emission vehicle criteria for passenger fleets and legacy vehicle controls, create geography-specific timelines and carve-outs that affect aftermarket demand and retrofit economics.
- These overlapping policy frameworks produce a differentiated landscape in which regulatory arbitrage and targeted compliance product lines can be lucrative — but only for firms that align product development, certification resources, and distribution footprints to the jurisdictional realities.
Competitive landscape — players to watch
The market is served by a mix of global OEM suppliers, specialist niche manufacturers, and aftermarket performance brands. Key firms profiled in our study include:
- Keihin (Tokyo, Japan)
A leading global OEM supplier historically focused on carburetors and fuel systems for two- and four-wheel applications. Following corporate restructuring and integration into a larger automotive systems entity, Keihin has broadened its R&D and production footprint, enabling integrated powertrain offerings that blend legacy expertise with newer fuel-delivery systems.
- Mikuni (Tokyo, Japan)
Specialist manufacturer with deep roots in motorcycle, powersports, and aftermarket carburation. Mikuni’s product strategy centers on high-performance and rebuildable product lines that support both OEM and aftermarket channels.
- Walbro (Prescott, Arizona, USA)
Supplier focused on small-engine and automotive carburetors, with strengths in application engineering, catalog management, and replacement fitment data for aftermarket channels.
- Holley (Bowling Green, Kentucky, USA)
Brand-focused supplier of high-performance carburetors and fuel systems, with strong consumer recognition in the performance aftermarket and motorsports communities.
- Edelbrock (Olive Branch, Mississippi, USA)
Performance-oriented producer with a stable of product offerings and reputation-driven customer loyalty within enthusiast segments.
Recent company activity illustrates how competitors are defending and reshaping their addressable markets: Holley issued an expanded product catalog in June 2026 that doubles down on high-performance carburetor and EFI systems; Mikuni launched new racing carburetors and rebuild kits in June 2026 aimed at both motorsports and service channels; and Walbro updated its fitment and technical documentation in May 2026 to reduce aftermarket compatibility friction. These moves evidence two practical strategic themes: incumbents are investing in product refreshes to defend aftermarket share, and they are coupling legacy product strengths with electronic or hybrid solutions to stay relevant as regulatory pressure increases.
What the PW Consulting report delivers (practical, board-ready assets)
- Granular demand model and forecasting engine (2026–2032) built on historical unit flows and price-realization assumptions — provided in configurable formats for financial modeling.
- Scenario analyses (fast-decline, central, and extension-of-life) that stress-test investment returns across regulatory and technology inflection points.
- Supplier scorecards that rank manufacturers against capacity, cost, product breadth, distribution reach, and transition-readiness — designed for procurement and M&A screening.
- Aftermarket channel maps and go-to-market playbooks for performance, service, and parts-distribution partners, including retrofit product commercialization templates.
- Regulatory impact matrix tied to certification timelines and compliance cost estimates across major jurisdictions, with suggested compliance roadmaps.
- M&A and joint-venture playbook: target profiles, valuation sensitivities, and integration checklists for acquiring technology, service networks, or regional manufacturing footholds.
- Interactive executive dashboard snapshots summarizing revenue, margin, and risk exposures by aggregated segments — accessible for board reporting and investor updates.
Note: This introduction highlights the practical deliverables; the detailed sub-segmentation tables and firm-level financials are available in the full report and interactive datasets.
Strategic implications and recommended actions for 2026
- For OEMs:
Prioritize module-level decisions: de-risk legacy platforms through supplier conversion agreements, and evaluate hybrid retrofit options that can be marketed for compliance and fleet applications. Preserve service revenue by embedding authorized refurbishment and certification programs into warranty systems.
- For Tier suppliers and manufacturers:
Segment R&D and manufacturing investments between defending aftermarket/performance niches and developing hybrid/electronic-enabled offerings. Lock down parts-sourcing and alternative workflows to maintain margin stability as mainstream volumes compress.
- For aftermarket distributors and service chains:
Invest in technical training, parts traceability, and certification services. Launch targeted campaigns to capture legacy fleet owners and performance enthusiasts, using bundled retrofit and emissions-compliance packages as a value proposition.
- For investors and M&A teams:
Screen for targets offering stable aftermarket cash flows, proprietary rebuildable product designs, or hybrid-electronic IP. Pay attention to firms with strong channel relationships and modular manufacturing that can be repurposed across non-automotive applications.
How to convert research into boardroom decisions
- Use our scenario outputs to set capital allocation thresholds: tie multi-year capex commitments to regulatory trigger points and market-share outcomes under each scenario.
- Run supplier and product scorecards through due-diligence checklists prior to any acquisition; prioritize targets with clear retrofit pathways and lower certification burden.
- Integrate the aftermarket monetization playbooks into service and digital strategies; recurring revenue from maintenance and rebuild kits can meaningfully offset unit-volume declines in core automotive segments.
- Adopt a staged product retirement and upgrade timeline that aligns with regional regulatory calendars to avoid stranded inventory and to maximize revenue from transition products.
PW Consulting’s full report provides the data tables, company scorecards, and executable templates referenced above. This introduction outlines the high-value strategic levers and near-term moves that senior executives should consider in 2026. To access the detailed segmentation, regional and application-level forecasts, and downloadable financial models that drive these recommendations, review the full report and interactive datasets available through our publication portal.
For detailed analysis of this topic, please visit the official page: Automobile Carburetor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com