

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: LSA Market to grow at 4.85% CAGR, reaching USD 844.73 Million by 2032

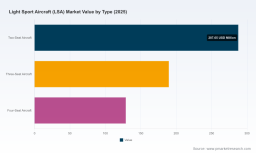
Light Sport Aircraft (LSA) Market — 2026 Strategic Briefing
Executive snapshot
As the Light Sport Aircraft (LSA) market moves from regulatory transition into a phase of commercial realignment, executive teams face a compressed window to translate new rules into competitive advantage. Our PW Consulting base-year assessment (2025) and forward-looking projection through 2032 show a market growing at a steady mid-single-digit compound annual growth rate (CAGR) of 4.85% over the 2026–2032 forecast horizon. That trajectory reflects a market that is neither nascent nor saturated — attractive to focused OEMs, aftermarket specialists, and financial sponsors prepared to act on regulatory-driven demand and product-upgrade cycles.
Light Sport Aircraft (LSA) Market
Why this study matters for 2026 decision-makers
- Regulatory inflection is a strategic lever. The rule changes finalized in 2025 materially alter the product and certification economics for LSA manufacturers — creating opportunities for new model classes and reshaping entry barriers.
- Investment timing is critical. With certification pathways and pilot privileges decoupled across interim timelines, companies that sequence product development and regulatory engagement correctly can capture early adopters and establish durable service footprints.
- Moderate market concentration leaves room for scale plays. Market concentration metrics indicate meaningful shares are held by top firms, but there remains substantial room for consolidation, niche specialization, and geographic expansion.
- Operational readiness wins. Supply-chain resilience, aftermarket capability, and certified maintenance infrastructure will differentiate winners in a market where time-to-certify and time-to-service matter as much as aircraft performance.
Regulatory inflection — MOSAIC and certification realities
The MOSAIC rule finalized by the FAA in July 2025 is the single most consequential change driving 2026 strategic choices. By moving toward performance-based eligibility for light aircraft (including higher maximums for weight and seating capacity under defined performance envelopes), MOSAIC expands the design space available to manufacturers while also imposing new conformity requirements. Key operational facts that matter for strategy include staggered effective dates for pilot privileges and certification, new expectations for consensus-standard compliance, and tighter notification and oversight processes for new make/model combinations.
Light Sport Aircraft (LSA) Market
For manufacturers and suppliers this means multiple near-term imperatives: (1) update certification roadmaps to align with the new performance-based definition and demonstration evidence requirements; (2) formalize engagement with recognized industry consensus standards organizations to avoid unnecessary certification friction; (3) revisit production-control and quality-assurance architectures, since SLSA pathways now require demonstrable alignment with accepted design and production standards; and (4) strengthen regulatory affairs capability to manage the notification process for new make/model combinations and to coordinate with Aviation Safety Inspectors on special airworthiness certificate issuance.
Light Sport Aircraft (LSA) Market
Market structure and competitive landscape
The competitive environment is diverse and geographically distributed, encompassing small specialist builders, legacy general‑aviation marques, and regionally focused manufacturers. Representative firms across the industry illustrate the breadth of strategies in play — from lightweight, weight‑shift models and amphibious designs to high-performance fixed-wing LSA entries and STOL-capable aircraft. Companies such as Tecnam, CubCrafters, and legacy general-aviation OEMs operate alongside highly specialized builders producing amphibious, ultralight, and kit-derived models. The prevalence of common engine platforms and well-established component suppliers creates both opportunities for scale and risks around supplier concentration.
Concentration metrics reinforce a market with meaningful leaders but ample room for disruptive entrants: the top three and top five players command a notable portion of the market, yet the majority of demand remains accessible to mid-sized and niche participants. That structure supports several viable strategic plays: consolidation by roll-up, targeted product differentiation (e.g., amphibious, short-field, weight-shift), and aftermarket-centric business models focused on training, service, and parts.
Competitive snapshot — what firms are doing
- Regional OEMs are doubling down on model lineups that emphasize ease-of-maintenance and modularity to shorten certification timelines and support rapid field upgrades.
- Specialist manufacturers are leveraging niche capabilities — amphibious hull design, weight‑shift expertise, or STOL performance — to defend high-margin niches while selectively pursuing broader market certification.
- Some well-known general-aviation names are positioning LSA variants as feeder products into wider pilot pipelines and flight‑training ecosystems, recognizing the downstream value of conversion to larger aircraft types.
- Across the supply chain, propulsion and avionics suppliers are offering integrated, certifiable bundles aimed at simplifying SLSA manufacturer certification demonstrations under consensus standards.
Strategic implications for OEMs, suppliers, and investors
- Product and certification sequencing. For OEMs planning new models, prioritize architectures that can demonstrate compliance under the performance-based framework with minimal design rework. Early engagement with consensus‑standards bodies and FAA channels reduces certification risk and shortens commercialization timelines.
- Aftermarket and service as growth engines. Given the expected fleet expansion and pilot-training implications of the regulatory change, establishing regional maintenance, repair, and overhaul (MRO) networks and training partnerships will unlock recurring revenue and customer retention.
- Supply-chain de-risking. Map and qualify alternate suppliers for critical systems (propulsion, flight controls, avionics) — particularly those with prior certifiable footprints — to avoid bottlenecks as production ramps.
- M&A and partnership playbook. Targets should be evaluated for certification-ready designs, demonstrable quality systems, and service footprints that complement a buyer’s geographic or capability gaps. Mid-market consolidation can accelerate scale benefits while preserving brand value in specialized niches.
- Investor due diligence. Financial sponsors should prioritize asset-level regulatory defensibility, the durability of aftermarket revenue, and realistic timelines for production and certification in valuation models.
What the PW Consulting report delivers — practical, ready-to-execute intelligence
Our full LSA Market study is structured to convert insight into action. Highlights include:
- Robust market-sizing methodology and scenario models (base-year 2025, forecast period 2026–2032) that allow stress-testing across regulatory, economic, and supply scenarios.
- Regulatory impact matrix with decision gates and an operational playbook for complying with the MOSAIC performance-based criteria, Partnership for Safety Plan expectations, and make/model notification flows.
- Competitor playbooks and scorecards that evaluate product portfolios, certification status, go-to-market strategies, service networks, and balance-sheet strength — enabling rapid identification of acquisition or partnership targets.
- Supply-chain maps and risk heatmaps, including propulsion, avionics, and critical structure suppliers, with mitigation strategies and alternate-sourcing options.
- Commercial scenarios and pricing frameworks that translate forecast demand into production ramp profiles, required capex, and break-even timelines for new entrants and incumbents.
- Aftermarket and training ecosystem analysis that quantifies serviceable available market drivers and suggests scalable business models for MRO and pilot training partnerships.
- Safety and operational risk assessment leveraging contemporary SLSA continued operational safety data to prioritize product and training investments that materially lower fleet risk and liability exposure.
How to use this intelligence — 90/180/360 day playbook
- 0–90 days: Regulatory triage and certification alignment. Update certification roadmaps, appoint regulatory liaisons, and prioritize model configurations that minimize demonstration burden under MOSAIC.
- 90–180 days: Commercial and operational preparation. Lock key supplier agreements, pilot a regional service hub, and launch targeted marketing to training schools and early-adopter owners.
- 180–360 days: Scale and capture. Execute production ramps, expand aftermarket capability, and evaluate strategic M&A to secure complementary product lines or service networks that accelerate market share gains.
Final perspective and next steps
The LSA market entering 2026 is not a simple earnings story — it is a regulatory and capability transformation. The MOSAIC rule reframes what an LSA can be, who can build and certify one, and how value is created over the aircraft lifecycle. For executives, investors, and planners, the decisions made in the next 12–18 months — particularly around certification pathway selection, supplier commitments, and aftermarket infrastructure — will disproportionately determine market outcomes through 2032.
The PW Consulting LSA Market study provides the granular, actionable intelligence required to make those decisions with confidence: from certification playbooks and competitor scorecards to scenario-tested demand models and MRO rollout plans. To preserve strategic advantage, this briefing intentionally highlights the high-level dynamics; detailed regional, application, and model-level financials and heatmaps are available in the full report. Access the complete study or contact our advisory team to commission tailored scenario workstreams and execution support.
For detailed analysis of this topic, please visit the official page: Light Sport Aircraft (LSA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com