

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Cold Mix Asphalt Additives Market to Hit USD 701M by 2032 at 4.92% CAGR

Cold Mix Asphalt Additives: Strategic Outlook for 2026 — A PW Consulting Preview
Executive snapshot
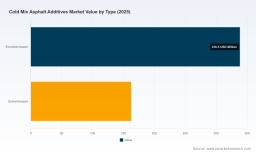
The cold mix asphalt additives market is maturing from a sustainability-driven niche into a strategic category for materials, infrastructure and public-works decision-makers. Our PW Consulting base-year assessment (2025) and 2026–2032 forecast identify a steady expansion path underpinned by procurement mandates, shifting raw material economics and product innovation. The total market grew from approximately 402 Million USD in 2020 to about 501 Million USD in 2025; under our central case it continues to expand at a compound annual growth rate of roughly 4.9%, with full-year market size crossing the 700 Million USD mark in the later stages of the forecast horizon. For 2026 decision-makers, this is a market large and liquid enough to warrant strategic resource allocation but still fragmented enough to reward decisive moves on product differentiation, supply resilience and regulatory positioning.
Cold Mix Asphalt Additives Market
Why this preview matters for 2026 corporate decisions
- Portfolio prioritization: Capital allocation choices — R&D vs. M&A vs. commercial rollout — can materially alter medium-term share in a market growing at near 5% annually. The most value-accretive plays in 2026 will be those that reconcile sustainability claims with cost-to-serve realities.
- Regulatory arbitrage and market access: Compliance roadmaps for REACH, state-level chemical disclosures (e.g., California’s frameworks) and analogous regimes in Australia/Canada materially influence launch timing and go-to-market cost. Firms that internalize toxicology/regulatory spend as part of product lifecycle planning will avoid commercial delays.
- Procurement and contracting: Municipalities and large contractors adopting green procurement create predictable demand corridors. Buyers should incorporate cold-mix specifications in multi-year contracts to lock in sustainability benefits without sacrificing performance.
Market dynamics: tailwinds, constraints and structural signals
The market is being reshaped by four interacting forces:
Cold Mix Asphalt Additives Market
- Decarbonization and life-cycle economics. Cold mix application enables significant on-site energy savings and CO₂ reductions versus conventional hot mix asphalt because it eliminates or reduces the need for heating to high temperatures. Peer-reviewed and industry-sourced studies indicate meaningful energy and emissions delta — a central value proposition for public agencies aiming to meet net-zero timelines.
- Regulatory complexity raises barriers to entry. Chemical additive vendors face increasingly stringent pre-market requirements in multiple jurisdictions. Conformance to REACH or to state-level disclosure regimes materially increases time-to-market and up-front development spend for novel chemistries and bio-based formulations.
- Raw material volatility. Feedstock price swings in crude oil and petrochemicals pass through to adhesive and emulsifier costs, compressing margins for incumbent petroleum-derived formulations while improving the relative economics of bio-based alternatives — even when those alternatives command a premium.
- Sustainability premium and product differentiation. Bio-based and carbon-sequestering innovations (e.g., biochar-infused cold mixes) are emerging. These innovations attract premium pricing (industry evidence suggests a typical 15–25% price premium for bio-based alternatives) while delivering performance benefits that can justify higher procurement unit prices under green procurement rules.
Competitive landscape: who matters and why
The competitive field is a mixture of chemical majors, specialty polymers firms, and innovative start-ups. Market concentration is moderate; the top three players do not dominate the market entirely, leaving room for regional leaders and technology-first entrants. Our assessment focuses on two illustrative players to highlight strategic choices.
Cold Mix Asphalt Additives Market
- Arkema SA (Courbevoie, France) — Arkema leverages a branded additive portfolio that emphasizes adhesion and moisture displacement for cold patch longevity. Their ColdGrip® solutions illustrate a classical incumbent strategy: product line extensions that target performance reliability, compatibility with existing paving mixes, and regulatory compliance pathways in major jurisdictions. For investors and partners, Arkema’s playbook underscores the importance of legacy distribution, technical support and regulatory dossiers as durable competitive advantages.
- Cargill (Minneapolis, United States) — Cargill’s Anova line highlights a different vector: bio-based, polymer-modified formulations that support high recycled-content mixes and low volatile organic compound (VOC) emissions. The product messaging aligns directly with municipal and contractor demand for circular-material solutions and year‑round applicability. Cargill’s vertically integrated supply model and bio-based positioning demonstrate how agricultural feedstock and polymer science can be deployed to capture the sustainability premium.
Recent industry developments reinforce these strategic themes. In mid‑2025 a major supplier launched a polymer-modified, bio-based entry that promotes very high recycled asphalt pavement (RAP) incorporation and reduced VOCs; later in the year another innovator introduced a biochar‑infused cold mix capable of measurable carbon sequestration. These product introductions confirm two concurrent market tracks: performance-first formulations that reduce life-cycle costs, and purpose-built, eco‑differentiated products that enable procurement compliance and premium pricing.
What the full PW Consulting report contains (practical modules)
Our research is designed for commercial leaders, product managers, procurement heads and corporate strategy teams who must make decisive choices in 2026. The full report — summarized here in structure — delivers operational intelligence rather than broad rhetoric:
- Market sizing and trend analysis: base‑year (2025) benchmarks, a five‑year historical series and a seven‑year forecast horizon with sensitivity scenarios reflecting raw material shocks, accelerated green procurement and regulatory delays.
- Demand-by-use-case modeling: performance thresholds, lifecycle cost comparisons vs. hot mix, and buyer elasticity estimates that support pricing strategy for premium bio-based formulations.
- Supply-side assessment: vendor scoring across technical capability, regulatory readiness, manufacturing footprint and distribution channels; supplier risk indices that quantify concentration and single-source exposure.
- Regulatory and compliance matrix: jurisdictional timelines, toxicology dossier requirements, and cost-to-compliance estimates to inform market-entry sequencing and R&D prioritization.
- Commercial playbooks: GTM options for incumbents and challengers, channel strategies for selling to contractors vs. public agencies, and contracting templates that capture sustainability premiums.
- Capex and operating models: build vs. buy analysis for manufacturing expansion, contract manufacturing options and input-cost hedging strategies tied to petrochemical price scenarios.
- Case studies and pilot frameworks: success criteria for roadway projects, measurement protocols for energy and emissions savings, and procurement language that operational teams can reuse.
How to use this intelligence in 2026 — concrete next steps
Here is a prioritized checklist for executives preparing decisions this year:
- Run a 12‑ to 24‑month pilot program that pairs a bio-based additive with high‑RAP mixes and a control hot mix lane. Use standardized LCA and performance testing to create defensible commercial claims for tenders.
- Map regulatory exposure by target market and allocate a compliance fund in your 2026 budget. Anticipate toxicology studies and dossier preparation timelines in your product launch milestones.
- Hedge feedstock risk through a mixed-sourcing strategy: contract for agricultural feedstocks where bio-based inputs are used, and maintain spot/pipeline arrangements for petrochemical-derived intermediates.
- Revise pricing architecture to capture a sustainability premium where procurers are willing to pay for carbon savings or circular content. Build outcome‑based contracting templates (e.g., pay-for-performance on pothole recurrence or lifecycle emissions) for public-sector clients.
- Assess M&A and partnership targets that provide either process chemistry capabilities (emulsifiers/adhesion promoters) or route-to-market in high-demand municipal corridors.
Why PW Consulting’s analysis is distinctive
Three features differentiate this research:
- Integrated modeling: our demand-driver models combine procurement policy scenarios, raw material price paths and adoption curves derived from public procurement data and contractor surveys.
- Operational focus: deliverables include reusable templates, supplier scorecards and cost models that translate market intelligence into executable plans — not just descriptive analysis.
- Scenario rigor: alongside a central forecast (CAGR ~4.9%), we provide upside and downside cases that stress-test investment and market-entry timing against plausible regulatory or feedstock shocks.
Closing — what we intentionally withhold here and how to get it
This preview demonstrates the strategic value of the full study for 2026 planning: it shows growth trajectories, identifies the dominant competitive playbooks, and translates macro signals into operational next steps. To preserve the commercial utility of our granular work we have deliberately withheld certain core segmented tables (regional and application split-by-dollar figures, detailed per-segment pricing grids and supplier-specific revenue runs). These items are available in the full report package, which also contains downloadable Excel models and procurement templates that can be executed immediately by commercial teams.
For companies preparing 2026 budgets, R&D roadmaps, or M&A screens, the PW Consulting Cold Mix Asphalt Additives Market study is intended to be the decision-support spine: a single source that turns sustainability opportunity and regulatory complexity into clear commercial options. Contact PW Consulting to access the full dataset, scenario models and playbooks to convert this market trajectory into a competitive advantage.
For detailed analysis of this topic, please visit the official page: Cold Mix Asphalt Additives Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com