

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: LED Street Lighting Market to Hit USD 9,432M in 2025; 5.28% CAGR (2026-2032)

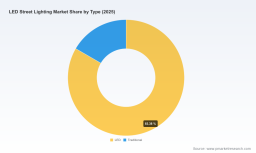
LED Street Lighting Market — Strategic Outlook for 2026 Decision Makers
As public authorities, utilities, and private infrastructure investors look to accelerate decarbonization, improve urban safety, and reduce operating expenditures, LED street lighting stands at the intersection of capital planning and smart-city modernization. This briefing frames PW Consulting’s new LED Street Lighting Market report as the essential strategic tool for organizations making decisions in 2026 — it synthesizes market trajectory, competitive dynamics, regulation-driven demand, cost pressures, and executional playbooks into a concise, decision-ready narrative.
LED Street Lighting Market
Why this study matters for 2026
The LED street lighting market is in a transitionary phase where steady market expansion converges with disruptive cost and regulatory vectors. Using 2025 as the base year, our model projects continued growth through the 2026–2032 forecast window at a compound annual growth rate (CAGR) of 5.28%. In revenue terms, the market sits in the multi‑billion USD range and moves toward a materially larger footprint by the end of the forecast period. For decision makers in 2026, that trajectory means procurement windows remain open, but timing, specification, and risk-mitigation choices will determine whether projects capture full lifecycle savings or underperform relative to expectations.
LED Street Lighting Market
Key takeaways for corporate and municipal leaders
- Adopt a two-speed procurement posture: prioritize immediate retrofits where simple paybacks are clear, and stagger complex smart-city integrations to benefit from maturing interoperability standards and falling premium component costs.
- Price volatility requires hedges: raw material spikes — notably in precious and base metals — have amplified component cost risk. Procurement strategies must include indexed pricing clauses, fixed-price tranches, or supplier partnerships with vertical integration to protect margins.
- Regulation is an accelerator: policy levers and municipal asset transfers are creating pockets of rapid adoption; projects with regulatory tailwinds deliver predictable demand and simpler financing pathways.
- Vendor selection is becoming more strategic: market concentration indicates leading vendors hold substantial share, but a strong cohort of specialized manufacturers and integrators enables competitive sourcing for differentiated requirements.
Market trajectory and what the numbers imply
Our bottom‑up revenue model reconciles historical installations, replacement cycles, urbanization trends, and energy-cost arbitrage to arrive at the market path embedded in the report. With a baseline anchored in 2025 and a forecast CAGR of 5.28%, the market demonstrates resilient long-term demand rather than a short-lived surge. For capital planners this translates into predictable replacement demand and growth in advanced-specification segments (controls, dimming, analytics). The implication is straightforward: vendors that can deliver verifiable lifecycle benefits and interoperable controls will capture disproportionate value as procurement shifts from capex-only thinking to integrated TCO optimisation.
LED Street Lighting Market
Report highlights — actionable content you can apply immediately
PW Consulting designed this study to move beyond descriptive analytics. The report contains practical modules intended to be used directly in 2026 project workstreams:
- Market sizing methodology and sensitivity models — replicate our forecasts with alternate energy-price and component-cost scenarios.
- Procurement playbook — RFP templates, contractual clauses for price-indexing and performance guarantees, and supplier evaluation matrices tailored to municipal, utility, and private-sector buyers.
- Lifecycle cost and carbon calculator — standardized templates that quantify energy savings, maintenance delta, and embedded carbon across common replacement scenarios.
- Smart-integration roadmap — stepwise approaches for migrating from standalone luminaires to networked, sensor-rich infrastructure without stranded investment.
- Project-level business case templates — CAPEX/OPEX models that finance teams can plug into to source debt, performance contracting, or hybrid funding structures.
- Operational optimization playbook — maintenance, remote diagnostics, and workforce transition guidance for service providers and municipal departments.
- Risk & mitigation matrices — covering supply-chain disruption, raw-material cost spikes, standards/regulatory changes, and cybersecurity for connected lighting systems.
Competitive landscape — what to watch in 2026
The competitive environment blends global platform providers, regional specialists, and systems integrators. Market concentration shows that leading firms hold meaningful share, but a broad set of capable suppliers remains. For buyers and investors, the choice is rarely about price alone — it is about demonstrated efficacy, durability, service model, and integration-readiness.
- Acuity Brands (Atlanta, GA): a supplier with a deep municipal and transportation footprint; strengths include proven roadway luminaires and bundled smart-control offers suited for large-scale retrofits with O&M components.
- Signify (Eindhoven): leverages platform-level capabilities (smart-city software and connected lighting systems) to compete on systems performance and data monetization potential.
- Eaton Corporation (Dublin): positions around high-efficacy fixtures and an established presence in infrastructure projects, which supports predictable performance in municipal procurement cycles.
- Cree Lighting (Durham, NC): focuses on high-efficiency fixtures with engineering emphasis on lumen output and thermal management — important for long-term lumen maintenance and warranty risk.
- Specialists and regional players: firms such as LEOTEK, Evluma, TRT Lighting, ZGSM, and Schréder occupy niches ranging from turnkey citywide upgrades to highly efficient modular products and tool-free maintenance designs.
Recent product launches in early 2026 illustrate competitive differentiation: modular, surge-protected roadway luminaires with broad lumen ranges target utilities requiring robust durability, while high-efficacy designs with tool-free maintenance appeal to municipalities prioritizing rapid deployment and low labor intensity. These developments underscore a strategic split in the market: scale-oriented, platform-enabled solutions versus nimble, efficiency-optimized fixtures for retrofit programs.
Regulation and macro drivers — the non-negotiables
Policy dynamics are central to demand formation. National and local regulations — from municipal asset transfers to mandated energy-efficiency targets — directly influence project economics and ownership models. For example, long-term U.S. energy-efficiency roadmaps signal that LED installations will dominate future incremental installs and deliver substantial system-level energy savings. Similarly, municipal-level asset ownership changes in select emerging markets have created procurement urgency and attractive payback profiles for LED retrofits. These regulatory tailwinds reduce demand uncertainty and can enable innovative financing structures such as energy-savings performance contracts.
Supply-side pressures and risk mitigation
Component-cost inflation has emerged as a primary execution risk. Significant year-over-year increases in prices for key metals and electronic components are elevating bill-of-materials costs and compressing margins for vendors that cannot lock in supply or vertically integrate. For 2026 decision-makers, it is essential to:
- build price-variation clauses into contracts,
- consider multi-supplier strategies for critical components, and
- evaluate total-cost-of-ownership under multiple raw-material price scenarios as part of the project approval process.
How to use this report in your 2026 planning cycle
Integrate our study into three core planning activities this year:
- Capital budgeting: use the lifecycle templates and sensitivity analyses to normalize project ranks across energy, maintenance, and resilience criteria.
- Procurement strategy: deploy the RFP archetypes and evaluation matrices to secure favorable contract terms that protect against component-cost volatility and specify measurable performance outcomes.
- Vendor engagement: apply the competitive profiles and due-diligence checklists to shortlist suppliers capable of meeting both near-term rollout needs and medium-term smart-city aspirations.
What the report does not do — and why that matters
Consistent with PW Consulting’s “trailer” approach, this introduction provides strategic insight and synthesized market direction without disclosing detailed sub-segment allocations or proprietary vendor revenue splits. The full report contains the granular regional, application, and type-level analytics, along with downloadable models and supplier scorecards necessary to operationalize the findings. This approach protects sensitive, commercially valuable detail while allowing decision-makers to assess the study’s relevance rapidly.
Next steps — for procurement leads, utility planners and investors
If your 2026 roadmap includes street lighting upgrades, networked-lighting pilots, or citywide retrofit programs, PW Consulting’s full report will accelerate your timeline. It provides the scenario-tested forecasts, contractual language, financial models, and competitive intelligence required to move from strategy to execution with defensible economics.
For executives looking to convert intent into deliverables: prioritize an initial 90-day assessment using the report’s project-level templates, then transition to a three-phase deployment plan aligned with procurement cycles and supplier capacity. Our team can support rapid implementation diagnostics and tailored vendor negotiation playbooks upon request.
Conclusion
LED street lighting is no longer a niche retrofit option — it is an infrastructure lever for energy efficiency, urban resilience, and smart-city enablement. In 2026, the market environment rewards disciplined procurement, scenario-informed budgeting, and vendors with verifiable lifecycle performance. PW Consulting’s LED Street Lighting Market report equips leaders with the frameworks and tools needed to make those judgments confidently. For full access to the granular segmentation, vendor scorecards, and downloadable financial models, refer to the complete report available through PW Consulting.
For detailed analysis of this topic, please visit the official page: LED Street Lighting Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com