

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Monofilament Fishing Line Market set to reach USD 568M by 2032 at 4.2% CAGR

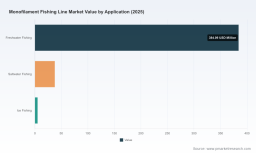
Monofilament Fishing Line Market — Strategic Briefing for 2026 Decision-Making
As PW Consulting’s lead industry analyst, I present a concise, strategy-focused introduction to our full Monofilament Fishing Line Market study. This briefing synthesizes the market’s macro trajectory, competitive dynamics, regulatory inflection points, and near-term playbook priorities that should shape corporate decisions in 2026. It is designed to demonstrate the depth and rigor of our analysis while reserving the granular segment-level datapoints for the full report and downloadable models.
Monofilament Fishing Line Market
High-level market view
-
Base year and scope: Our study uses 2025 as the base year and reviews historical performance across 2020–2025, with forward projections covering 2026–2032.
Monofilament Fishing Line Market -
Size and growth: The global monofilament fishing line market stood at approximately USD 427.0 Million in 2025. Using scenario-normalized demand drivers and cost pass-through assumptions, our core forecast models project a steady expansion to a market approaching USD 568 Million by 2032 — an implied compound annual growth rate (CAGR) of roughly 4.2% for the forecast interval.
Monofilament Fishing Line Market -
Concentration: Market concentration is moderate. The top-three players account for a meaningful share but do not create an insurmountable entry barrier; the top-five aggregate share rises further, indicating room for mid-sized specialists and innovative entrants to scale through product or channel differentiation.
Why 2026 is a strategic inflection point
-
Cost volatility and input risk: The feedstock base for monofilament — primarily nylon polymers — remains exposed to crude oil price cycles. Historical volatility since early 2022 underscores the potential for raw material cost shocks to compress margins or force price adjustments if manufacturers cannot rapidly pass through increases.
-
Regulatory acceleration: A cluster of state-level restrictions and federal reporting requirements on PFAS, along with tightening product standards, create near-term compliance imperatives. These rules are shifting formulation strategies, labeling, and testing budgets for manufacturers and private-label brands.
-
Consumer and retail forces: Retail channels and specialty distributors are increasingly rewarding sustainability credentials and circularity claims. Early movers who can credibly demonstrate recycled-content products, verified supply chains, and reduced chemical footprints gain access to premium channels.
Key market dynamics and implications
-
Raw material dynamics — volatility and hedging: Crude price volatility since 2022 has materially affected nylon resin costs. Companies that adopt disciplined hedging programs, multi-sourcing strategies, and closer supplier collaboration can stabilize gross margins. Our report includes sensitivity tables that quantify margin swings under alternate oil price scenarios.
-
Regulatory and compliance pressure: Several U.S. states and federal agencies have moved to restrict PFAS in consumer articles and to increase reporting obligations. For manufacturers, this translates into reformulation timelines, testing and certification costs, and potential market access limitations in certain jurisdictions. Strategic responses include dedicated compliance roadmaps, investment in alternative chemistries, and targeted SKU rationalization.
-
Sustainability as competitive advantage: Recycled-content and take-back initiatives are shifting from marketing niceties to source-of-differentiation. We document early commercial launches that signal the market’s direction and map the cost-to-value trade-offs for adopting recycled feedstocks at scale.
-
Channel evolution: Specialty outdoor retailers, e-commerce, and OEM partnerships are influencing assortment decisions. Private-label purchases and bundled offerings (rod + reel + line) create margin and share opportunities for suppliers who can deliver consistent quality at competitive price points.
Competitive landscape — who matters and why
-
Legacy brands with scale and distribution: Established manufacturers retain advantages via recognized brand names, broad distribution networks, and historical technical expertise in line construction and coating technologies. These firms are defending core categories while selectively investing in sustainability and product innovation.
-
Specialists and innovators: Smaller, technically focused companies continue to challenge incumbents with niche products, formulation advances, and agility in responding to regulatory or consumer demand shifts. We observe targeted launches that combine recycled content and improved mechanical properties aimed at premium segments.
-
Competitive signals to watch: New product introductions emphasizing recycled material content, formulation changes to avoid regulated substances, and partnerships with testing labs and recyclers. These moves are early indicators of which firms are positioning for regulatory and consumer shifts rather than reacting after market share erosion.
Representative vendor profiles and strategic posture
-
Leading heritage manufacturers leverage strong brand equity and broad dealer relationships to defend value. Their key levers include steady product R&D investments, layered SKU strategies, and selective premiumization.
-
Specialist brands and regional players focus on performance claims, material innovation, or localized compliance solutions. Several have already piloted recycled-content lines and are testing consumer willingness to trade price for sustainability.
-
Selected companies profiled in our full study include recognized global and regional manufacturers spanning both heritage and innovation-centered approaches. Each profile assesses product portfolios, manufacturing footprint, channel strength, and strategic responses to raw material and regulatory pressures.
Recent developments that materially change strategic choices
-
Product-level sustainability launches: Market participants are introducing recycled-content monofilament options targeted at sustainability-motivated buyers. These moves influence procurement decisions, retailer assortment, and brand positioning.
-
Policy and supply implications: Broader regulatory activity around chemical reporting and product restrictions has increased the cost and complexity of market entry for suppliers relying on legacy formulations. Separately, federal regulatory adjustments affecting biofuel feedstocks and related supply chains can indirectly influence availability and pricing of alternative feedstock routes.
What the full PW Consulting report contains (practical, actionable elements)
-
Transparent methodology and model: Detailed market model (historical and forecast), scenario variants, input assumptions, and sensitivity analyses that allow clients to re-run projections under alternate pricing, demand, and regulatory scenarios.
-
Regulatory heatmap and compliance playbook: Jurisdiction-level regulatory tracking, compliance cost estimates, and prioritized remediation actions for product reformulation and labeling.
-
Supply chain and procurement advisory: Raw material exposure matrices, supplier risk scoring, and recommended hedging and dual-sourcing strategies to protect margins through commodity cycles.
-
Commercial and go-to-market playbooks: Channel segmentation guidance, SKU rationalization frameworks, price architecture options, and promotional tactics tuned for specialty retailers and e-commerce partners.
-
M&A and partnerships pipeline: Identification of strategic targets and partnership archetypes (technology providers, recyclers, regional consolidators) with preliminary valuation and integration risk indicators.
-
Vendor benchmarking: Comparative profiles of incumbent and emergent manufacturers, focusing on product breadth, innovation capability, cost position, and strategic initiatives — including early movers on recycled-content products and PFAS-free formulations.
Strategic imperatives for executives in 2026
-
Prioritize compliance-forward R&D: Initiate or accelerate reformulation projects and third-party testing to ensure market access in regulated states and to pre-empt broader regulatory moves.
-
Hedge input exposure: Implement or refine resin-price hedging strategies and diversify procurement to reduce single-supplier or single-region dependency.
-
Move from pilot to scale on sustainability: Validate cost, quality, and supply chain for recycled-content lines and prepare a two-speed launch plan — premium early-adopter SKUs coupled with a ramp plan for mainstream offerings.
-
Reassess channel economics: Rebalance investments across direct-to-consumer, specialty retail, and distributor channels according to margin profile, growth potential, and control over consumer data.
-
Active portfolio management: Use SKU pruning, targeted innovation, and selective M&A to consolidate scale where it matters and invest in differentiated technology or materials where price competition is intense.
How PW Consulting’s output supports 2026 decision-making
-
Scenario-ready analytics: Our Excel-native market model enables commercial and finance teams to stress-test budgets and investment cases against plausible market and cost scenarios for 2026–2032.
-
Actionable playbooks: Short, medium, and long-term roadmaps align R&D, procurement, regulatory, and commercial functions around prioritized interventions tied to ROI milestones.
-
Deal support: We provide target screens and preliminary valuation heuristics for M&A or partnership ventures focused on capability acquisition (e.g., recycling tech, specialty coatings, testing labs).
Conclusion — what to do next in 2026: Companies should move beyond monitoring to active repositioning. The combination of cost volatility, regulatory tightening, and shifting retail incentives makes 2026 a year for decisive action: secure raw-material resilience, commit to compliance-minded product portfolios, and mobilize investments in sustainability where they create defensible differentiation.
To access the complete market model, regional and application breakdowns, segmented demand tables, and detailed company dossiers (including supplier scorecards and SKU-level recommendations), please visit the PW Consulting report page and download the full Monofilament Fishing Line Market study. The full package contains the granular data and executable tools needed to translate the insights in this briefing into board-level decisions and operational plans for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Monofilament Fishing Line Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com