

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Specialty Paper Market Set to Expand at 5.1% CAGR Through 2032

Specialty Paper Market — Strategic Preview for 2026 Decisions
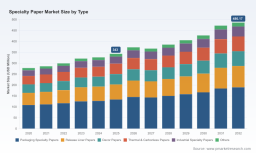
PW Consulting’s Specialty Paper Market Specialty Paper Market — Specialty Paper Market Specialty Paper Market Specialty Paper Market Specialty Paper Market Specialty Paper Market Specialty Paper Market (Specialty Paper Market) provides a focused, decision-grade preview for corporate leaders planning capital allocation, M&A, pricing and supply-chain moves in 2026. Built on a 2020–2025 historical base and using 2025 as the reference year, our model estimates the global specialty paper market at approximately USD 343 Million in 2025 and projects a compound annual growth rate (CAGR) of 5.1% over the 2026–2032 forecast window, taking the market to around USD 486 Million by 2032. This paper is a strategic “trailer”: it surfaces the analytical framework, high-conviction implications and action levers executives need now, while reserving detailed subsegment, regional and account-level datasets for the full report.
Specialty Paper Market
Why this study matters for 2026
-
A turning point in industry economics: The market’s mid-single-digit CAGR masks material reallocation within the value chain. Growth continues, but profit pools are migrating toward barrier-coated, flexible-packaging and technical grades where fiber innovation and coating technologies create premium pricing power.
Specialty Paper Market -
Cost and policy shocks are reshaping tactics: Recent pulp-price inflation and targeted environmental policies have shifted producer economics and sourcing strategies. These shocks are already triggering price adjustments, mill closures and capacity realignments that will influence margin trajectories through 2026 and beyond.
Specialty Paper Market -
Consolidation and strategic capacity moves: Market concentration metrics indicate a partially fragmented industry — sufficient scale among leading players to drive consolidation, while regional and product niches remain contested. Strategic acquirers are already expanding technical-grade capacity and reassigning legacy assets to higher-value lines.
-
Regulatory and sustainability demand: Food-safety barriers, recyclability mandates and corporate ESG targets are accelerating adoption of fiber-based barrier solutions. Companies that align product roadmaps and supply chains with emerging regulations will capture disproportionate share gains.
What the full Specialty Paper Market report delivers (operational map)
-
Market architecture and validated sizing: Comprehensive top-line model (USD Million), historical performance (2020–2025) and scenario-driven forecasts (2026–2032) with sensitivity to raw material and price cycles.
-
Demand-side segmentation framework: Demand drivers by application cluster, end-user purchasing behavior, and channel economics—structured to support commercial playbooks and pricing strategies.
-
Supply-side maps: Mill-level capacity overlays, recent commissioning and decommissioning events, and a supplier scorecard covering technology stack, sustainability credentials, and unit-cost proxies.
-
Competitive benchmarking: Strategic profiles and capability matrices for leading and challenger producers, with actionable implications for partnerships, procurement sourcing and M&A prioritization.
-
Playbooks and toolkits: Pricing levers, hedging checklists, capex prioritization templates, and go-to-market tactics for premiumization and product conversion.
-
M&A heatmaps and valuation ranges: Targets by strategic fit, integration risk, and near-term synergies—plus a practical due-diligence checklist that highlights hidden liabilities in fiber sourcing and environmental compliance.
Competitive landscape — strategic profiles and near-term signals
-
Large diversified players: Global cellulose and packaging incumbents retain distribution reach and balance-sheet strength. Recent portfolio moves show a deliberate shift toward higher-margin specialty lines and selective plant rationalization to remove low-return capacity.
-
Specialty-focused manufacturers: Firms with premium packaging, coating or technical-paper expertise are investing in barrier technologies and service-led propositions to capture end-user switching value.
-
Regional challengers and nimble consolidators: Companies executing bolt-on acquisitions and opportunistic mill purchases are expanding technical capacity and addressing short-term demand imbalances.
-
What to watch (recent, high-conviction developments): A flurry of strategic activity in early-to-mid 2026 underscores the themes above: targeted acquisitions to expand technical capacity; tactical price increases in response to pulp-cost inflation; and new barrier-coated product introductions to address food-packaging demand and regulatory shifts. These moves indicate active re-pricing of the market and accelerating product innovation cycles.
Key industry signals incorporated
-
Pulp-cost pressure: A documented hike in pulp prices has translated into across-the-board cost pressure and supplier price actions. Organizations must embed raw-material sensitivity in pricing and procurement contracts to preserve margins.
-
Policy and competitive intensity in China: Capacity trends and policy-driven expansions in China are exerting competitive pressure on export flows and regional pricing. China’s dominant share of capacity is a structural factor that must be part of any sourcing or market-entry assumption.
-
Selective capacity rationalization in mature markets: Strategic closures and technology upgrades among established producers are compressing lower-value output, tightening near-term availability for certain grades while reallocating upstream capacity to higher-value products.
Actionable implications for 2026 corporate decision-makers
-
For producers: Reprioritize capital into specialty grades that combine technological differentiation (coatings, barrier performance) with favorable regulatory alignment. Use modular capex and contract manufacturing to accelerate time-to-market while limiting balance-sheet risk.
-
For procurers and brand owners: Rework long-term contracts to include indexed pricing clauses and multi-sourcing strategies that mitigate volatility from pulp-price cycles and regional capacity swings. Demand more transparency on upstream fiber sourcing and compliance to de-risk supply continuity.
-
For private equity and strategic acquirers: Target bolt-on assets that deliver immediate technical capabilities and customer relationships rather than greenfield mills. The concentration profile creates room for value creation through integration and channel consolidation.
-
For R&D and sustainability officers: Accelerate validation and commercialization of fiber-based barrier solutions and recyclable coatings—these are the highest-return technology bets given regulatory trajectories and end-user demand for circular packaging.
Risk scenarios and trigger points (how to stress-test your 2026 plan)
-
Baseline (our modelling): Continuation of the 5.1% CAGR with structural reallocation toward premium grades—outcomes driven by steady regulatory alignment and moderated raw-material inflation.
-
Downside: Elevated pulp-price spikes combined with trade restrictions reduce margins and compress demand for discretionary specialty grades; the appropriate defensive moves include temporary throughput realignment, renegotiated supplier terms and short-term price passes to customers.
-
Upside: Accelerated adoption of fiber-based barriers and faster-than-expected premiumization drive above-model growth in target segments; strategic actions include capacity acceleration, selective M&A and premium-contract locking with blue-chip customers.
Competitive snapshots — examples of strategic moves to benchmark
-
Acquisition-driven capacity expansion: Several firms have recently expanded specialty capacity through targeted asset purchases and mill acquisitions to secure technical-grade output and shorten product development cycles.
-
Price and product responses to input shocks: Selected producers have announced price adjustments to mitigate pulp-cost inflation, while others are launching upgraded barrier-coated grades to defend margin and market share.
-
Operational rationalization in mature geographies: Strategic closures and line conversions are being used to concentrate investment in differentiated products and improve unit economics.
How to use this preview and where the full intelligence adds value
-
This preview surfaces the strategic imperatives and the near-term moves that will matter in 2026. The full Specialty Paper Market report contains the granular tools executives need to execute: detailed segment and regional revenue breakdowns, mill-by-mill capacity maps, customer-level demand models, supplier scorecards, an M&A target list with pro forma synergy estimates, and downloadable financial models (USD Million basis) that allow you to run custom scenarios.
-
We intentionally withhold the detailed subsegment and regional line-item numbers here to preserve the report’s commercial value. If your team is prioritizing capex, procurement renegotiation, premiumization roadmaps or an acquisition sprint in 2026, the full dataset and playbooks will materially shorten your decision cycle and reduce execution risk.
PW Consulting’s Specialty Paper Market preview is designed to move decisions from debate to action. The market is growing at a predictable clip, but the distribution of value is changing quickly — favoring companies that combine product differentiation, disciplined procurement and targeted M&A. For executives drafting 2026 plans, the fundamental question is not whether the market will grow, but which parts of the value chain will capture the growth. Our full report provides the maps, models and playbooks to answer that question with confidence.
For detailed analysis of this topic, please visit the official page: Specialty Paper Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com