

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Hemodialysis Concentrates Market to Reach USD 3,560M by 2032 at 6.2% CAGR

Hemodialysis Concentrates Market — Strategic Outlook for 2026 Decision‑Makers
As PW Consulting’s lead industry analyst, I present a high‑level strategic primer intended to orient executives, investors, and procurement leaders ahead of 2026. This piece distills the practical implications from our full Hemodialysis Concentrates Market study: it demonstrates the rigor and framing we apply while deliberately withholding the granular segment tables and proprietary breakouts that drive tactical decisions. Consider this a trailer — enough detail to validate the methodology and strategic direction, but not the replaceable data payload. To act on detailed segment economics, client teams will need the full report and supporting models.
Hemodialysis Concentrates Market
Market snapshot — where we stand and where we’re headed
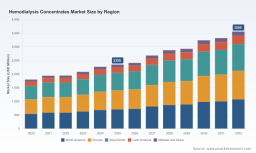
The hemodialysis concentrates market has shown steady expansion over the past half decade, rising from USD 1,800 million in 2020 to approximately USD 2,350 million in the base year 2025. Our forecast model, underpinned by historical demand patterns, pricing dynamics, and expected adoption trends, projects a compound annual growth rate (CAGR) of roughly 6.2% across the 2026–2032 horizon, with the market approaching just over USD 3,560 million by 2032 under the base scenario.
Hemodialysis Concentrates Market
Those headline numbers mask structurally important characteristics: the market remains concentrated, with the top three players controlling the majority of commercial volumes and the top five capturing nearly eighty percent of the marketplace. This concentration creates both barriers and levers for new entrants and incumbents — a duality that shapes every strategic choice covered in the full study.
Hemodialysis Concentrates Market
Why this study matters for 2026 corporate decisions
- Procurement and sourcing optimisation: With raw material costs and supply‑chain configuration continuing to drive margin volatility, procurement teams must rethink supplier segmentation, dual‑sourcing thresholds, and buffer inventory policies. Our models translate demand variability into recommended safety stocks and cost‑to‑serve trade‑offs tailored for regional manufacturing footprints.
- Portfolio and product strategy: The rise of single‑use bicarbonate cartridges and digital integration across dialysis ecosystems is changing product lifecycle economics. The report quantifies adoption tipping points and recommends where to prioritize investment in cartridge platforms versus premixed solutions.
- M&A and partnership screening: Given market concentration and the strategic value of in‑house production, M&A remains a fast route to secure capacity and proprietary formulations. We provide a transaction playbook that aligns target profiles with integration risk tolerances and synergies — essential for 2026 deal sourcing.
- Regulatory risk management: Recent Class 2 recalls have amplified the business impact of manufacturing controls and post‑market surveillance. The study maps regulatory event scenarios to financial and operational outcomes so organizations can size remediation programs and insurance strategies.
- Commercial go‑to‑market decisions: Home dialysis growth and clinic consolidation require different commercial models. The research prescribes channel strategies, pricing architectures, and clinical evidence investments to win in each segment.
What the full report contains — practical, executable deliverables
- Transparent market sizing and forecast methodology (base year 2025; historical series 2020–2025; forecast 2026–2032) with downloadable model files you can re‑run under alternative assumptions.
- Scenario matrix covering baseline, downside (manufacturing disruption/regulatory tightening), and upside (accelerated home care adoption/technology substitution) paths with P&L and cash‑flow implications by scenario.
- Supplier and capability scorecards: manufacturing footprint, quality systems maturity, SKU portfolios, and integration readiness to support vendor selection or outsourcing decisions.
- Commercial playbooks: channel and pricing decision trees, tender win probability levers, and sample RFP templates aligned to concentrate format (liquid, dry, cartridge) and customer type (clinic, home care).
- Regulatory and compliance roadmap: probable enforcement actions, monitoring expectations, and a remediation cost estimator tied to class‑level recall scenarios.
- M&A diligence checklist and 50+ target characteristics filtered by strategic rationale (capacity, geography, technology, or customer access).
- Executive dashboards and slide templates designed for board briefings, investor updates, and procurement committees.
Competitive landscape — synthesis and strategic reads
The competitive set combines global dialysis system integrators, specialized concentrate manufacturers, and regional producers. Notable players we evaluate (company HQ and public information cited in the full study) include:
- Fresenius Medical Care (Bad Homburg, Germany; https://freseniusmedicalcare.com) — a vertically integrated incumbent that couples concentrate production with machine fleets and service contracts. Fresenius’s digital moves (including a unified platform launched in mid‑2025) indicate a strategy to monetize systems + consumables integration and to lock in long‑term service revenues.
- B. Braun Melsungen (Melsungen, Germany; https://www.bbraun.com) — leverages premixed concentrate compatibility within broader dialysis systems and positions concentrates as part of an end‑to‑end clinical solution. Their strength is system integration and direct channel relationships with institutional purchasers.
- Nipro Corporation (Osaka, Japan; https://www.nipro-group.com) — focuses on machine‑compatible concentrates and benefits from strong OEM relationships across Asia. Their technical competence in formulation and packaging is a distinct advantage in tailored contracts.
- Rockwell Medical (Wixom, Michigan, USA; https://www.rockwellmed.com) — has accelerated product innovation with single‑use bicarbonate cartridges added to the portfolio in early 2025 and maintains active presence at major clinical conferences. This product focus targets ease‑of‑use and infection‑control narratives.
- Renacon Pharma Limited (Karachi, Pakistan; https://renaconpharma.com) — a long‑standing regional manufacturer with cost position advantages and niche product expertise in citrate‑based concentrates.
- Farmasol (Kayseri, Turkey; https://farmasol.com.tr) — recently became part of Pollet Medical Group in early 2025, an acquisition that strengthens in‑house acid concentrate capacity and regional supply resilience.
- Pollet Medical Group (Belgium; https://polletmedicalgroup.com) — beyond being an operator, Pollet now amplifies its role as a producer and systems supplier for concentrates, increasing competition in manufacturing capability and process equipment sales.
Strategic takeaways: incumbents with integrated systems can extract higher lifetime value from customers, while focused innovators and regional producers compete on unit economics, speed to local market, and specialized formulations. Recent product launches and M&A moves underscore a bifurcating market: consolidation among system houses and targeted sourcing strategies among clinical buyers seeking supply resilience.
Regulatory, reimbursement and supply dynamics shaping near‑term risk
- Regulatory events: The period 2024–2025 saw multiple FDA Class 2 recall actions tied to premixed and concentrate products; the regulatory climate now prioritizes perimeter seal integrity, labeling, and manufacturing controls. These events materially increase the cost of quality and raise the floor for entry.
- Reimbursement variability: Reimbursement rules for the preparation of dialysate vary across jurisdictions; standard procedural codes exist in major markets, but the margins available to suppliers and service providers depend on local payment models and scope of clinic budget ownership.
- Material and manufacturing costs: Purified water systems, electrolytes, acids, and packaging infrastructure drive production economics. Fluctuations in upstream supply‑chain infrastructure and energy costs can quickly alter unit economics, particularly for dry versus premixed formats.
How to use these insights in 2026 — an actionable playbook
- Run three immediate stress tests: (1) single‑supplier disruption for a key concentrate SKU; (2) a Class 2 recall requiring a 30‑day market withdrawal; (3) 10–20% raw material cost inflation. The report’s model workbook contains plug‑and‑play scenarios ready for C‑suite review.
- Prioritize pilot projects for digital integration with systems suppliers. Where possible, negotiate commercial pilots that tie software adoption to preferential concentrate pricing and co‑funded clinical evidence generation.
- Revisit supplier contracts with new SLAs for quality event response and holdbacks. Embed audit rights and pre‑defined corrective action plans to reduce remediation latency following regulatory events.
- For corporate development: focus on targets that provide manufacturing redundancy, unique proprietary formulations, or rapid access to high‑growth home dialysis channels. The report’s target filter helps size accretion and integration complexity.
- Align commercialization with clinical economics: build value propositions that reduce total cost of care (e.g., reduced hospitalizations, simplified home set‑up) rather than unit price alone.
Closing note — what this preview does (and doesn’t) give you
This preview demonstrates the analytical frame, practical outputs, and strategic prescriptions that PW Consulting applies to the hemodialysis concentrates sector. It includes headline market sizing, growth trajectory, competitive context, and regulatory risk framing — sufficient for boards and strategy teams to validate our approach. What it intentionally omits are the granular subsegment revenue tables, regional and application breakouts, and the raw model files that operational teams need to run procurement RFPs, calibrate M&A bids, or set volume‑based pricing by market. Those assets are available in the full Hemodialysis Concentrates Market report and the accompanying Excel workbooks.
Contact PW Consulting to request the full study, model access, and a tailored executive briefing that converts these strategic insights into a 90‑day operational plan for 2026.
For detailed analysis of this topic, please visit the official page: Hemodialysis Concentrates Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com