

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Stainless Steel Floor Drains Market at USD 1,656M in 2025, 3.6% CAGR Forecast

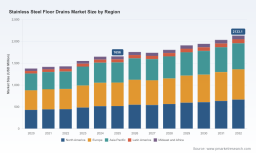
Stainless Steel Floor Drains Market — Strategic Outlook for 2026 Decision‑Making
As companies plan capital allocation, product roadmaps, and M&A activity for 2026, the stainless steel floor drains market presents a mix of steady demand, regulatory-driven premiumization, and margin pressure from raw material dynamics. Our PW Consulting analysis uses a 2025 base year and a historical window (2020–2025) to produce a detailed forecast for 2026–2032. At the aggregate level, the market stood at approximately USD 1,656 million in 2025 and is modeled to reach roughly USD 2,133 million by 2032, reflecting a compound annual growth rate (CAGR) near 3.6%. This trajectory frames 2026 as an inflection year for product investments, sourcing strategies, and sector consolidation.
Stainless Steel Floor Drains Market
Why this study matters for enterprise leaders in 2026
- Tangible sizing to inform capital decisions: The forecast and scenario work in this study translate macro trend lines into capex-scheduling guidance — enabling manufacturers and specification-driven distributors to align capacity investments with realistic demand curves.
- Procurement and raw‑material exposure: Stainless steel input prices remain a dominant earnings driver. Our analysis incorporates real‑world ranges for common alloys (for example, 304-grade stainless demonstrated meaningful price bandwidth in 2025), and ties that volatility to margin modelling and contract strategies.
- Regulatory and hygienic premium: Increasing regulatory scrutiny and hygiene standards in foodservice, pharmaceuticals, and municipal works are raising the technical bar for drains. Compliance and hygienic design now influence specification choices and create opportunity for differentiated, higher‑margin products.
- Fragmentation creates tactical options: With a market structure that remains relatively fragmented, 2026 is an attractive year for selective bolt‑on M&A, geographic footprint expansion, or strategic partnerships that secure specification channels.
- Infrastructure‑led demand pockets: Public and institutional refurbishment funded through infrastructure programs is creating near‑term project pipelines — companies that can position as trusted suppliers early in design can capture outsized share.
What the PW Consulting report delivers (practical, operational outputs)
- Granular market sizing and an empirically validated forecast model for 2026–2032, with scenario toggles for high/low raw material and regulatory outcomes.
- Segmented demand drivers by product type, application vertical, and region — presented with interactive dashboards and downloadable models (note: this executive overview intentionally omits the detailed segment tables; full segmentation is available in the report package).
- Price‑sensitivity and input‑cost stress tests that translate stainless steel price movements into EBITDA and break‑even thresholds for typical product families.
- Regulatory and standards matrix (NSF/ANSI, ASME, HACCP, EHEDG and related regional requirements) mapped to product development checklists and validation pathways.
- Competitive benchmarking and capability mapping of key suppliers, including product breadth, fabrication vs. cast capabilities, and go‑to‑market channels.
- Commercial playbooks — specification influence strategies for manufacturers, procurement negotiation templates for buyers, and contractor engagement models for distributors.
- M&A playbook and valuation sensitivities tuned to the market’s commercial dynamics and the earnings impact of steel price shocks.
- Case studies and project references illustrating best practices for hygienic installations, retrofit approaches, and cost efficient logistics for heavy stainless components.
High‑level competitive landscape and what it means strategically
The competitive map includes legacy manufacturers with broad portfolios, regional specialists focused on custom systems, and firms targeting hygienic or industrial niches. Market leadership is not concentrated — the leading companies account for a minority of total sales, leaving room for nimble specialists and integrated players to expand through targeted moves.
Stainless Steel Floor Drains Market
- Josam Company (Elkhart, Indiana) — Offers both fabricated and cast stainless solutions (304/316L) with strong traction in hygienic commercial and industrial applications. Recent project references (notably brewery and winery installations) demonstrate success in specification‑led, high‑value projects. Strategic implication: Josam’s product breadth and project track record position it well to win lifecycle spec work where hygienic design and retrofit capability are required.
- AWI Manufacturing (Montgomery, Alabama) — Decades of experience in food and dairy applications give AWI a durable specification advantage in sectors where hygienic performance is non‑negotiable. Strategic implication: Their deep vertical focus is a barrier to entry for generic players but also makes AWI an attractive partner or takeover target for companies seeking to enter the food‑service channel.
- Jay R. Smith Mfg. Co. (Montgomery, Alabama) — A broad commercial drainage portfolio with a reputation in sanitary drains and specialty products. Strategic implication: Strong channel relationships with commercial contractors mean early involvement in design stage projects — a key competitive moat.
- Zurn Industries (Saginaw, Michigan) — A high‑grade product line augmented in 2025 with expanded hygienic drainage solutions targeting pharmaceutical and food processing. Strategic implication: Zurn’s recent push underscores premiumization in the market and highlights the growing value of compliance‑certified, hygienic product variants.
- Blücher / Watts Water Technologies (Denmark / U.S.) — Global reach with standardized stainless drainage systems and channel presence in multiple regions. Strategic implication: Global players can exploit scale in specification, while local fabrication partners often win retrofit and custom channel work.
- CustomDrains (U.S.) — Focused on bespoke stainless systems for food processing and pharmaceutical facilities; agility and customization are core strengths. Strategic implication: Custom specialists can command premium pricing on engineered projects and are natural partners for system integrators.
- Sioux Chief Manufacturing — Balanced residential and commercial product set. Strategic implication: Companies that straddle both channels can smooth demand cyclicality but must manage product mix to avoid commoditization.
Market dynamics and risk map
- Input volatility: Nickel and stainless alloy price swings materially affect margins. Procurement strategies and long‑lead hedges are essential.
- Regulatory compliance and specification escalation: Foodservice, pharmaceutical, and municipal standards (including NSF/ANSI and ASME measures, and hygienic guidelines such as HACCP and EHEDG) are driving demand for premium, certifiable designs.
- Infrastructure funding: Public investment in wastewater and public facility upgrades creates project pipelines, but these are procurement‑driven and price‑sensitive.
- Fragmented supply base: Regional manufacturers and custom fabricators create localized competition and make national roll‑outs dependent on partner networks.
- Technology and product evolution: Innovations in seals, trap designs, and smart monitoring are emerging as differentiators; product roadmaps should prioritize modularity and serviceability.
- Sustainability and circularity: Recycled content and end‑of‑life recovery are becoming procurement criteria for institutional buyers.
Strategic playbook — recommended actions for 2026
- Procurement resilience: Implement a two‑track sourcing model — long‑term formula contracts for base alloys combined with a tactical spot pool to capture downward price moves. Model the earnings impact of 5–20% raw material swings on product families.
- Product prioritization: Invest selectively in hygienic, certifiable variants (e.g., 316L offerings and validated trap systems) to capture higher margins in food, pharma, and institutional channels.
- Specification strategy: Build an early‑engagement program for architects and MEP contractors, offering spec packs, BIM families, and on‑site demo units to lock in choice during the design phase.
- M&A and partnerships: Pursue bolt‑ons that add fabrication capacity, hygienic certifications, or geographic access — prioritize targets that close specification gaps or shorten lead times.
- Operational productivity: Standardize platform components to reduce SKU complexity and improve sourcing leverage without sacrificing customization where it commands premium pricing.
- Commercial channels: Strengthen distributor relationships for retrofit and quick‑turn projects while deploying direct sales teams for large institutional and industrial bids.
- Regulatory readiness: Invest in testing and certification capabilities to shorten time‑to‑market for premium products and reduce reliance on third‑party labs.
- Data and digital: Use the report’s downloadable models to run internal scenarios; layer product‑level telemetry (where applicable) to support lifecycle selling and service contracts.
Final perspective — where to focus in 2026
With aggregate growth modest but stable (a mid‑single digit CAGR across 2026–2032), 2026 becomes a year to sharpen competitive advantage rather than to pursue broad, capital‑intensive expansion. Success will favor firms that combine disciplined procurement, certified hygienic offerings, and early design influence. Fragmentation leaves room for value‑creating consolidation — particularly in niches where specification and hygienic performance drive purchasing decisions.
Stainless Steel Floor Drains Market
This executive overview sketches the strategic contours. For operational leaders ready to translate these insights into action, the full PW Consulting Stainless Steel Floor Drains Market report includes the complete segmentation tables, region and application dashboards, raw material sensitivity spreadsheets, competitor scorecards, and an M&A valuation toolkit. Access to those deliverables is available on our report page — where you will also find downloadable models and a companion implementation checklist tailored to 2026 priorities.
For detailed analysis of this topic, please visit the official page: Stainless Steel Floor Drains Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com