

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Waste Paper Recycling Market to Reach USD 74,300M by 2032 at 5.0% CAGR

Waste Paper Recycling Market 2026: Strategic Preview for Executive Decision‑Making
Executive summary
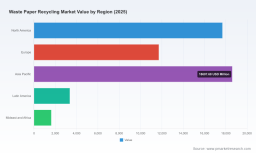
As lead analysts at PW Consulting, we present a strategic preview of our full Waste Paper Recycling Market study (base year 2025). The sector sits at the intersection of regulatory pressure, circular-economy ambition and heavy industrial capital allocation: our modeling shows the global market expanding from roughly USD 41.5 billion in 2020 to USD 53.0 billion in 2025, and we forecast further growth to approximately USD 74.3 billion by 2032. The compound annual growth rate for the forecast window (2026–2032) is 5.0%.
Waste Paper Recycling Market
This briefing explains why these macro dynamics matter for corporate strategy in 2026, outlines the practical decision tools contained in the full report, and synthesizes competitive and technology dynamics you must factor into capital planning, sourcing, and M&A. By design this note highlights the actionable themes while omitting the granular regional and application splits that are included in the purchasable report—our “trailer” approach to demonstrate value while directing you to the full data package for execution.
Waste Paper Recycling Market
Why 2026 is an inflection year
Three converging forces make 2026 a critical planning year for operators and investors in waste paper recycling:
Waste Paper Recycling Market
- Operational leverage: plants commissioned in 2023–25 move from ramp‑up to steady state, creating near‑term capacity and throughput visibility that changes feedstock demand dynamics.
- Price and input volatility: recovered fiber pricing experienced upward pressure in early 2026, reflecting stronger demand for recycled fiber and tighter availability—this feeds directly into margin sensitivity for processors and papermakers.
- Policy and procurement shifts: extended producer responsibility and recycled‑content mandates across multiple jurisdictions are driving corporate procurement requirements, accelerating demand for certified recycled pulp and differentiated product streams.
For executives, these represent both risks (feedstock cost shocks, regulatory compliance costs) and strategic openings (premium for certified supply, first‑mover advantages in high‑quality recycling capacity).
Market shape and concentration: what the headline numbers hide
The sector exhibits a medium concentration profile: the top three suppliers account for a meaningful but not dominant share of the market, and the top five widen that dominance modestly. Practically, this means:
- There is sufficient scale among leaders to influence technology and standards, while significant niche and regional players continue to serve differentiated customer segments.
- New entrants can find avenues for growth through specialization—service models, dry pulping, deinking innovations, or integrated logistics—without immediately challenging incumbent scale.
Our full report unpacks the competitive map at plant‑level granularity; this preview focuses on the strategic implications for 2026 decision cycles.
Competitive and technology landscape — strategic takeaways
We evaluated suppliers across equipment types and delivery models—from single‑machine vendors to turnkey line providers—and synthesized implications for procurement and partnership strategies.
- Precision shredding and pre‑processing: European engineering firms specializing in single‑shaft and industrial shredders have sharpened offerings to handle corrugated and OCC streams with lower energy intensity and higher throughput consistency. Their tech reduces downstream sorting and pulping costs but requires careful integration engineering at the plant level.
- Turnkey recycled‑fibre lines: A subset of suppliers delivers complete pulping, cleaning and deinking lines at scale. These vendors shorten time‑to‑production and shift project risk to the OEM—at a price. For large processors or greenfield entrants, the turnkey route accelerates commercial ramp and reduces systems integration burden, making it attractive for capacity expansions tied to offtake agreements.
- Baling and logistics equipment: Solutions that compress and tie OCC and corrugated streams remain critical to cost economics. Automated, high‑density balers reduce handling costs and transportation emissions—key levers for procurement teams working to meet sustainability KPIs.
- Dry pulping and process innovation: Emerging dry‑pulping approaches promise energy efficiency and reduced wastewater profiles. Adoption remains selective—driven by feedstock composition and regulatory constraints on effluent management.
Selected vendor archetypes we analyzed include mechanical pre‑processors (specialist shredders), complete line vendors (turnkey pulpers and deinking systems), and baling/logistics equipment suppliers. Each archetype implies a different procurement playbook and total cost of ownership profile.
Company snapshots and strategic posture (high level)
- WEIMA (Germany): strong in single‑shaft shredders and modular pre‑processing; ideal for operators seeking flexible throughput modules to optimize upstream capture and reduce transport costs.
- Parason Engineering (India): turnkey capability spanning pulpers to deinking; attractive for large‑scale retrofit or greenfield projects where rapid commissioning and output quality are priorities.
- American Baler Company and Maren Engineering (USA): focus on balers and compaction systems—critical for logistics optimization and cost containment in material handling chains.
- BHS‑Sonthofen (Germany): expertise in shredders and pre/post‑shredding systems that integrate with recycling lines to improve feedstock homogeneity.
- SOYU (China): proponents of energy‑efficient dry pulping lines targeting operators prioritizing CAPEX‑lite and water‑constrained footprints.
- Rexon Hydraulics (India): automated balers and recycling machines tailored for high throughput OCC and cardboard operations in distribution and retail consolidation points.
These profiles are part of a broader vendor evaluation framework contained in the full study, including technology readiness, O&M intensity, retrofit compatibility, and supply‑chain resilience scoring.
What the full report provides — practical, executable content
PW Consulting’s full study is structured for transaction and operational use. Key deliverables include:
- Market model (2020–2032): downloadable, dynamic Excel model with historical series and forward scenarios by region, type and application, plus sensitivity levers for recovered fiber pricing, capex schedules and throughput assumptions.
- Procurement and vendor selection toolkit: configurable RFP templates, vendor scorecards, and total cost of ownership calculators for equipment and turnkey suppliers.
- Operational playbooks: CAPEX/OPEX benchmarking, plant sizing heuristics, integration checklists, and commissioning roadmaps to reduce execution risk and shorten payback timelines.
- Regulatory and certification matrix: mapping of relevant recycled‑content mandates, labeling requirements and permitting timelines in key markets—critical for contract timing and compliance budgeting.
- M&A and partnership screening: candidate prioritization criteria, synergies checklist, and a pipeline of potential bolt‑on targets by capability (e.g., deinking tech, logistics consolidation, specialty fiber upgrades).
- Vendor deep dives: comparative analyses of equipment providers, solution architects and service partners, including case studies of recent plant builds and retrofit projects.
These practical modules are built to plug into capital planning cycles in 2026 and to inform strategic choices such as entering new geographies, locking in long‑term fiber supply, or selecting a technology partner for capacity expansion.
Risk, sensitivity and scenario implications
Our scenario work highlights three high‑impact variables for 2026 decisions:
- Recovered fiber price volatility — a primary driver of short‑term margin swings for processors and papermakers.
- Feedstock quality mix shifts — higher contamination rates increase processing costs and influence equipment selection.
- Policy and procurement changes — recycled content mandates can create structured demand but also require certification and traceability investments.
For each variable, the full report provides break‑even curves, hedging and contracting strategies, and staged investment options to preserve optionality in an uncertain pricing and regulatory environment.
Recent market signals to monitor in 2026
- Recovered paper prices for OCC rose in March 2026, a signal of tightening feedstock availability relative to rising demand for recycled fiber—important evidence when stress‑testing margins.
- Industry engagement remains strong: for example, firms such as ReBAT confirmed exhibition participation at major trade events in mid‑2026, illustrating continued interest in showcasing process and logistics innovations in recycling machinery.
Implications for corporate strategy and recommended next moves
Executives should treat 2026 planning as a balance between committing to capacity and preserving flexibility. Recommended actions include:
- Run a rapid TCO comparison for turnkey vs modular builds using our vendor scorecards; in many cases, turnkey reduces integration risk but at a premium that must be justified by secured offtake.
- Secure diversified feedstock contracts with volume‑and‑quality clauses to mitigate OCC price spikes and contamination risk; consider strategic partnerships with large waste generators and retailers.
- Accelerate investments in downstream traceability and certification if your customers or regulators are moving toward recycled‑content requirements.
- Evaluate M&A targets focused on deinking, dry pulping, or logistics consolidation to buy capability and shorten time‑to‑market for premium recycled pulp products.
Closing — how PW Consulting can accelerate your 2026 program
This preview demonstrates the strategic lenses and practical tools executives need to act in 2026. The full Waste Paper Recycling Market report contains the confidential segmentation tables, regional and application breakout data, plant‑level economics, and downloadable models required to finalize capital and commercial decisions. We have intentionally withheld the granular splits in this public note to preserve the integrity of the full analysis and to ensure decision makers access the complete evidence base before committing capital.
Contact PW Consulting to arrange access to the complete report, the interactive market model, and a tailored workshop to translate these insights into a 90‑day action plan for your organization.
For detailed analysis of this topic, please visit the official page: Waste Paper Recycling Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com