

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
SAXS Market Eyes USD 170M in 2025 with 6.8% CAGR (2026–2032) — PW Consulting

Small Angle X-ray Scattering (SAXS) Market: Strategic Preview for 2026 Decision-Makers
As organizations calibrate R&D investments, capital equipment purchases, and strategic partnerships for 2026, the Small Angle X-ray Scattering (SAXS) market presents a distinct mix of steady growth, concentrated supplier strength, and accelerating application breadth. This preview—prepared by PW Consulting’s industry analysis team—summarizes the high‑level market trajectory, competitive positioning, regulatory contours, and the immediate strategic implications that senior leaders should weigh before committing budget or launching new initiatives. It deliberately demonstrates analytical depth while withholding detailed segment tables and granular splits to reserve premium insights for the full report.
Small Angle X-ray Scattering (SAXS) Market
Market snapshot: trajectory and scale
Between 2020 and our base year of 2025 the SAXS market showed resilient expansion, rising from approximately USD 110 million in 2020 to roughly USD 170 million in 2025. Our forecast for the 2026–2032 window projects a compound annual growth rate (CAGR) of 6.8%, bringing the market to an estimated USD 266 million by 2032 under the central scenario. This pace reflects a combination of continued academic demand, increasing industrial adoption—particularly in semiconductor and advanced materials—and more accessible laboratory-grade instrumentation and software stacks.
Small Angle X-ray Scattering (SAXS) Market
Two headline dynamics underpin this growth: (1) instrument replacement and laboratory modernization cycles in well‑funded research institutions and industrial metrology labs; and (2) expanding applied use cases—ranging from bio‑SAXS in structural biology to TSAXS (tilted‑angle SAXS) and GISAXS in semiconductor and surface nanostructure metrology—where SAXS moves from niche characterization toward embedded process control.
Small Angle X-ray Scattering (SAXS) Market
Why this matters for 2026 corporate decisions
- Capital procurement timing: Vendors are refreshing portfolios with higher‑throughput detectors, integrated temperature and environmental control stages, and software that shortens time‑to‑insight. Procurement teams should incorporate total cost of ownership horizons (5–7 years) rather than sticker price alone to capture upgrade paths and software licensing models.
- R&D prioritization and platform bets: For R&D portfolio managers, SAXS capabilities now enable faster materials screening and quality control loops. Decisions to internalize SAXS versus outsourcing should be informed by throughput needs, sample types (liquid, gel, thin film), and the availability of validated workflows for your application class.
- Make‑vs‑buy for software and analytics: The market is maturing beyond raw hardware: value migrates to instrument‑agnostic data platforms and AI‑assisted analysis pipelines. Firms should budget for software integrations, structured data management, and validation against reference materials and standards.
- Regulatory and standards compliance: Adoption in regulated industries (pharmaceuticals, food) requires alignment with standards such as ISO 17867 and traceable intensity calibration (e.g., NIST SRM materials). Compliance planning must begin at procurement to avoid downstream revalidation and costly retrofits.
Report scope: what the full PW Consulting study delivers
Our full market research package is designed as an operational playbook for executives and technical leaders. Key deliverables include:
- Market sizing and validated forecasts (2020–2032) with scenario sensitivity and upside/downside drivers.
- Adoption curves by application class, with use‑case narratives that translate instrument capabilities into R&D and production KPIs.
- Technology deep dives on laboratory SAXS, GISAXS, TSAXS, and ultra‑SAXS modalities—covering detector architectures, source technologies, and sample environment trends.
- Buyers’ guidance: procurement templates, vendor comparison checklists, and TCO models that reflect service, calibration, and software lifecycle costs.
- Partnering and M&A scorecards that identify likely acquisition targets and strategic fit by capability and geography.
- Regulatory and standards roadmap, with action items for quality, traceability, and validation in regulated sectors.
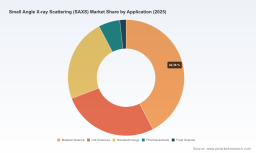
Note: To preserve the report’s commercial value for subscribers, this preview intentionally omits detailed regional, product, and application split tables. The full dataset—useful for budgeting and competitive analysis—is available via our subscription portal.
Competitive landscape — what to watch in 2026
The SAXS supplier ecosystem is characterized by a handful of strong global players complemented by specialists that address niche laboratory and industrial needs. Market concentration is meaningful: the top three and top five suppliers command a sizable share of industry revenues, indicating that vendor selection decisions have material consequences for service, upgradeability, and ecosystem access.
-
Anton Paar GmbH (Graz, Austria)
Anton Paar’s SAXSpoint series positions the firm strongly in modular laboratory systems with features such as advanced detectors, temperature‑controlled stages, and GISAXS capability. Their active engagement in academic conferences and hands‑on workshops signals a customer‑education approach that reduces adoption friction for complex experiments.
-
Bruker Corporation (Billerica, MA, USA)
Bruker’s D8 ADVANCE platform and DIFFRAC.SAXS software emphasize integrated hardware‑software ecosystems for both 1D and 2D analysis. Bruker’s product strategy focuses on end‑to‑end workflows and enterprise licensing models—appealing to labs seeking consolidated vendor relationships and validated analytics.
-
Malvern Panalytical Ltd (Malvern, UK)
Malvern Panalytical’s Empyrean Nano edition is built for multipurpose scattering (USAXS, SAXS, bio‑SAXS, WAXS, PDF) on a single goniometer system. This multi‑mode approach reduces footprint and supports labs needing a flexible platform for cross‑disciplinary projects.
-
Rigaku Corporation (Akishima, Tokyo, Japan)
Rigaku is concentrating on industrial metrology, notably TSAXS instruments for semiconductor 3D metrology and critical‑dimension analyses. Their recent technical notes and application pieces underscore a go‑to‑market approach aimed at manufacturing process engineers.
-
Xenocs SAS (Grenoble, France)
Xenocs’ Xeuss family and analytics software target high‑performance lab systems and bio applications. Integrated software offerings and detector performance improvements are central to their value proposition for research labs that require high sensitivity and throughput.
-
Shimadzu Corporation (Kyoto, Japan)
Shimadzu provides SAXS solutions oriented to materials science and nanotechnology. Their strength lies in established service networks, particularly in Asian markets, and in instruments that balance industrial robustness with research flexibility.
-
Hecus X-ray Systems GmbH (Austria)
Hecus specializes in compact laboratory SAXS systems, addressing customers who require benchtop solutions and simpler deployment models. Their niche positioning is attractive for early adopters and small to mid‑sized research facilities.
Recent vendor signals (implications for buyers)
- Anton Paar’s 2026 conference and workshops demonstrate vendor investment in user enablement; buyers should expect accelerated training offerings bundled with new instrument purchases.
- Rigaku’s technical notes on TSAXS highlight a vendor push into semiconductor metrology—an important signal for manufacturing customers evaluating precision metrology vendors.
- Malvern Panalytical’s webinars and product introductions confirm an emphasis on converged scattering platforms, which can reduce the need for multiple specialized instruments.
Standards, calibration, and regulatory dynamics
Standards and calibration references are central to SAXS adoption in regulated contexts. ISO 17867 provides standardized methods for particle sizing in the 1–100 nm range; NIST SRM materials (e.g., glassy carbon) remain the benchmark for absolute intensity calibration. Meanwhile, instrument and software vendors are closing the usability gap by providing validated workflows and automated reporting—reducing the burden of in‑house method validation.
For regulated product teams (pharma, food, advanced materials), early alignment on calibration standards and audit‑ready documentation should be a gating criterion for any procurement decision.
Strategic recommendations for 2026
- Adopt a capability tiering approach: Classify use cases into exploratory research, regulated QC, and inline process control. Match instrument class and service level to the tier to avoid overinvestment.
- Prioritize open analytics and data portability: Require interoperable data formats and exportable analysis pipelines in procurement contracts to avoid vendor lock‑in for mission‑critical workflows.
- Design an instrument lifecycle and calibration plan: Build multi‑year budgets that include calibration reference materials, service visits, and software upgrades to protect measurement traceability.
- Evaluate partnerships with specialist providers: For organizations with limited SAXS expertise, consider strategic alliances with academic centers or contract labs as a bridge while developing internal capabilities.
- Incentivize cross‑functional pilots: Run 6–12 month pilot projects that pair materials R&D, process engineering, and data science to validate value capture before capital deployment.
Actionable next steps
- Commission a tailored TCO and ROI study tied to your key use cases—our full report contains a customizable financial model.
- Request vendor demonstrations emphasizing your sample types and throughput—insist on hands‑on workshops that reproduce target experiments.
- Map regulatory and calibration obligations to procurement terms to ensure audit readiness from day one.
- Engage PW Consulting for a short workshop to translate the market forecast into a 24‑month procurement and competency roadmap.
Closing note: this preview demonstrates the analytical framework and strategic levers that matter for SAXS decisions in 2026. To preserve the integrity of our benchmarking and to provide clients with actionable allocation‑level intelligence, we have withheld detailed segment and regional tables in this public summary. Access the full PW Consulting SAXS Market report for comprehensive datasets, vendor scorecards, and the spreadsheet models necessary to execute procurement and investment decisions with confidence.
For detailed analysis of this topic, please visit the official page: Small Angle X-ray Scattering (SAXS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com