

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Thyristors Market Poised for Growth at 4.1% CAGR Through 2032

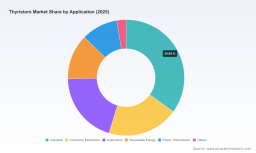
Thyristors Market 2026: Strategic Signals for Decision-Makers
As global electrification accelerates, thyristors remain a foundational but often underappreciated building block of high‑power conversion and control. PW Consulting’s latest Thyristors Market study (base year 2025; historical window 2020–2025; forecast 2026–2032) synthesizes market sizing, competitive positioning, supply‑chain dynamics and technology trajectories into an operational playbook tailored for executives making capital, sourcing and product decisions in 2026. Our forecast period shows the market growing at a steady compound annual growth rate (CAGR) of 4.1% through 2032, rising from USD 1,461.0 Million in 2025 to roughly USD 1,936.5 Million by 2032. This trajectory masks important inflection points and supplier dynamics that will determine winners and laggards over the next 18 months.
Thyristors Market
Why this study matters for 2026 decision cycles
-
Visibility into near‑term supply risk: lead times, wafer cost inflation and concentrated supply power are already shaping procurement risk and should influence 2026 sourcing strategies.
Thyristors Market -
Investment timing for capacity and R&D: modest but persistent market growth combined with episodic upstream cost shocks creates selective opportunities for reshoring, JV stakes and targeted M&A.
Thyristors Market -
Product roadmaps and differentiation: shifts in module architectures, Si/SiC coexistence and integration into power sub‑systems require product roadmaps to prioritize manufacturability and serviceability now, not later.
High‑level market trajectory and concentration
From USD 1,182.5 Million in 2020 to USD 1,461.0 Million in 2025, the historical series in our study demonstrates resilient demand across power conversion, traction and industrial segments. The forecast shows continued expansion to approximately USD 1,936.5 Million by 2032 at a 4.1% CAGR (2026–2032). While growth is steady rather than explosive, market concentration is material: the top three suppliers account for roughly two‑thirds of market share, and the top five approach four‑fifths. For buyers and investors, this concentration creates leverage for supplier strategy but also elevates systemic risk if one of the major suppliers alters capacity or pricing.
Competitive landscape: who sets the pace
The thyristor ecosystem blends long‑cycle, capital‑intensive manufacturers with diversified semiconductor houses and specialized module integrators. Our competitive analysis profiles the market’s incumbents and strategic challengers, mapping capabilities, go‑to‑market channels and vertical focus areas:
-
Hitachi Energy — brings a broad high‑power portfolio and deep systems expertise for grids, traction and large renewables projects. Their strength is product breadth and system integration, making them a partner of choice for large utilities and industrial OEMs.
-
Dynex Semiconductor — differentiated by in‑house device manufacture and a focus on high‑current, disc‑type thyristors used in pulsed power and heavy industrial applications. Their low thermal resistance designs are a technical advantage where thermal management is decisive.
-
Powerex Inc — recognized for mission‑critical modules serving aerospace, defense and space markets. Recent direct funding agreements to expand domestic production capacity signal geopolitically driven demand for localized supply chains.
-
Littelfuse — competes strongly in discrete SCR and TRIAC markets for motor controls, lighting and industrial controls, leveraging distribution channels and application engineering services.
-
Infineon, STMicroelectronics, Renesas — large semiconductor houses that position thyristors alongside power conversion and SiC roadmaps. Their scale allows bundling devices into modules and design ecosystems attractive to high‑volume OEMs.
-
Central Semiconductor, Semikron Danfoss — niche and module specialists that bridge discrete device supply and system‑level integration, often favored by renewable and alternative energy integrators.
Collectively, these players illustrate two critical strategic tensions: specialization versus integration, and global scale versus regional resilience. Our report benchmarks each company on manufacturing footprint, product breadth, channel strength and roadmap maturity to help clients construct supplier scorecards and identify partnership or acquisition targets.
Supply‑chain and raw‑materials dynamics that will shape 2026 outcomes
-
Lead times: discrete component lead times held steady or rose modestly, reaching around 26 weeks in mid‑2025. For high‑power buyers planning system deliveries in 2026, this window is the starting point for inventory and contractual strategy.
-
Wafer availability and cost: silicon wafer shipments grew in 2025 and are forecast to remain supportive for device manufacturers, but advanced‑node wafer pricing pressures in early 2026—driven by the cost of next‑generation nodes—raise upstream input costs and complicate margin planning for silicon‑based thyristors.
-
Policy and industrial incentives: public funding for domestic capacity (e.g., recent government support for Powerex in mid‑2026) is creating pockets of accelerated investment and should be considered when evaluating regional manufacturing strategies and supplier selection.
Technology and application vectors
Key technological trends in our study include continued coexistence of Si and SiC device strategies, module integration (thermal and control ICs), and system‑level features such as fault detection and easy field replacement. Applications continue to diversify: traditional industrial and transmission roles remain important while electrified transport, large‑scale renewables interfaces and utility‑grade converters are increasing device complexity and reliability requirements. For R&D and product teams, this combination means investing in robust qualification regimes, modular architectures and closer co‑engineering with OEMs.
Strategic implications by stakeholder
-
OEMs and system integrators: Lock in supplier capacity with multi‑year purchase agreements, invest in second‑source development, and prioritize designs that enable late customization to mitigate lead‑time exposure.
-
Component manufacturers: Evaluate targeted capacity expansion versus strategic partnerships; prioritize cost‑to‑serve reductions and modularized SKUs that lower qualification overhead for large accounts.
-
Private equity and strategic acquirers: The market’s concentration and steady growth profile create attractive roll‑up opportunities—especially for niche module specialists and regional manufacturers with strong customer lock‑in.
-
Procurement leaders: Recalibrate TCO models to include wafer cost volatility and extended lead‑times; implement dynamic hedging for long‑lead raw materials where feasible.
From insight to action: 90/180/360 day playbook
-
0–90 days: Conduct a supplier stress‑test (lead‑time, capacity, single‑sourcing), prioritize critical SKUs for second‑source identification, and secure at‑risk inventory for key programs.
-
90–180 days: Negotiate conditional capacity commitments with preferred suppliers tied to escalators for raw‑material costs; initiate co‑development agreements for modularized offerings that reduce qualification cycles.
-
180–360 days: Execute selective investment—either greenfield or through minority stakes—in manufacturing nodes supported by local incentives; implement product families designed for interchangeability and serviceability.
What’s inside the PW Consulting Thyristors Market report
The report is designed as a decision‑ready toolkit for 2026. Highlights include:
-
Time‑series market sizing (2020–2025) and an actionable forecast (2026–2032) with scenario variants that stress test demand sensitivity to lead times and wafer pricing.
-
Competitive benchmarking and supplier scorecards covering product breadth, manufacturing footprint, vertical focus and partnership appetite.
-
Supply‑chain mapping and vulnerability heat maps (lead time, raw materials and geopolitical exposure).
-
Technology roadmaps and patent landscaping that identify white spaces and potential disruptive entrants.
-
Commercial playbooks: pricing scenarios, buyer negotiation levers, and channel strategies for both high‑power and discrete markets.
-
M&A and investment targets: shortlists based on strategic fit and integration risk, with valuation sensitivities under different wafer‑price and lead‑time regimes.
-
Primary‑research appendices: executive interviews, plant tours and supplier questionnaires that underpin our qualitative judgments.
How to use the study without losing competitive advantage
The report is deliberately constructed to provide the strategic depth required for boardroom decisions while preserving commercially sensitive granularity that is best consumed in full. Our “trailer” approach gives executives what they need to frame strategy—market size trajectory, concentration metrics, supplier risk signals and prescriptive actions—while directing them to the full dataset and modeling assets for transactional work, supplier selection or M&A diligence. If your team needs the models, sensitivity analyses or the supplier scorecards for RFPs and bid evaluation, those are accessible in the complete PW Consulting deliverable.
Final strategic note
By 2026, thyristor market participants will be judged less on product roadmaps alone and more on the resilience of their go‑to‑market systems—procurement flexibility, manufacturing optionality and the ability to bundle device offerings into higher‑value system contracts. The market’s moderate growth and high concentration create a nuanced environment: enough demand to justify selective investment, but sufficiently concentrated supply that single‑source or geopolitical shocks can ripple through programs. Firms that act now—securing flexible supply, accelerating modular product architectures and actively evaluating regional capacity options—will be best positioned to capture the upside embedded in the 2026–2032 outlook.
For access to the full datasets, scenario models and supplier scorecards—necessary for RFPs, capital allocation and M&A execution—please consult the complete PW Consulting Thyristors Market study.
For detailed analysis of this topic, please visit the official page: Thyristors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com