

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Gantry/Cartesian Robots Market to hit $5.9B by 2032; 9.4% CAGR from $3.15B (2025)

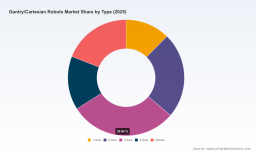
Gantry/Cartesian Robots Market — Strategic Preview for 2026 Decision-Making
As industrial automation budgets reallocate to support reshoring, high-throughput micro-assembly and novel additive-manufacturing use cases, Gantry/Cartesian robots have moved from niche utility to strategic infrastructure. PW Consulting’s latest market study (base year: 2025; historical window: 2020–2025; forecast: 2026–2032; currency: USD, revenue unit: Billion) quantifies that transition and models the practical choices procurement, product and corporate development teams must make in 2026. The segment has grown robustly over the last half-decade and is projected to expand at a compounded annual growth rate (CAGR) of 9.4% through 2032 — a trajectory that materially alters capital planning, supply chains and competitive dynamics for system suppliers and end users alike.
Gantry/Cartesian Robots Market
Why this report matters to 2026 strategies
- Capex and portfolio timing: With the market entering a sustained growth phase, firms that time platform launches or capacity expansions in 2026–2027 can capture disproportionate share if they align product features to emerging demand (precision, throughput, and energy efficiency).
- Supply-chain resilience: Raw-material volatility and component lead times are a top-three margin lever. Tactical sourcing and dual-sourcing strategies developed in 2026 will determine gross-margin trajectories for the next five years.
- M&A and alliances: Fragmentation in the space creates attractive roll-up opportunities for system integrators and component specialists seeking scale or adjacent capabilities.
- Regulatory & safety compliance: Updated ISO/ANSI requirements and region-specific constraints mean product roadmaps must bake in compliance testing and risk-assessment services up front.
- Service and software monetization: With hardware commoditizing in many standard applications, service, software and AI-enabled handling/gripper capabilities are the most defensible margin pools.
Report deliverables — what you’ll be able to use immediately
- Granular total-addressable-market (TAM) and forecast model (2020–2032), with scenario-based outputs to stress-test capex and revenue plans under differing adoption curves and macro assumptions.
- Methodology annex that outlines our demand drivers, price erosion curves, and installed-base replacement cycles — enabling your finance team to re-run forecasts with your corporate assumptions.
- Practical go-to-market playbooks for OEMs, system integrators and distributors, including channel economics, lead-time reduction tactics, and service-contract templates.
- Supplier-cost model that incorporates raw-material sensitivity (steel and rare-earth magnet price swings) and quantifies margin impact under multiple procurement strategies.
- Regulatory impact assessment that maps recent ISO/ANSI updates and North American heavy-industry safety constraints to product development roadmaps and field-deployment costs.
- Vendor heatmaps and strategic scorecards (technical capabilities, speed-to-delivery, service footprint, vertical-focus) — presented at a level sufficient to inform RFP shortlists while preserving paywalled score granularity.
- Case studies and field benchmarks (including heavy-load construction printing and high-precision semiconductor pick-and-place) that illustrate installation, commissioning, and OPEX realities.
Market shape and concentration — strategic implications
The market exhibits low overall concentration: the top three and top five suppliers together account for roughly one quarter of market revenue (CR3 ≈ 24.6%; CR5 ≈ 26.2%). This fragmentation signals two simultaneous dynamics. First, there is room for specialized vendors to capture strong, defensible positions in subsegments (e.g., heavy-load gantries, ultra-precise XYZ modules, or low-cost tabletop systems). Second, system integrators and component suppliers can build scale advantage through geographic expansion, platform standardization, or targeted M&A.
Gantry/Cartesian Robots Market
For buyers, fragmentation means vendor selection must emphasize integration capability, aftermarket support and total cost of ownership, not just unit price. For investors and corporate development teams, the math favors roll-ups of high-service local integrators and verticalized OEMs that can consolidate recurring revenue and shorten lead times.
Gantry/Cartesian Robots Market
Competitive landscape — what to watch in 2026
- igus (Germany): Their maintenance-free plastic linear systems (drylin) are strategically positioned for low-cost, low-maintenance pick-and-place and palletizing. Expect continued traction where TCO and rapid deployment trump absolute precision.
- Yamaha Motor (Japan): High-performance XY-X Cartesian platforms remain a benchmark for factory automation. The October 2025 JV to form TY ROBOTICS (production transition starting January 2026) is a deliberate move to shorten lead times and broaden the product lineup — a challenge to competitors on speed-to-market and local-service expectations.
- Festo (Germany): Offers ready-to-install Cartesian modules and 3D gantries; their May 2026 GripperAI launch signals how AI-enabled end-effectors are becoming modular, reducing brand lock-in for gripper hardware while increasing software value capture.
- IAI Automation (Japan): Compact multi-axis Cartesian solutions and parallel kinematics make them a strong candidate for compact assembly cells and medical-device automation.
- Güdel Group (Switzerland): Their FP-5 and gantryRobot lines target heavy-load precision. Recent case studies demonstrating 3D concrete printing highlight non-traditional verticals where gantry systems can unlock new revenue pools.
- Dunkermotoren (Germany) and Physik Instrumente (PI) USA: Focused on linear-motor speed/precision and air-bearing accuracy respectively — enabling high-speed packaging and semiconductor/3D-printing use cases.
- Janome, Nordson EFD, Promation (Japan/USA): Represent the low-to-mid cost and niche application players (standard handling, adhesive dispensing, tabletop assembly) who defend margin through specialization and local service.
- Trade-show and ecosystem signals: Activity such as Rollon’s presence at key automation shows indicates continued demand for modular linear-motion components and emphasizes the importance of distribution and partner channels.
Key market dynamics and risks to factor into 2026 plans
- Raw-material volatility: Steel and rare-earth magnet prices have fluctuated in the high single-to-double digits year-on-year since 2022, compressing gross margins on standard-grade gantry components. Our modeling shows this dynamic can shave 2–4 percentage points off gross margins absent mitigating procurement tactics.
- Regulatory tightening: Updated safety standards in 2025 require comprehensive risk assessments for collaborative and heavy-load cells. Compliance adds development and field-validation costs that must be accounted for in product pricing and service contracts.
- Energy-efficiency pressures: Buyers increasingly demand low-consumption solutions for continuous heavy-duty operations. Energy-efficient motorization and recuperation features will be differentiators in tender evaluations.
- Demand concentration shifts: Growth is being driven by a mix of established industrial automation (packaging, semiconductor, automotive) and nascent applications (large-format 3D printing, on-site construction). Each vertical imposes distinct proof-of-concept and certification timelines.
Recommended actions for 2026 — practical, prioritized
- Re-baseline your supply-cost model: Integrate raw-material scenarios and negotiate multi-year hedges or fixed-price contracts for critical components.
- Invest in modularity and software: Prioritize platform architectures that accommodate multiple end-effectors and embed telemetry to monetize predictive maintenance.
- Pursue targeted partnerships: Consider JVs or manufacturing alliances in regions with long lead times — the Yamaha TY ROBOTICS example underscores the value of production proximity.
- Differentiate around service: Build installation and safety-compliance advisory bundles to reduce buyer switching costs and accelerate deployment timelines.
- Evaluate M&A selectively: Target local system integrators or specialized OEMs that deliver recurring service revenue or unique vertical capabilities (heavy-load, ultra-precision, or AI-enabled handling).
- Embed compliance and energy targets early: Make updated ISO/ANSI safety and energy-efficiency a non-negotiable part of the product-definition phase to avoid retrofit costs later.
How PW Consulting supports your 2026 execution
Our report combines market forecasts, supplier scorecards, executable go-to-market playbooks and a sensitivity-tested financial model that your strategy or finance team can adopt or re-run with internal assumptions. We surface tactical supplier-negotiation scripts, OEM bundling examples and an M&A screening tool calibrated for valuation multiples in fragmented automation niches.
This preview is intended to establish the strategic contours you need now. For the full segment-level breakdowns, regional and application-specific forecasts, vendor score matrices with quantified metrics, and downloadable financial models that support board-room decisions, consult the complete Gantry/Cartesian Robots Market report. The full dataset and appendices contain the detailed inputs and outputs you will need to finalize 2026 budgets and M&A pipelines.
For detailed analysis of this topic, please visit the official page: Gantry/Cartesian Robots Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com