

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Dental Intraoral X‑ray Sensors Market to Reach USD 473 Million by 2032 at 8.59% CAGR

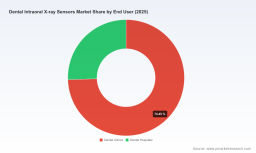
Dental Intraoral X‑ray Sensors Market: Strategic Preview for 2026 Decision‑Makers
Executive teaser
The dental intraoral X‑ray sensor market has matured from an emergent digital niche into a mainstream clinical and commercial platform. Our latest PW Consulting study, built on 2020–2025 historical performance and a 2026–2032 forecast horizon, shows the market expanding at a mid‑single‑digit to high‑single‑digit compound annual growth rate (CAGR). From an industry size that rose materially during the 2020–2025 base period, the market is projected to continue growing through 2032 under the combined influence of device substitution, software‑enabled diagnostic uplift, and reimbursement and regulatory tailwinds. This preview outlines why the 2026 inflection point matters and what pragmatic steps executives should be considering now.
Dental Intraoral X-ray Sensors Market
Why this study matters for 2026 corporate decision cycles
- Timing of product and software investment: 2026 is the year many OEMs and channel partners must decide whether to accelerate wireless and AI investments or prioritize cost and compatibility with legacy practice IT. Strategic capital allocation now will determine competitive positioning for the next product cycle.
- Regulatory and reimbursement clarity: Dental intraoral sensors operate in an increasingly defined regulatory frame—FDA 510(k) pathways remain the standard for market access and ISO biocompatibility requirements apply to components in direct oral contact. Concurrently, reimbursement coding commonly used in dental radiographic services creates quantifiable offsets to acquisition costs for clinics that can capture them. Understanding the interplay of these levers is essential to commercial planning.
- Consolidation and concentration: The competitive landscape is consolidated: a small set of global vendors account for a meaningful share of market value, while a broader long tail competes on price, features and channel relationships. This concentration creates both defensive and acquisitive opportunities for companies looking to scale quickly.
- Clinical value and sell‑through: Digital sensors reduce patient X‑ray exposure in optimized workflows and enable efficiencies in chair time and diagnosis. The clinical ROI calculus — acquisition cost, maintenance, software subscriptions, and billing capture — is now quantifiable and a gating factor for procurement decisions in dental groups and hospital systems.
What the full PW Consulting report delivers (practical, decision‑grade content)
- Proprietary market size and forecast model (2020–2032) in editable Excel, including high‑granularity scenario toggles for adoption rates, price erosion, and software monetization to stress‑test investment cases.
- Methodology appendix detailing data sources, triangulation logic, and sensitivity assumptions so finance teams can reproduce and audit outputs for internal approval processes.
- Commercial playbooks for OEMs, distributors and large clinic groups: pricing levers, service bundles, channel economics and margin waterfall templates.
- Regulatory and reimbursement matrix with go/no‑go checklists for 510(k) filings, ISO compliance, and payer engagement strategies to maximize billing capture where codes are available.
- Vendor scorecards and strategic heatmaps that synthesize product capability (hardware resolution, wireless architectures, software integration), customer support footprint, intellectual property posture, and partnership openness.
- Supply‑chain resilience assessment with alternate sourcing strategies for key components, and a procurement playbook for fleet upgrades that minimizes clinical disruption.
- M&A and inorganic growth framework: screening criteria, valuation levers, and integration risk checklists targeted to strategic and financial buyers active in medical/dental imaging.
- Clinical adoption tools including buyer personas, clinical value calculators that quantify exposure and time savings, and templates for pilot programs in multi‑location dental groups.
Competitive landscape—strategic read on leading players
The market is characterized by a blend of large dental OEMs with integrated imaging portfolios and specialized sensor suppliers focused on niche differentiation (resolution, form factor, wireless connectivity) and channel partnerships. Top vendors have pursued different routes to competitive advantage:
Dental Intraoral X-ray Sensors Market
- Dentsply Sirona (Charlotte, NC): A major incumbent with sensor product lines emphasizing high line‑pair resolution and broad channel access, leveraging its wider consumables and equipment relationships to drive installed base upgrades.
- DEXIS / Dental Imaging Technologies (Quakertown, PA): A software‑hardware integrator that has been aggressive on clinical workflow and imaging platform capabilities. Recent platform updates to expand AI‑assisted 2D pathology detection and improved wireless workflows underscore the importance of software as a differentiation vector.
- Planmeca (Helsinki): Known for high image quality and patient‑centered design, Planmeca's sensor portfolio is positioned to win in premium clinic segments where ergonomics and software integration matter.
- Vatech (Hwaseong, South Korea): A supplier combining high‑resolution sensor hardware with cost‑competitive manufacturing, well‑placed to serve both channel partners and export markets.
- Carestream Dental (Atlanta): An integrated imaging player offering sensor hardware as part of broader digital dentistry solutions—strength is in bundled sales to mid‑sized chains and hospitals.
- Owandy Radiology (France): Focused on iterative hardware improvements—third‑generation sensors emphasize speed and reliability aimed at clinic workflows demanding uptime and rapid image acquisition.
- Freedom Technologies Group (US), Acteon (France), Qpix Solutions (US), XpectVision (China): These companies represent important vectors: wireless direct‑conversion designs, strong clinical brand names in diagnostic tools, recent regulatory clearances, and geographically diversified production respectively. Smaller vendors frequently compete on specialization (e.g., zero‑profile sensors or Bluetooth connectivity).
Recent notable moves include platform and product launches extending AI diagnostic features and wireless freedom, and regulatory clearances enabling broader addressable markets. These are emblematic of a market where hardware improvements are necessary but no longer sufficient—software and regulatory access increasingly determine commercial success.
Dental Intraoral X-ray Sensors Market
Market dynamics and external forces to monitor in 2026
- Regulation: FDA 510(k) compliance remains the baseline for U.S. market access; adherence to medical biocompatibility standards is non‑negotiable for intraoral devices.
- Reimbursement and clinical coding: Established billing codes used in dental radiographic services materially influence ROI calculations for clinics and dental chains; capturing those reimbursements reduces payback periods on fleet upgrades.
- Clinical safety and efficacy: The quantifiable reduction in radiation exposure versus film creates a clear clinical value proposition for sensor adoption, particularly in practices focused on patient safety metrics and regulatory compliance.
- Technology convergence: The pairing of sensors with cloud platforms, practice management systems and AI reading aids is accelerating; vendors that offer an open, integrable stack will benefit from larger ecosystem plays and recurring software revenues.
- Consolidation pressure: With the top tier accounting for a material share of market value, there is ongoing pressure for mid‑tier players to consolidate or specialize to maintain margins and coverage.
Strategic implications: recommended moves for 2026
- For OEMs: Prioritize modular product architectures that allow incremental feature rollouts (sensor hardware + separate subscription‑grade AI). This reduces time‑to‑market and protects revenue as clinical evidence for AI tools matures.
- For distributors and channel partners: Negotiate bundled service agreements that include training, subscription software and tiered replacement programs to increase switching costs and lifetime customer value.
- For investors and M&A teams: Focus on targets that either fill software gaps (AI diagnosis, practice integration) or add unique hardware IP (wireless direct conversion or ultra‑low profile sensors) rather than low‑margin commoditized manufacturing plays.
- For large dental groups and hospitals: Use pilot programs to measure real productivity gains and reimbursement capture; the clinical ROI will be the primary lever to justify broader fleet upgrades.
- For product teams: Embed regulatory strategy into the roadmap from day one and document clinical safety and biocompatibility testing early to accelerate 510(k) timelines and reduce time‑to‑revenue.
How to use the PW Consulting study in your 2026 planning cycle
Leverage our editable forecast model to apply your unique assumptions—pricing scenarios, contract length, software ARPU and adoption curves—and run best/worst/base case outputs for board and investment committees. Use the vendor scorecards as an objective input into supplier selection, and deploy the regulation and reimbursement playbooks to shorten procurement cycles. The full report contains the granular segmentation, channel economics and price benchmarks that underpin these recommendations; this preview is intentionally selective to preserve the value of the complete analysis.
For executives evaluating capital allocation, partnerships, or acquisition targets in dental imaging, the decisions you make in 2026 will define competitive positioning for the rest of the decade. PW Consulting’s full Dental Intraoral X‑ray Sensors Market report provides the actionable models, deal frameworks, and regulatory compass to convert market momentum into durable advantage.
Next steps
Access the full report and interactive models through our research portal or contact PW Consulting to schedule a strategy briefing tailored to your specific company role (OEM, distributor, investor or large clinical buyer). Our engagement offering pairs the research with a bespoke workshop to translate market intelligence into a prioritized 12–24 month roadmap.
For detailed analysis of this topic, please visit the official page: Dental Intraoral X-ray Sensors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com