

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Copper Strips Market Set for 5.24% CAGR Through 2032

Copper Strips Market 2026: Strategic Preview for Decision-Makers
As PW Consulting’s lead industry analyst, I present a focused, executive-grade preview of our Copper Strips Market research — designed to orient corporate leaders, investors, and procurement strategists for the pivotal business year of 2026. This briefing outlines the macro trajectory, the operational and competitive dynamics reshaping the value chain, and the pragmatic levers companies can pull to preserve margin and capture share. It intentionally surfaces analytical depth while withholding granular segmentation tables and proprietary line-item forecasts — a deliberate “trailer” to the full study that protects the actionable intelligence reserved for subscribers.
Copper Strips Market
Why this study matters for 2026 decisions
-
Timing: 2026 is a deflection point. Our base-year is 2025, and the forecast window (2026–2032) captures the concentrated phase of electrification, semiconductor resilience, and climate-led infrastructure investment. Decisions made this year about capacity, alloy strategy, and procurement contracts will lock-in cost exposure and market access for the next business cycle.
Copper Strips Market -
Practical value: The study provides the playbooks executives need to operationalize strategy — from capex prioritization to product-mix optimization and hedging of feedstock price risk. It translates market dynamics into boardroom-ready options and trade-offs, not just raw data.
Copper Strips Market -
Risk calibration: With upstream volatility and policy interventions accelerating, the research frames scenario-based outcomes to help risk committees quantify downside and hedgeable exposures.
Market snapshot — scale, growth, concentration
Our market model traces copper strips revenue from the 2020 starting point through the 2025 base year and projects forward to 2032. On a consolidated basis (USD, revenue in Million), the market expanded from approximately 102.5 million in 2020 to roughly 126.6 million in 2025, and under our central scenario it reaches about 180.0 million by 2032. That trajectory corresponds to a compound annual growth rate (CAGR) of roughly 5.24% over the forecast period — reflective of steady demand growth from electrification, automotive wiring, and electrical equipment, tempered by cyclical headwinds in commodity pricing and midstream capacity constraints.
Market concentration is moderate: the three largest players account for roughly 35.2% of revenue, while the top five collectively represent about 52.1%. This structure creates a landscape where scale matters for margin management and where focused innovation or niche specialization can still deliver outsized returns for smaller incumbents and new entrants.
Key dynamics shaping 2026 strategy
-
Feedstock volatility and its asymmetric impact. Copper prices surged in recent quarters — with benchmark indicators crossing historically high levels in early 2026 — driven by intensive demand from electric vehicles, renewable installations, and broader electrification. These price movements materially affect procurement costs and the economics of semi-finished product manufacturing. Midstream margins have come under stress as smelter treatment and refining charges (TC/RCs) contracted even while commodity prices rose, compressing the value available to refiners and fabricators.
-
Trade policy and contract complexity. Tariff actions on semi-finished copper products and other trade measures introduced in recent policy cycles have altered delivered-cost math and arbitrage opportunities. These regulatory moves changed global sourcing patterns and accelerated localization conversations in customer segments sensitive to lead times and supply security.
-
Capacity shifts and technology-driven differentiation. Several large producers have announced capacity investments and new grades tailored to automotive and electronics performance requirements. These investments not only expand throughput but also raise product-portfolio complexity as manufacturers seek to embed thermal, mechanical, and conductivity advantages into multi-gauge and alloy designs.
Competitive landscape — who’s setting the reference points
The competitive map is characterized by a mix of global-scale metal producers and specialized rolled-product manufacturers. The full report contains supplier scorecards and capability matrices; below is a high-level orientation to principal market influencers included in our analysis.
-
Aurubis AG (Hamburg, Germany) — A leading non-ferrous producer and recycler whose rolled copper product portfolio includes copper strips. Aurubis’ integrated position across recycling and primary processing gives it flexibility in feedstock sourcing and a competitive advantage when scrap premiums and secondary material streams matter.
-
KME Germany GmbH & Co. KG (Osnabrück, Germany) — A specialist in rolled copper and copper-alloy semi-finished products. Recent capacity additions at Osnabrück aim to stabilize supply for industrial applications and tighten lead-time spreads for European customers.
-
Mitsubishi Materials Corporation (Tokyo, Japan) — Producer of wrought copper products, including oxygen-free and multi-gauge strips engineered for automotive and electronics performance. Their product innovation roadmap recently added a high-strength, high-heat-resistance oxygen-free grade designed to meet evolving thermal-management requirements.
-
Wieland-Werke AG (Ulm, Germany) — A focused supplier of semi-finished copper and copper-alloy rolled products with strategic investments aimed at expanding capacity in North America to capture near-market demand for electrical and automotive segments.
Recent notable developments — which we analyze for impact on supply, pricing, and competitive posture — include capacity expansions and new product launches across these firms. For example, multiple firms inaugurated refining capacity or ground new production facilities between 2025 and 2026, while others introduced high-performance strip grades optimized for thermal management and contact reliability in EV and electronics applications. Each development carries implications for regional availability, specification competition, and billet-to-strip margin dynamics.
What the full report delivers — practical, transaction-ready outputs
-
Granular, validated market sizing and growth scenarios (historical 2020–2025; forecast 2026–2032) with sensitivity runs that isolate the impact of upstream price shocks, tariff regimes, and EV adoption curves.
-
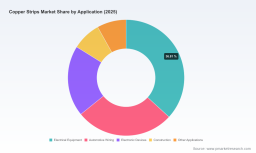
Segment-level demand drivers and an implications matrix for procurement, product-engineering, and sales strategy. (Note: detailed segmental tables and percentage breakdowns are intentionally withheld from this preview.)
-
Supplier benchmarking and an evidence-based scorecard assessing scale, technical capability, geographic reach, and product differentiation — enabling rapid shortlisting for partnership or M&A diligence.
-
Working capital and margin playbooks that translate commodity forecasts into hedging, inventory, and contract-design recommendations for 12-, 24-, and 36-month horizons.
-
Operational readiness checklists and a phased implementation roadmap for capacity expansions, alloy qualification programs, and repurposing lines for multi-gauge production.
-
Investment-case templates and scenario-modeled IRR/ payback sensitivities tailored to greenfield plants and brownfield upgrades.
Strategic implications and recommended actions for 2026
-
For producers: prioritize flexible production — invest in multi-gauge capabilities and modular finishing — to serve both high-performance automotive and electrical segments while managing feedstock swings. Reassess procurement tenors and incorporate indexation clauses to protect margins.
-
For OEMs and assemblers: deepen collaboration with strip suppliers to co-develop grades that reduce downstream processing steps (e.g., contact plating savings, reduced annealing cycles). Consider near-sourcing or strategic supplier partnerships to mitigate tariff and logistics risk.
-
For investors and private equity: target consolidation plays in regions where scale will create measurable cost advantages. Smaller, technology-focused players with patented alloys or production process advantages are attractive targets, particularly where product differentiation short-circuits commodity competition.
-
For traders and commodity desks: calibrate hedging strategies to account for compressed TC/RCs and potential policy shifts. Arbitrage windows have narrowed, so the premium is on logistical agility and contractual sophistication.
Scenario framing and uncertainties to monitor
Our scenarios span an upside (accelerated EV adoption and green infrastructure), a central-case (moderate growth with episodic commodity shocks), and a downside (prolonged macro slowdown and protectionist escalation). Key uncertainty levers include global copper availability, policy shifts on semis, and the pace of thermal-management innovation in electronics and EV powertrains. The full report quantifies each scenario’s impact on revenue, margin, and capacity utilization — enabling fully informed contingency planning.
How to use this analysis in your 2026 planning cycle
-
Start with a rapid diagnostic: map your revenue exposure to copper strips across customers and geographies, then align that mapping with the report’s scenario outcomes to assess upside and downside exposures.
-
Execute a three-month tactical plan to secure feedstock positions, refine contractual indexation terms, and prioritize capex projects with the highest optionality.
-
Embed a six- to twelve-month product qualification sprint with targeted customers to lock in design wins for emerging multi-gauge and high-heat-resistance grades — a proven path to premium pricing and stickier revenue.
To preserve the competitive edge of the full dataset and the supplier-level insights, we have withheld granular segmentation tables and certain proprietary submarket metrics from this preview. Access to the full Copper Strips Market report provides the detailed, transaction-ready intelligence needed to execute the recommendations above and to stress-test your operational plans under the exact scenarios we model.
For organizations committing to actionable 2026 strategies — whether through capex, M&A, supply-chain redesign, or product development — this study serves as the evidence base. Contact PW Consulting to obtain the complete report and the supporting data packages that translate these insights into executable plans.
For detailed analysis of this topic, please visit the official page: Copper Strips Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com