

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Cs Beam & Hydrogen Maser Clocks Market Poised for 6.98% CAGR to 2032

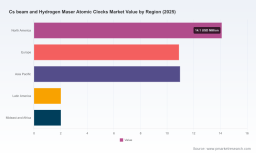
Cs Beam and Hydrogen Maser Atomic Clocks Market — Strategic Briefing for 2026 Decision-Makers
Executive snapshot
As organizations across telecommunications, defense, space, metrology, and critical infrastructure prioritize resilience against GNSS disruption and precision timing drift, the market for high-stability primary and secondary frequency standards is entering a sustained growth phase. Our analysis frames this market as a specialized, capital- and expertise-intensive ecosystem that expanded from a modest base in 2020 to an estimated USD 40.0 Million in 2025 and is projected to reach approximately USD 63.1 Million by 2032, representing a compound annual growth rate (CAGR) of roughly 6.98% across the forecast horizon. The market structure is moderately concentrated — the top three suppliers account for around 40% of revenue and the top five for roughly half — underscoring both the competitive moat enjoyed by incumbents and the room for focused challengers.
Cs beam and Hydrogen Maser Atomic Clocks Market
Why this matters for corporate strategy in 2026
-
Timing as a resilience asset: Precise and sovereign timing capabilities are becoming core to national-security and commercial continuity strategies. From data-center synchronization and telecom holdover to deep-space navigation and GNSS-independent PNT, atomic clocks represent strategic hardware that reduces systemic operational risk. Executives should treat timing platforms like other mission-critical infrastructure: plan lifecycle budgets, redundancy strategies, and scheduled refresh programs now, not later.
Cs beam and Hydrogen Maser Atomic Clocks Market -
Investment prioritization: A near-7% CAGR implies steady market expansion rather than speculative hypergrowth. This pattern favors disciplined capital allocation: scale manufacturing capacity where reproducible demand signals exist, invest selectively in R&D that narrows performance gaps (e.g., short-term stability vs holdover), and favor modular designs that allow aftermarket service, upgrades, and long tails of spare-part revenue.
Cs beam and Hydrogen Maser Atomic Clocks Market -
M&A and alliance optics: Moderate concentration and specialist know-how create attractive targets for horizontal consolidation and vertical integration. Buyers seeking rapid capability entry will find bolt-on acquisitions or strategic partnerships more efficient than greenfield development, particularly when the objective is to combine maser-level short-term performance with cesium-based long-term stability in a systems offering.
-
Supply chain and capacity risk management: The industry’s technical complexity and low-volume manufacturing profile mean single-source risk is real. Recent capacity moves by established vendors point to proactive scaling; market participants should validate supplier roadmaps, dual-source critical components, and secure long-lead items through multi-year contracts or strategic inventory buffers.
Market dynamics and technological inflection points
The sector sits at a junction of incremental innovation and application-driven adoption. Hydrogen masers offer unparalleled short-term stability, making them indispensable for timekeeping ensembles, deep-space telemetry, and national metrology applications. Caesium beam standards continue to provide robust long-term frequency references and increasingly come in optical cesium implementations that close the short-term gap versus masers at lower operating complexity and lifecycle cost.
Key technical enablers to watch in 2026 include: integration of ESTU (enhanced short-term stability units) into cesium platforms, packaging and thermal management advances that improve operational life in field conditions, and space-qualified architectures that emerged through recent mission deployments. Standards and primary reference upgrades at national metrology institutes also recalibrate buyer requirements: when a national standard is recertified or replaced, procurement cycles at labs, defense agencies, and large telecom operators often follow.
Competitive landscape — what differentiates today’s leaders
-
Microchip Technology Inc. — An established supplier with both cesium beam and active hydrogen maser offerings. Microchip’s portfolio spans metrology-grade devices and ruggedized systems for telecom and satellite ground segments. Recent capacity expansion in the U.S. underscores a strategic focus on reducing lead times and supporting sovereign timing strategies for national infrastructure customers.
-
Oscilloquartz SA — Positioned on the optical-cesium frontier, offering solutions that combine improved short-term stability with options targeted at telecom and defense markets. Product architectures that integrate ESTU-like modules enable competitive holdover performance without the full operational overhead of masers.
-
Safran Electronics & Defense — A leader in space-qualified masers and cesium systems, with demonstrable pedigree in missions that demand extreme stability. Its Space Hydrogen Maser program and deployments on high-profile space missions illustrate the company’s strength in high-assurance, mission-critical timing platforms.
-
Adtran Inc. — As a systems integrator and channel-focused supplier, Adtran’s recent launches emphasize cost-effective optical cesium primary references with long designed lifespans and improved holdover. Its go-to-market approach targets telecom modernization, data-center synchronization, and PNT resilience in infrastructure customers.
Tactical insight: competitive advantage in this market is less about one-off component innovation and more about system-level credibility — proven stability under operational conditions, lifecycle service offerings, spare-parts visibility, and demonstrated national or space mission endorsements.
Recent developments that recalibrate risk and opportunity
-
Capacity and industrialization: A significant manufacturing expansion by a leading maser supplier in 2026 signals that suppliers expect multi-year demand growth from infrastructure hardening programs and sovereign timing initiatives. Companies evaluating vendor selection should confirm execution risk and domestic sourcing constraints in their supply-chain due diligence.
-
Space and deep-space validation: Deployments of space-qualified masers and cesium ensembles in recent ESA-backed missions validate these technologies under the most demanding conditions. This reduces technology adoption risk for space and high-availability terrestrial systems and accelerates product roadmaps for space-hardened variants.
-
Standards recalibration: The certification of updated national primary standards and the visible calibration links between fountains and masers reshape procurement criteria for labs and regulators. Buyers must align procurement specs with the latest national metrology references to ensure interoperability and traceability.
-
Competitive product launches: Optical cesium introductions that offer maser-comparable short-term stability at lower lifecycle cost introduce a near-term substitution threat for certain low-to-medium risk deployments, changing the trade-off calculus for telecom and infrastructure buyers.
What our full report delivers (practical, actionable components)
-
Market sizing and scenario forecasts through 2032, including base, upside, and downside cases and sensitivity testing for major demand drivers. We provide modeled revenue curves and unit shipment estimates under alternative adoption pathways.
-
Quartered competitive benchmarking: technology scorecards, manufacturing footprint maps, margin-pressure analysis, and a supplier viability index calibrated for long-lead procurement environments.
-
Procurement playbook and total cost of ownership models: guidance for sourcing strategies, buy-versus-lease analysis, lifecycle maintenance planning, and spare-parts stocking algorithms tailored to different risk tolerances.
-
Regulatory and standards tracker: a concise digest of metrology certifications, space mission approvals, and standards updates that materially affect procurement specifications and time-to-deployment.
-
Use-case ROI calculations for major verticals (telecom, defense, space, metrology, critical infrastructure) that incorporate holdover needs, redundancy trade-offs, and failure-mode costs—delivering clear investment thresholds for board-level decision-making.
-
M&A and partnership targets: a curated list of integration opportunities and feasibility assessments for horizontal and vertical plays, informed by market concentration metrics and capability gaps.
Strategic recommendations for 2026 planning cycles
-
Institutional buyers (national labs, defense agencies): prioritize ensemble strategies that pair a maser for short-term stability with a cesium primary for long-term traceability. Lock multi-year service-level agreements with suppliers that demonstrate capacity expansion and mission provenance.
-
Telecom and cloud infrastructure operators: evaluate optical-cesium platforms with ESTU capability as a cost-effective hedge against GNSS outages. Pilot deployments in edge and core data centers will inform scalable rollouts and validate holdover profiles versus operational SLAs.
-
Vendors and new entrants: focus on modular subsystems and aftermarket services to build recurring revenue. Consider strategic partnerships with space and metrology institutions to accelerate credibility and shorten sales cycles.
-
Investors and corporate development teams: target bolt-on acquisitions that add either space-qualification competencies or domestic manufacturing capacity; valuation discipline should reflect the low-volume, high-technical-barrier nature of the market.
Closing — the strategic value of timely intelligence
For leaders making capital-allocation, procurement, or M&A decisions in 2026, the Cs beam and hydrogen maser atomic clocks market offers predictable expansion but demands specialist judgment. Our market projection to 2032 highlights a steady uptick in institutional and commercial demand — not a boom-and-bust cycle. That profile rewards early, disciplined moves: secure supply, validate performance claims under operational conditions, and structure deals that protect long-term access to critical spares and service capabilities.
This introduction intentionally surfaces the high-level market trajectory, competitive positioning, and tactical implications while withholding detailed subsegment tables and granular regional or application-level splits that are reserved for the complete report. To access the full dataset, downloadable models, and bespoke scenario analyses that underpin these strategic conclusions, please refer to the full Cs beam and Hydrogen Maser Atomic Clocks Market report on our website.
For detailed analysis of this topic, please visit the official page: Cs beam and Hydrogen Maser Atomic Clocks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com