

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Low-Voltage DC-DC LED Drivers to reach USD 458.6M by 2032, 6.2% CAGR — PW Consulting

Low-Voltage DC-DC LED Drivers: Strategic Imperatives for 2026 — PW Consulting Industry Brief
Executive preview
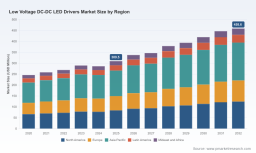
As organizations prepare budgets and product roadmaps for 2026, the low-voltage DC-DC LED drivers market demands a different strategic lens than it did five years ago. LED lighting systems are no longer just components; they are systemized value pools that span power electronics, thermal management, dimming ecosystems, software-enabled control, and aftermarket service. PW Consulting’s latest market study — anchored on a 2025 base year — synthesizes historical behavior (2020–2025) with forward-looking forecasts (2026–2032). The headline: the market is expanding with a steady compound annual growth rate of 6.2%, rising from roughly USD 245.8 million in 2020 to USD 309.5 million in 2025, and projected to approach USD 458.6 million by 2032. This trajectory underscores persistent, investment-grade demand while signaling shifting profit pools within the value chain.
Low Voltage DC-DC LED Drivers Market
Why this matters for 2026 corporate decision-making
-
Resource allocation: Firms must decide how much R&D, validation capacity, and commercial focus to allocate to low-voltage DC-DC LED drivers versus adjacent power-management segments. The trackable CAGR and near-term jump between 2025 and 2026 provide a quantitative backdrop for those trade-offs.
Low Voltage DC-DC LED Drivers Market -
Productization versus systems play: Buyers prefer suppliers who can reduce integration risk. The market reward is increasingly skewed toward vendors offering reference designs, flicker- and EMC-validated modules, and system-level efficiency gains.
Low Voltage DC-DC LED Drivers Market -
M&A and partnership timing: With mid-market concentration that leaves room for bolt-on acquisitions, 2026 is a window for strategic consolidation to capture design wins and channel access.
-
Channel and geographic strategy: Rapid pockets of adoption — ranging from retrofit commercial lighting to automotive lighting platforms — create regionally differentiated go-to-market approaches. Understanding where to prioritize engineering and sales resources is critical.
Market trajectory and what the headline numbers mean
The reported CAGR of 6.2% is not merely a statistic; it reflects a compound set of drivers: continued LED penetration across building and vehicle fleets, accelerating adoption of smart lighting controls, and incremental performance gains from semiconductor process and topological improvements. The market’s expansion from approximately USD 245.8 million in 2020 to USD 309.5 million in 2025 validates recovery and resilience during a period of supply-chain stress and shifting component cost structures. The projected advance toward USD 458.6 million by 2032 suggests that strategic entrants who capture design wins now can monetize multi-year product life cycles and aftermarket services.
Key demand vectors shaping technology and commercial choices
-
Efficiency and thermal headroom: Manufacturers targeting fixture-level cost reductions are prioritizing driver efficiency to shrink heatsink and enclosure costs. Small percentage gains in converter efficiency cascade into fixture-level BOM savings and easier compliance with thermal regulatory limits.
-
Dimming fidelity and human-centric lighting: End-users expect seamless PWM and analog dimming with imperceptible flicker. Suppliers offering validated, flicker-free reference designs win earlier in specification-led procurement cycles.
-
Automotive and safety-critical specifications: Automotive lighting imposes exacting reliability, AEC-Q certifications, and transient immunity requirements — creating a premium submarket for automotive-grade DC-DC driver solutions.
-
Integrated system solutions: Reference designs, modular engine architectures, and integrated control interfaces (including digital dimming and telemetry) shorten time-to-market for luminaire manufacturers.
-
Regulatory and standards pressure: Efficiency, EMC, and safety standards are tightening in multiple jurisdictions, influencing product roadmaps and testing investments.
Competitive landscape — who matters and why
The competitive picture is characterized by a handful of capable semiconductor leaders, specialist power-IC companies, and system-level players. Market concentration metrics indicate a top-three share consistent with a market where scale matters but differentiation still wins deals (CR3 ≈ 37.2%; CR5 ≈ 47.8%). Below are strategic reads on the core competitors that shape competitive dynamics.
-
Texas Instruments (Dallas, TX) — Strengths: Extensive portfolio of DC-DC LED driver controllers, robust reference designs, and high-quality application support. Strategic implication: TI’s playbooks favor ecosystem lock-in via design-in kits and platformization. Suppliers and OEMs should expect TI to increase design support services that accelerate specification approval cycles.
-
Analog Devices (Wilmington, MA) — Strengths: High-performance analog ICs and co-development capabilities for automotive and consumer lighting. Strategic implication: ADI is well-positioned to capture higher-margin, performance-sensitive pockets — particularly where signal integrity, sensing, and mixed-signal control are valued.
-
STMicroelectronics (Geneva, Switzerland) — Strengths: PWM-dimmable driver ICs and broad power-management ecosystem. Strategic implication: ST’s breadth enables integrated offers for vendors seeking consolidated BOMs and simplified supplier management.
-
Infineon Technologies (Munich, Germany) — Strengths: High-current hysteretic buck families with class-leading efficiencies. Strategic implication: Infineon competes on raw power-performance metrics — appealing to high-output and general-lighting segments where thermal efficiency drives fixture cost.
-
Diodes Incorporated (Plano, TX) — Strengths: Focused medium- and low-voltage LED driver ICs with practical evaluation platforms. Strategic implication: Diodes’ product breadth addresses price-sensitive markets and small-form-factor applications; partnerships with fixture manufacturers can yield rapid adoption.
-
Molex (Downers Grove, IL) — Strengths: System-level driver platforms and fixture-oriented modules. Strategic implication: Molex competes as a systems supplier that reduces integration risk for luminaires, which is attractive for high-volume OEMs seeking supplier consolidation.
-
LEDdynamics (United States) — Strengths: Niche, fixture-focused driver products. Strategic implication: Smaller players maintain agility for customized solutions — a pattern attractive to boutique luminaire designers and retrofit specialists.
-
ON Semiconductor (Scottsdale, AZ) — Strengths: Discrete and IC solutions that enable flexible power-management architectures. Strategic implication: ON’s hybrid approach can lower platform costs for customers willing to assemble near-complete solutions in-house.
-
Monolithic Power Systems (San Jose, CA) — Strengths: Compact hysteretic buck controllers and dimming-capable drivers. Strategic implication: MPS targets high-efficiency niches and compact-form-factor applications where board space and system simplicity matter most.
Practical contents of the PW Consulting report — what you get
Our study is intentionally operational. For decision-makers we include:
-
Demand-side segmentation and validated growth scenarios (baseline, upside, downside) mapped to purchasing timelines and fixture life cycles.
-
Supplier scorecards and capability matrices covering technology, reference designs, certification support, and channel reach.
-
Competitive benchmarking: design-in timelines, performance trade-offs, and go-to-market playbooks used by leading vendors.
-
Go-to-market and pricing playbooks for system suppliers and component vendors: margin models, tender-response templates, and distributor engagement strategies.
-
Supply-chain stress tests and sourcing risk maps that quantify supplier concentration and alternative sourcing pathways.
-
Engineering checklists and validation plans for flicker, EMC, thermal, and automotive-grade requirements — reducing prototyping cycles and certification risk.
-
Financial models and scenario-based ROI calculators that translate market forecasts into NPV and payback timelines for product investments.
-
Actionable M&A and partnership thesis: target profiles, valuation heuristics, and post-integration value-capture playbooks.
Strategic playbook for 2026
-
Prioritize modular platforms. Create reference architectures that accommodate PWM and DC dimming, telemetry, and quick swaps across power classes to shorten design-in cycles.
-
Invest in validated reference designs. OEMs buying fixtures value out-of-the-box compliance; suppliers who provide these shorten procurement lead times and capture premium pricing.
-
Differentiate on system-level efficiency. A 1–2% converter efficiency improvement is meaningful when amortized across millions of hours of operation; quantify system-level savings for customers.
-
Adopt a dual track for automotive: pursue AEC-Q compliance and functional safety where justified, while keeping a separate low-cost track for consumer and retrofit markets.
-
Consider bolt-on acquisitions to accelerate design-win pipelines — particularly targets that bring validated reference designs, distributor relationships, or regional manufacturing footprints.
-
Use the market’s moderate concentration to form selective alliances that create bundled offers for major luminaire OEMs.
Where the trailer ends — and why you should read the full report
This brief offers a directional and actionable view of the low-voltage DC-DC LED drivers landscape — but intentionally omits the granular segmentation matrices, regional and application-level breakdowns, and the full set of supplier-level datasheets that PW Consulting delivers in the complete report. Those datasets are essential for precise budgeting, sourcing, and product roadmapping in 2026. If your 2026 planning cycle demands validated unit-cost curves, channel-specific adoption timelines, and candidate acquisition targets ranked by integration complexity — the full report contains those deliverables, accompanied by downloadable financial models and supplier scorecards.
Engage with the full study to convert the macro growth (6.2% CAGR and a clear upward revenue trajectory) into defensible, quarter-by-quarter action plans that materially improve time-to-revenue and reduce integration risk. PW Consulting’s advisory team is available to translate the report into a tailored 90-day go-to-market sprint for product and commercial teams.
For detailed analysis of this topic, please visit the official page: Low Voltage DC-DC LED Drivers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com