

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Wellington Boots Market to Hit USD 1,842.67M by 2032 at 4.8% CAGR

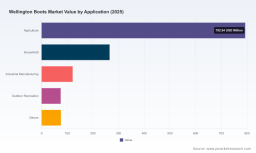
Wellington Boots Market — 2026 Strategic Preview
Executive snapshot
Our Wellington Boots Market research (base year 2025; historical 2020–2025; forecast period 2026–2032) shows a market that has recovered from mid‑decade supply shocks and is on a steady upward trajectory. At USD 1,330 Million (2025, USD Million), the category is projected to track a compound annual growth rate (CAGR) of 4.8% through 2032 under the central scenario. Market concentration remains modest — the top three firms account for less than one‑third of sales and the top five still fall well short of majority control — signalling a fragmented competitive landscape with room for both scale and niche plays.
Wellington Boots Market
Why this research matters for 2026 decisions
-
Actionable macro guidance: the forecast and scenario work in this study translate headline growth (CAGR 4.8%) into revenue paths, margin pressure points and inventory burn scenarios that CFOs and supply‑chain leads can plug into 2026 budgets.
Wellington Boots Market -
Trade & sourcing contingency: with tariff volatility intensifying, procurement teams need a clear, quantitative way to compare near‑term cost impacts of supplier re‑shoring, near‑shoring or tariff absorption strategies. Our report models these choices across realistic duty shock permutations.
Wellington Boots Market -
Product and channel prioritisation: stronger consumer appetite for eco‑materials and premium utility designs creates distinct SKU investment cases. We translate consumer trends into SKU-level NPV and time-to-payback guidance for product teams.
-
Competitive playbooks: the analysis maps who is positioned to win each demand niche — from professional workwear to outdoor lifestyle — and how competitors’ recent moves change the battleground for 2026.
Market dynamics shaping 2026 strategy
-
Tariff and trade disruption: import measures introduced since 2025 materially change landed costs for many manufacturers. Stakeholders should account for both ad valorem duties and country‑specific measures when sizing supply‑chain alternatives; new HTS rulings and specific ad valorem charges have created a discontinuity that makes single‑source Asian procurement increasingly risky for certain retail and industrial channels.
-
Raw material and inflationary pressure: rising rubber and polymer input prices, combined with elevated freight and labour costs in 2025, forced price increases that exceeded 20% for many manufacturers. Margin restoration in 2026 will depend on a mix of price architecture, cost avoidance and productivity gains rather than simple pass‑through alone.
-
Consumer preferences and sustainability: eco‑friendly materials and demonstrable sustainability credentials have moved from niche to mainstream; approximately half of new product launches since 2023 have featured eco‑materials or lower‑footprint claims. For brands targeting premium and Western markets, sustainability certification and transparent supply chains are now table stakes for growth.
-
Channel evolution: specialist workwear and fishing channels remain resilient, while lifestyle and outdoor retailing show faster adoption of premium and seasonal assortment strategies. E‑commerce complements but does not fully replace traditional route‑to‑market for many B2B buyers who prioritise fit, certification and bulk procurement.
Competitive landscape — who's shaping the market
The Wellington boots category is populated by brands with distinct strategic positioning — heritage craftsmanship, industrial specification, price accessibility, and lifestyle crossover. Our report includes deep profiles and comparative frameworks for key players, including:
-
Le Chameau (Normandy, France) — artisan rubber construction and premium dual‑material designs that trade on provenance and durability. Recent retail partnerships expand reach into mainstream premium channels.
-
Grundéns (Canada) — professional fishing and work footwear with rigorous field testing; product launches have been engineered for extreme operating conditions.
-
Xtratuf (United States) — broad appeal in commercial fishing and workwear, supported by scale under Rocky Brands ownership.
-
Rubbermaid (Atlanta, GA) — commercial and facility footwear with an emphasis on institutional procurement and specification.
-
Bogs Footwear (Portland, OR) — waterproof seamless builds that bridge farm, work and lifestyle segments.
-
Blundstone (Hobart, Australia), Aigle (France), Dunlop Boots (UK), Rockland (US), and Tingley Rubber (US) — each bringing a mix of heritage, industrial specs, or value positioning that shapes sub‑markets and buyer expectations.
Consolidation opportunities exist for firms that can scale distribution or cost‑effectively add technical differentiation. Because the category’s CR3 and CR5 metrics indicate limited dominance by incumbents, M&A or strategic alliances remain viable routes to accelerate market share for ambitious buyers.
Recent developments you must factor into 2026 planning
-
Product innovations: targeted product launches tested in demanding geographies — for example, professional fishing and work boots validated across extreme environments — are shortening time‑to‑adoption in occupational markets.
-
Retail expansion: premium collaborations and selective retail partnerships are widening consumer reach for heritage producers, changing promotional economics and inventory turnover norms.
-
Material shift: category demand is increasingly influenced by alternative polymers and recycled content; this shift both creates premium pricing power and requires supply‑chain reengineering.
-
Regulatory updates: specific HTS rulings and revised import duties in major markets have immediate P&L consequences and longer‑term sourcing implications — firms without a trade‑compliance roadmap face amplified margin erosion.
What the full PW Consulting report delivers (operationally focused)
-
An interactive forecast model (2026–2032) with scenario toggles (tariff shocks, raw material price curves, demand elasticity variants) that Senior Finance and Strategy teams can use to stress test budgets.
-
Supply‑chain stress tests and sourcing decision trees evaluating re‑shoring, near‑shoring and alternative material sourcing on a landed‑cost and lead‑time basis.
-
Go‑to‑market playbooks by channel (professional, retail, e‑commerce) with SKU rationalisation, promotional cadence and margin impact simulations.
-
Pricing architecture and value capture frameworks that balance rising input costs with elasticity and competitor positioning.
-
Competitive capability matrices and a short‑list of acquisition targets aligned to defined strategic objectives (scale, capability, channel access).
-
Sustainability roadmap and costed implementation plan for transitioning to eco‑materials while protecting margin and brand equity.
-
Regulatory and trade playbook detailing HTS implications, compliance checklists, and mitigation options for duty exposure in key export markets.
Practical recommendations for 2026 (what to do in Q1–Q3)
-
Embed tariff scenarios into procurement: re‑price top ten SKUs under multiple duty permutations and qualify second‑source suppliers within 90 days.
-
Prioritise eco‑materials for high‑margin SKUs and pilot certification for two flagship lines to capture premium positioning where demand is strongest.
-
Re‑engineer price architecture with tiered SKUs that balance margin recovery and volume protection — combine modest list increases with targeted promotions rather than across‑the‑board discounts.
-
Invest in channel segmentation analytics: allocate inventory to channels with higher conversion and lower return rates (e.g., specialist B2B routes and premium retail partners).
-
Strengthen trade compliance: assign cross‑functional ownership for HTS classification, and build an early‑warning dashboard for tariff changes that could materially affect landed cost.
-
Run a 12‑month M&A readiness programme: prepare data rooms for potential bolt‑ons that add manufacturing capability, technical lab capability or distribution reach.
Final note — the value of the full intelligence pack
This preview frames the strategic choices firms face in 2026: navigate tariff complexity, capitalise on sustainability momentum, and decide where to compete on price versus performance. PW Consulting’s full Wellington Boots Market report converts these strategic imperatives into executable plans — including the granular segmentation, SKU‑level economics, and proprietary scenario outputs that we intentionally withhold here to protect client value and maintain the report’s role as the definitive commercial toolkit.
For practitioners making 2026 investment, sourcing, or go‑to‑market decisions, the full study provides the evidence base, financial models, and implementation playbooks to move from intent to measurable outcomes. Contact PW Consulting to access the complete report and the downloadable models referenced in this preview.
For detailed analysis of this topic, please visit the official page: Wellington Boots Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com