

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Synthetic Concrete Fibers Market Poised for 6.5% CAGR through 2032

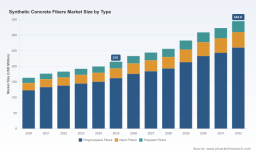
Synthetic Concrete Fibers Market — Strategic Outlook for 2026
As PW Consulting’s Senior Strategic Advisor and Head Industry Analyst, I present an executive introduction to our deep-dive research on the Synthetic Concrete Fibers market. This briefing synthesizes the market’s macro trajectory, the near-term dynamics that will shape corporate choices in 2026, and the competitor and supply-side signals that demand an immediate strategic response. This note intentionally demonstrates analytical depth while preserving the full granularity of our segmentation models and proprietary datasets for subscribers to the complete study.
Synthetic Concrete Fibers Market
Macro snapshot: a clear growth runway
Our base-year analysis (2025) and historical series (2020–2025) show an established, resilient growth pattern for synthetic concrete fibers, reinforced by structural demand in industrial flooring, precast, and infrastructure repair applications. The market expanded meaningfully during the historical window and, under our central-case forecast, continues to compound at approximately 6.5% CAGR through the 2026–2032 horizon. By 2026 the market steps into a higher-investment phase where incremental demand from large-scale industrial flooring and sustainability-driven steel-replacement strategies materially increases addressable volumes.
Synthetic Concrete Fibers Market
Two implications are immediate for decision-makers: budgeting and capacity planning should assume sustained mid-single-digit growth; and commercial strategies must balance near-term margin pressures with the long-term upside of broader fiber adoption across concrete value chains.
Synthetic Concrete Fibers Market
Dynamics to prioritize in 2026
-
Raw-material volatility is a near-term P&L driver. Polypropylene — the primary feedstock for many synthetic fibers — has experienced pronounced price swings in 2025–mid‑2026. Regional benchmarks and month-on-month movements have created a pricing environment where procurement timing and hedging materially affect product margin. Companies without active feedstock strategies will find gross margins under pressure when passing cost through to concrete customers is impractical.
-
Substitution and specification dynamics. Synthetic fibers are shifting from niche crack‑control additives to first‑line reinforcement alternatives for slabs and many industrial applications. This transition is accelerating where installers, designers, and owners value lifecycle savings, constructability advantages, and reduced safety/compliance costs versus traditional steel mesh.
-
CapEx and capacity moves matter sooner than later. Recent capacity expansions announced by tier‑1 producers signal an industry gearing up for larger projects and broader specification acceptance. Firms that delay capacity or strategic partnerships risk becoming price-takers or facing longer lead times for critical projects in 2026.
-
Digitization and specification tools change win‑rates. Commercial tools that reduce specification friction — such as mobile apps, submittal packagers, and on-site design calculators — are improving project adoption rates. Early adopters of these productivity enablers are beginning to out-compete slower peers on both proposals and long-term framework agreements.
Competitive landscape — concentrated expertise, fragmented value chain
The competitive map combines global chemical/construction majors with specialist fiber manufacturers and regional innovators. Market concentration metrics show a market led by a small set of recognized brands while overall share remains broadly distributed — a structure that rewards product differentiation, technical service, and channel intimacy.
-
Sika AG — Strengths: comprehensive fiber portfolio and recent capacity expansion to support North American demand. Strategic posture: integration of production scale with construction-market access; expect further investments in manufacturing and specification support tools.
-
MAPEI — Strengths: formulation expertise and global distribution network. Strategic posture: leveraging combined polymer chemistry and admixture relationships to offer bundled systems that simplify contractor selection.
-
Euclid Chemical — Strengths: product specialization and strong ties to local ready-mix and contractor ecosystems. Strategic posture: partnerships with large construction integrators on high‑profile projects signal an aggressive adoption strategy for macro fibers in industrial builds.
-
FORTA Corporation — Strengths: deep product breadth across macro and micro fibers, strong brand recognition in North America. Strategic posture: continued emphasis on performance testing and contractor training to defend share in slab and infrastructure projects.
-
GCP Applied Technologies — Strengths: technical toolsets (including digital specification apps) that reduce adoption friction for engineers and contractors. Strategic posture: further platformization of specification and cost-calculation tools to convert design intent into purchase orders.
-
Specialist producers (BarChip, Fabpro/Great Lakes, Polyfibers, Mighty Shield, Adfil, Belgian Fibers) — Strengths: focused R&D, CE and other regional certifications, and agile product development. Strategic posture: pursuing niche high-performance plays, regional infrastructure projects and certification-led entry into new markets.
Collectively, these players illustrate two strategic pathways that succeed: (1) scale + system offering (broad portfolios bundled with admixtures, support, logistics); and (2) focused technical leadership (high-performance fiber systems, certifications, and project-level partnerships). Our client diagnostics show high conversion rates for firms that combine commercial tooling with targeted pilot projects in heavy industrial end markets.
What the PW Consulting report delivers — practical, actionable assets
Our full report is designed for immediate operationalization by strategy, commercial, and supply-chain teams. Key deliverables include:
- Robust market model (base-year 2025) with historical series and scenario forecasts through 2032 (central, upside, downside);
- Raw-material sensitivity analyses and a procurement playbook with hedging and supplier diversification templates;
- Detailed go‑to‑market playbooks for industrial flooring, precast, and infrastructure segments (including specification win strategies and contractor incentive models);
- Competitive heatmaps and vendor capability matrices, including technology differentiators, certification maps, and likely M&A targets;
- Commercial tools: pricing elasticity tables, sample submittals, ROI calculators for owners, and a modular pilot-to-scale implementation checklist;
- Regulatory and sustainability impact assessment, with carbon-intensity scenarios and lifecycle cost comparisons versus steel-based reinforcement;
- Customizable Excel financial model with unit economics, margin scenarios, and CapEx planning templates for 2026 budget cycles.
Note: The public summary here highlights the types of insights included. The full report contains the granular segmentation, regional and application breakouts, and price-band tables required to operationalize these templates — available through PW Consulting’s client portal.
Priority strategic moves for 2026 (sequenced)
-
Immediate (0–6 months) : Lock procurement flexibility — adopt staggered purchase contracts or swap-based hedges for polypropylene exposure; secure short-term off-take agreements with strategic ready-mix partners to stabilize demand channels.
-
Near term (6–18 months) : Pilot bundled solutions with national contractors and owners in high‑volume industrial flooring projects; deploy specification-support tools to reduce friction in bid processes; evaluate brownfield capacity additions in low-cost regions where logistics advantages exist.
-
Medium term (18–36 months) : Invest in product differentiation — higher-performance monofilament and hybrid fiber systems aimed at heavy-load and long-life infrastructure segments; consider bolt-on acquisitions of specialist fiber makers to accelerate technology access and certification portfolios.
Risk matrix and contingency planning
The three highest-probability, high-impact risks for 2026 are:
- Raw‑material price spikes compressing margins if cost pass-through is limited;
- Faster-than-expected steel-price or alternative-technology rebounds that slow fiber substitution rates;
- Regulatory changes or certification delays in key markets that obstruct large project pipelines.
Mitigants include diversified feedstock sourcing, contract clauses allocating material-cost risk, accelerated certification programs in target geographies, and near-term commercial incentives tied to total cost of ownership savings for owners.
Concluding perspective — why 2026 is a strategic inflection
The synthetic concrete fibers market is no longer an emergent niche: it is transitioning into mainstream reinforcement strategy in several high-value applications. With a clearly upward market trajectory and a multi‑year compound growth profile, 2026 represents a decision point for businesses to convert opportunity into durable advantage. Firms that align procurement, product development, and commercial tooling in the coming 12 months will capture outsized share as adoption scales.
To convert the high-level direction above into executable plans — including itemized regional and application breakouts, price-band tables, and an acquisition shortlist — access the full PW Consulting Synthetic Concrete Fibers Market report and our implementation toolkit. The detailed datasets and scenario models therein are calibrated to inform 2026 capital allocation, roll‑out sequencing, and M&A prioritization.
Contact PW Consulting to schedule a tailored briefing or request the full report, which includes the complete segmentation, granular forecasts, and plug‑and‑play operational templates designed for immediate deployment.
For detailed analysis of this topic, please visit the official page: Synthetic Concrete Fibers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com