

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Sanitary Napkin Market Set to Grow at 6.98% CAGR (2026–2032)

Sanitary Napkin for Feminine Care Market — A 2026 Strategic Preview
As PW Consulting’s lead industry analyst, I present a focused preview of our full market study on the Sanitary Napkin for Feminine Care Market. This briefing is written for senior executives and investment teams who must translate market rhythms into strategic choices in 2026. It highlights the macro trajectory, regulatory inflection points, competitive posture and the action-orientated outputs contained in the full report — while reserving the granular segment-level tables that are available on the source page.
Sanitary Napkin for Feminine Care Market
High‑level market trajectory you need to accept as baseline
The market has moved from a modest base in early 2020 to a materially larger and structurally different market by 2025. After five years of steady expansion, the market reached a meaningful milestone in our base year (2025). Our forecast from 2026–2032 assumes a compound annual growth rate of approximately 6.98%, with the market continuing to expand driven by product premiumization, improved distribution access in developing markets, and evolving regulatory requirements that raise quality and performance thresholds.
Sanitary Napkin for Feminine Care Market
These macro dynamics should be treated as givens in 2026 planning: steady demand growth, higher regulatory compliance costs, and intensifying product differentiation along softness, absorbency, breathability and sustainability vectors.
Sanitary Napkin for Feminine Care Market
Why this study matters for 2026 decision-making
- Regulatory regime shift: The industry is operating under new, binding regulatory expectations. Notably, recent authorities have clarified classification and testing expectations for menstrual products and updated quality system requirements. These changes impose measurable compliance costs, but also create barriers to entry that can be turned into strategic advantage for incumbents who act early.
- Proof-of-performance now table stakes: Performance testing and labeling guidance have tightened. Buyers — retail chains, health systems and large private-label customers — will increasingly demand documented performance and traceability as part of purchase decisions.
- Fragmented competitive structure: Despite strong brand names and scale pockets, the market remains materially fragmented at the global level. This fragmentation creates M&A and partnership opportunities for companies seeking to build scale quickly or access distribution niches.
- Materials & innovation pressure: Rapid adoption of new nonwovens, film constructions and alternative substrate chemistries is reshaping the product set. Manufacturers that align product and manufacturing strategy with these material trends will capture disproportionate margin expansion.
- Sustainability and ESG are table stakes: Consumers and retail buyers are attributing higher value to reduced plastic content, certified manufacturing, and transparent supply chain claims.
What the full PW Consulting report contains (practical, decision‑ready deliverables)
- Verified market sizing and time-series (historical 2020–2025 and detailed forecasts 2026–2032) with scenario variants (base, upside, downside) and modeled sensitivities to raw-material and regulatory cost shocks.
- Demand drivers and buyer segmentation (channels, buyer personas, pricing sensitivity) plus a playbook for premiumization versus value propositions.
- Regulatory & standards roadmap: mapping of recent guidance, effective dates, audit-ready checklists for QMS alignment (including ISO‑aligned practices) and a gap analysis template for faster compliance conversion.
- Competitive landscaping: 40+ company profiles with capability maps, manufacturing footprints, go-to-market strengths, OEM/ODM exposure, private‑label activity and an M&A target shortlist calibrated to multiple strategic scripts.
- Commercial and supply‑chain stress tests: raw material cost models, alternative sourcing scenarios, nearshoring cost/benefit matrices, and a three‑year capex ranking for production scale or line conversion.
- Innovation & product roadmap: patent cluster analysis, feature-attribute value curves, and a prioritized R&D investment allocator that ties to commercial payback timelines.
- Sustainability assessment tools: lifecycle hotspots, polymer substitution pathways and procurement scorecards aligned to retailer requirements.
- Investor & Board materials: decision memos, valuation scenarios, KPI dashboards and an integration playbook for acquisitions.
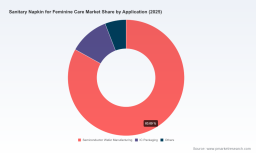
Note: the full dataset includes the granular segmentation tables (by type, by application, by region and channel) and detailed revenue line items. They are intentionally omitted here to preserve the strategic value of the proprietary work — the full breakdown is available on the source page.
Competitive snapshot — who’s shaping the market and how
The competitive field combines global brand leaders, national champions and specialist OEM/ODM producers. Key strategic archetypes we observe:
- Global brand integrators: These players leverage well-known consumer brands, sophisticated marketing, and broad retail reach. Their 2024–2026 moves include partnerships and brand-led social programs that reinforce consumer trust while opening institutional channels.
- Regional champions: Companies with strong domestic distribution and cost-efficient manufacturing that selectively export to neighboring markets. These firms are often leaders in private-label production and rapidly adapt to local channel dynamics.
- OEM/ODM specialists: Turnkey producers focused on manufacturing excellence, compliance credentials and B2B service relationships. They are strategic partners for retailers and white‑label players looking to expand range quickly without heavy capex.
Representative company behaviors:
- Established consumer goods multinationals are extending social-impact partnerships and reinforcing brand purpose to build deeper loyalty among younger cohorts.
- R&D‑led companies are introducing soft-touch and breathability improvements to create meaningful perceived differentiation at acceptable unit-cost premiums.
- OEM and private-label suppliers are investing in certification and FDA registration to capture the growing demand from global retailers seeking compliant suppliers.
Two recent developments underscore the incline of competitive intensity and regulatory pressure: (1) strategic partnerships and product innovations aimed at premiumization and social reach, and (2) regulatory updates that raise compliance requirements and documentation expectations for manufacturers and buyers alike.
Regulatory inflection: what changed and what it means for 2026
- Regulatory bodies have issued tighter guidance on classification, performance testing and labeling. These changes raise the entry bar for new manufacturers but provide incumbents with defensible quality advantages if they convert compliance into commercial claims.
- Quality Management System requirements have been updated to align more closely with international medical-device standards. Firms that accelerate QMS upgrades will reduce audit friction, unlock institutional contracts and avoid rework costs.
- International standards work is active and expected to crystallize soon; organizations that participate in standards-setting or adopt draft norms early gain first-mover benefit in tender processes and retailer lists.
Strategic actions recommended for 2026
- Compliance acceleration: Immediate gap assessment against the new QMS requirements, prioritized remediation roadmap (documentation, validation, supplier controls). Target: obtain audit-readiness within 9–12 months.
- Portfolio reallocation: Reweight SKU investment toward high-margin premium and certified ranges; rationalize loss-making SKUs based on a quick SKU-level contribution analysis.
- Supply-chain resilience: Execute raw-material hedging pilots and shortlist dual sourcing partners; consider selective nearshoring for high-value SKUs to reduce lead-time risk.
- M&A & partnerships playbook: Use the market’s fragmentation to pursue tuck-ins that add distribution or manufacturing capability; co-development partnerships with innovation-focused players to accelerate new substrate adoption.
- Commercial modernization: Implement buyer persona segmentation, recalibrate pricing ladders and roll out evidence-based marketing (performance claims tied to test data) for trade negotiations.
- ESG positioning: Publish a three-year sustainability roadmap tied to procurement and packaging targets — this is increasingly required by large retailers and institutional buyers.
How Boards and deal teams should use this study
The report is structured to support three immediate use cases for 2026:
- Fast-track M&A diligence: use the competitive maps and scoring model to prioritize targets and estimate integration CAPEX and compliance costs.
- Budget allocation: translate forecast scenarios into 3-year capex/opex plans with clear break-even analyses for line conversions, marketing spends and certification investments.
- Risk mitigation: implement the supplied regulatory gap checklist, supplier audit protocol and SKU de‑risking playbook to reduce adverse surprises in the next procurement cycle.
Closing — the strategic payoff of engaging with the full report
Our full study provides the detailed segmentation, revenue tables and proprietary scenario models that power board-level decisions. It is designed as an operational toolkit — not just a market narrative — enabling executives to convert the market’s structural growth (and its regulatory tightening) into defensible competitive advantage. For teams weighing entry, expansion, M&A or product repositioning in 2026, the actionable analyses and templates in the full report materially shorten the path from insight to execution.
To obtain the granular segment breakdowns, the full forecast tables and the company-by-company strategic dossiers that support the recommendations above, please consult the source page for this PW Consulting study.
For detailed analysis of this topic, please visit the official page: Sanitary Napkin for Feminine Care Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com