

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Sunglasses Market Poised for 6.5% CAGR, Hits USD 190 Million in 2025

Sunglasses Market 2026: A Strategic Preview for Executive Decision-Makers
As PW Consulting’s lead industry analyst, I present a high‑level briefing designed to orient senior executives and investment committees ahead of critical 2026 planning cycles. Our full Sunglasses Market study (base year 2025; historical window 2020–2025; forecast period 2026–2032) combines a rigorous market model with decision‑ready playbooks. This preview highlights the strategic implications embedded in our analysis while deliberately withholding segmented line‑by‑line data to preserve the full report’s value as the source of actionable intelligence.
Sunglasses Market
Why this report matters in 2026
- Translate a steady mid‑single digit market growth trajectory into prioritized capital allocation: the market is expanding at a compound annual growth rate of 6.5%, creating windows for both organic expansion and bolt‑on consolidation.
- Operate through trade volatility and tariff shocks: recent duty changes and raw‑material pressures mean procurement strategy and nearshoring decisions will materially affect margin outcomes.
- Optimize product and channel mixes for new consumer behavior: the interplay of fashion, performance, and sustainability is reshaping SKU economics and retail assortments.
- Inform M&A and partnership targets with a concentration lens: a handful of global players capture the majority of market value, leaving clear white spaces for nimble challengers and regional champions.
Market at a glance — what the macro data tells you
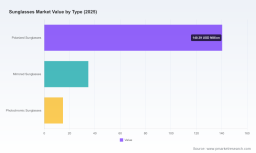
The sunglasses market has moved from a recovery phase in the early 2020s into a sustained expansion as discretionary spend normalizes and performance‑oriented categories gain prominence. Our model benchmarks show the overall market at USD 190 million in 2025 and projects a progressive climb to approximately USD 310 million by 2032, underpinned by a 6.5% CAGR across the forecast horizon. Those headline figures mask diverging dynamics by product configuration, channel, and regional exposure — divergence that will determine winners and losers over the next 18 months.
Sunglasses Market
Three structural forces underpin the top‑line growth: (1) premiumization and brand differentiation, (2) higher consumer willingness to pay for functional lens technology and sustainability credentials, and (3) channel sophistication, particularly in digital direct‑to‑consumer and omnichannel experiences. Our scenarios account for upside and downside permutations around macroeconomic growth, currency swings, and tariff regimes.
Sunglasses Market
Key dynamics reshaping strategy
- Trade and input cost shocks: Industry participants continue to grapple with tariff interventions enacted in 2025 that raised duties on certain imported materials and inputs. These measures logically pressure cost of goods sold and force a reappraisal of global sourcing networks, supplier contracts, and landed‑cost models.
- Material and manufacturing adjustments: Steel and aluminium tariffs and additional duties on specific origin materials have already driven short‑term sourcing shifts. Expect manufacturers and OEMs to accelerate qualification of alternative suppliers and to revisit regional manufacturing footprints.
- Sustainability as competitive advantage: Leading players are already substituting recycled inputs at scale. One manufacturer’s rollout of eco‑frame collections using a majority share of recycled content produced measurable shifts in retail unit mixes during peak seasons — a clear signal that sustainability investments yield commercial payback when paired with marketing and retail execution.
- Channel evolution and retail economics: Brick‑and‑mortar still matters for premium fitting and prescription conversion, but digital conversion funnels and subscription models are capturing incremental share. Retail economics are rapidly being redrawn by fulfillment costs, returns, and the balance between exclusivity and wide distribution.
Competitive landscape — what incumbents and challengers are doing
Market concentration is notable: the largest three players capture a sizeable majority of market value, with the top five controlling an even larger share. This concentration drives both competitive intensity at the premium end and opportunity at adjacencies where smaller, brand‑centric players can cultivate loyal niches.
- EssilorLuxottica (France): Global scale, vertical integration, and an unparalleled brand portfolio position it as the default benchmark for market standards. Its recent showcase of future‑ready eyewear at major trade events signals ongoing investment in lens innovation and omnichannel retailing.
- Kering Eyewear (Italy): Luxury positioning and lifestyle storytelling remain its strengths. Recent global brand campaigns emphasize emotional resonance and adventure themes, underscoring the value of creativity in driving premium ASPs.
- Safilo Group (Italy): The firm’s strategic acquisitions to broaden eyewear portfolios reflect a consolidation play to capture differentiated design and distribution capabilities. M&A activity among established houses is likely to accelerate as firms seek scale and access to adjacent consumer segments.
- De Rigo Vision and Marcolin (Italy): Both are doubling down on sustainability and licensed fashion partnerships. Their emphasis on eco‑materials and high‑performance collections demonstrates how mid‑tier manufacturers can compete on both ethics and technical performance.
- Maui Jim, goodr, Bajio (United States): These brands illustrate the premium‑to‑value spectrum within polarized and performance eyewear. Proprietary lens technologies and highly targeted brand narratives (e.g., fishing, athletics, no‑bounce active wear) create defensible niches versus mass competitors.
Report contents — what you’ll receive (select, practical deliverables)
Our full Sunglasses Market report is structured to move teams from insight to action. Key, operational deliverables include:
- Scenario‑based market forecast models (2026–2032) with configurable assumptions for price, mix, regional growth, and tariff shocks.
- TAM/SAM/SOM mapping tools to quantify addressable opportunity by channel and product family (note: detailed split tables are available in the full dataset).
- SKU‑level profitability matrices and suggested assortment rationalization to improve margin capture per distribution channel.
- Supplier risk heat maps and a supply‑chain resilience playbook covering nearshoring, hedging, and contract redesign.
- M&A target screening framework and valuation multiples tailored to eyewear category economics.
- Go‑to‑market playbooks for premium vs. value segments and for direct vs. wholesale channels, including customer acquisition cost benchmarks and lifetime value levers.
- Regulatory and tariff impact models with recommended mitigation strategies for procurement, pricing, and inventory planning.
- Commercial roll‑out templates for sustainability initiatives, including expected payback windows and trade‑off analysis versus premium positioning.
Strategic imperatives for 2026
- Re‑engineer procurement for volatility: introduce dual‑sourcing and short‑cycle contracts for critical lens and frame inputs; build landed‑cost scenarios into SKU P&Ls.
- Prioritize high‑margin, high‑engagement SKUs: focus investment on product technologies and brand stories that sustain pricing power rather than competing on cost alone.
- Accelerate sustainability investments with measurable KPIs: quantify the conversion lift and margin impact of eco‑SKUs and incorporate those metrics into assortment planning.
- Use M&A selectively to plug capability gaps: target companies that bring proprietary lens technology, unique channel access, or supply‑chain advantages rather than generic scale alone.
- Design flexible channel strategies: optimize the balance of exclusive wholesale, D2C, and retail partnerships to manage inventory turns and customer acquisition costs.
- Embed tariff and regulatory scenario planning into all major investment decisions: run upside/downside cases that stress test margins, working capital, and capital expenditure plans.
How executive teams should use this intelligence
Senior leaders should treat our study as both a forecasting tool and a decision‑support system. Key uses include:
- Board‑level strategic reviews and long‑range planning exercises, using the scenario models to set capital allocation limits and M&A appetite.
- Procurement negotiations, leveraging our landed cost and supplier risk diagnostics to set contract terms and scorecard KPIs.
- Commercial planning and assortment strategy, where the SKU profitability playbooks help optimize holiday and seasonal assortments without overexposing capital.
- Investor communications and integration planning for acquisition targets, with valuation sensitivity analyses and merger synergy playbooks.
Next steps and access to the full analysis
This briefing surfaces the strategic shape of the sunglasses market in 2026 and the operable choices executives face. For teams seeking the full dataset, segment breakouts, and downloadable scenario models, the comprehensive report provides granular tables, retailer‑level insights, and templates that translate our high‑level recommendations into executable plans. To access the complete intelligence package — including our interactive forecast model and the full competitive scorecards — please visit the PW Consulting report page or contact our research team directly.
In an industry where a few players command scale and many niche brands capture passion, the winners in 2026 will be those who convert macro growth into resilient margins through smarter sourcing, sharper brand positioning, and agility across channels. Our Sunglasses Market study is designed to make that conversion measurable, repeatable, and fundable.
For detailed analysis of this topic, please visit the official page: Sunglasses Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com