

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Sulphur Recovery Market Poised for 2.51% CAGR Through 2032

Sulphur Recovery Market: Strategic Preview for 2026 Decision-Making
Executive teaser
As organizations prepare capital allocation and technology roadmaps for 2026, clarity on the sulphur recovery market’s trajectory is no longer optional — it is a strategic necessity. PW Consulting’s latest Sulphur Recovery Market study (base year 2025, historical 2020–2025, forecast 2026–2032) delivers that clarity at the macro level while preserving the competitive and segment detail behind a gated analysis. This preview highlights the study’s strategic value: how to translate observed market dynamics, regulatory pressure, and vendor positioning into executable decisions in 2026 — without disclosing the underlying proprietary segment tables that drive our forecasts.
Sulphur Recovery Market
Macro trajectory and what the numbers mean for 2026
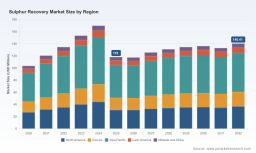
Our market model shows a multi-year recovery path following a notable recalibration in 2025. The aggregate market measured in the study peaked through the early 2020s, experienced a material contraction in the base year (2025), and then resumes growth across the forecast window. After a small transition year in 2026, the market expands steadily to the end of the forecast period, consistent with an annualized growth profile of approximately 2.51% (CAGR, 2026–2032).
Sulphur Recovery Market
Why this matters to 2026 planning: a modest but persistent CAGR means that timing and selectivity matter. Large, irreversible investments (new-build SRUs, full-scale retrofits) will face a market environment where demand growth is measured rather than explosive. Conversely, targeted investments — modular units, advanced tail-gas treating retrofits, and services that optimize operating reliability — can capture outsized returns by aligning with regulatory drivers and feedstock mix shifts.
Sulphur Recovery Market
Market dynamics driving near-term choices
-
Regulatory compression on sulfur emissions has become a dominant forward force. Evolving limits under frameworks such as 40 CFR for EPA-regulated operations, state-level permitting regimes, and expanded Emission Control Areas for marine fuels are creating persistent demand for high-performance sulphur recovery solutions and tail gas treatment upgrades.
-
Feedstock variability in gas processing and refining — especially swings in acid gas H2S concentration — is increasing demand for flexible process architectures. Operators who preserve optionality in design and can scale treatment intensity will manage margin volatility better.
-
Project phasing and supply-chain dynamics contributed to the 2025 market correction. Several projects were deferred or re-scoped, producing a one-time reduction in annual spend that is driving the subdued 2026 baseline before recovery resumes.
-
Technology mix evolution: classical Claus-based systems remain the backbone of recovery, but low-temperature oxidation solutions, advanced tail-gas treating (TGTU), and modular fabrication approaches are gaining traction where emissions or operational constraints demand them.
Technology and process implications for 2026 investments
For 2026 capital plans, three technical priorities emerge from our analysis:
-
Tail gas treatment as a force-multiplier: Investments that tighten tail-gas emissions — either through advanced catalytic options or hybrid process trains — offer both compliance and margin advantages, especially in markets tightening marine and refinery fuel standards.
-
Modularity and brownfield integration: Shorter schedule, lower execution risk modular SRUs and retrofit packages permit operators to act within the constrained growth environment. These approaches are particularly attractive where permitting timelines and uptime constraints dominate.
-
Digital and reliability upgrades: Predictive maintenance, catalyst life extension analytics, and remote monitoring for SRU and TGTU systems reduce operating risk and enable deferred capital while preserving compliance — a critical tradeoff in a modest-growth market.
Regulatory and feedstock landscape — the near-term mandate
Regulatory tightening is not uniform, but its direction is clear: lower permitted SO2 and sulfur-in-fuels ceilings are expanding the technical bar for recovery systems and tail-gas polishing. Additionally, expansions of maritime Emission Control Areas and consequential downstream fuel quality demands are creating pockets of elevated retrofit urgency, especially in export-oriented refining hubs. Operators and investors must account for these compliance requirements when sizing 2026 projects and negotiating performance guarantees.
Competitive landscape — who matters and why
The sulphur recovery supply chain is concentrated: the market structure benefits established licensors and engineering firms while creating niches for specialist service providers. Our concentration metrics indicate a market where the top three providers capture a substantial portion of activity, and the top five further consolidate incumbent advantage — a dynamic that shapes pricing power, lead times, and partnership opportunities.
-
Licensors and process houses: Firms offering integrated Claus and advanced tail gas technologies remain central to large new-build and upgrade contracts. They command advantage through proven process licenses, catalyst supply relationships, and long-cycle service agreements.
-
Engineering and EPC partners: Global engineering groups and regional EPC specialists control execution risk and schedule — a critical differentiator for operators constrained by uptime and permitting windows.
-
Specialist service and optimization players: Companies focused on SRU optimization, catalyst management, and turnaround execution can unlock rapid value for operators seeking OPEX improvements without committing to large CAPEX.
Representative firm capabilities covered in the full study (selected examples):
- Vendors offering full Claus and tail gas portfolios, including licensed process variants and integrated degassing solutions.
- Engineering firms providing front-end design, modular deliverables and EPC execution with SRU specialization.
- Service specialists delivering optimization, maintenance, and brownfield reliability programs for SRU, TGTU and sour water systems.
Recent market signals that matter for 2026
-
Strategic contract awards for front-end and FEED work on major gas projects underscore continued investment appetite in upstream-associated sulphur management solutions.
-
Modernization programs on existing gas plants that target near-zero sulphur slip indicate a clear market for high-efficiency upgrades and performance guarantees.
-
Regional refinery SRU projects are completing, signaling that operators are renewing their asset bases and will require aftermarket services and lifecycle support.
What PW Consulting’s full report delivers (operationally actionable)
Our full Sulphur Recovery Market study moves beyond headline forecasts to practical tools and decision-support frameworks tailored for 2026 execution cycles. Key contents include:
- Top-down market sizing and bottom-up project database (gated) with project status, timelines and vendor relationships.
- Scenario-based forecasts reflecting regulatory tightening, oil & gas capex cycles, and feedstock volatility.
- Technology deep dives and comparative performance matrices for Claus variants, low-temperature oxidation and tail-gas treating options.
- Vendor scorecards with licensing footprints, typical delivery models, and procurement risk profiles.
- CapEx/Opex benchmarking templates for new-build vs. retrofit decision-making and payback sensitivity tools.
- Execution playbooks: FEED to commissioning checklists, modular delivery considerations and contract structures that reduce schedule and performance risk.
- Service and aftermarket opportunity mapping: catalyst management, reliability contracts and digital retrofit pathways.
- Regulatory impact assessments and compliance stress tests by policy scenario.
How to use these insights for 2026 decisions
Translate the study into immediate actions using three practical moves:
-
Deploy a two-track CAPEX posture: preserve optionality with modular retrofit pockets while selectively pursuing full-scale upgrades where regulatory or feedstock realities make them unavoidable.
-
Lock performance-based contracts with licensors and EPCs that align payment to demonstrated sulphur removal and uptime metrics; where possible, insist on staged milestones to de-risk execution.
-
Invest in low-capex digital reliability and catalyst-lifecycle programs to extract near-term OPEX improvements and defer larger CAPEX until market direction becomes clearer.
Closing — why this preview should lead you to the full study
For executives, asset managers and engineering leaders planning 2026 investments, the choice is between acting on high-level impressions or on structured, scenario-tested evidence. PW Consulting’s Sulphur Recovery Market study provides the latter: a market blueprint that combines a disciplined macro forecast (anchored to a 2.51% CAGR across 2026–2032), competitive intelligence, regulatory stress-testing, and operational playbooks. This preview surfaces the strategic implications you need now; the full report supplies the granular, segment-level breakdowns and project-level data required to finalize contracts, capital approvals and procurement strategies.
To evaluate deal structures, vendor selection, and retrofit timing against the complete dataset — including regional and application-level segmentation, project-by-project timelines, and the vendor scorecards — please consult the full report available on our research portal.
For detailed analysis of this topic, please visit the official page: Sulphur Recovery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com