

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Food Service Equipment Market to Reach USD 66.6B by 2032 at 7.0% CAGR

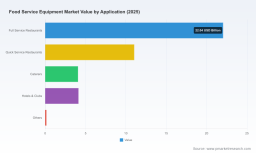
Food Service Equipment Market 2026: Strategic Imperatives from PW Consulting
As companies plan capital allocation and go-to-market moves for calendar-year 2026, a fresh, pragmatic view of the global food service equipment market is no longer optional—it is a strategic necessity. PW Consulting’s latest market study (base year 2025; forecast 2026–2032) synthesizes macrogrowth, regulatory shifts, supplier dynamics, and operator economics into an operational playbook. At the headline level, the market sits at approximately USD 41.47 Billion in 2025 and is projected to grow at a compound annual growth rate of 7.0%, reaching roughly USD 66.59 Billion by 2032. Below we outline why these topline indicators matter for executive decisions in 2026 and what practical actions senior leaders should prioritize.
Food Service Equipment Market
Why the 2026 Inflection Matters
-
Growth with nuance: A steady ~7% CAGR signals a healthy expansion that supports incremental capacity investment, but the pace masks important pockets of faster change—driven by energy regulation, labor economics, and digitization—that require targeted strategies rather than broad-brush plays.
Food Service Equipment Market -
Policy and incentive dynamics: Recent regulatory updates and incentive frameworks increasingly reward energy-efficient equipment. ENERGY STAR eligibility is now material to utility rebates and procurement economics, making efficiency compliance a near-term commercial lever.
Food Service Equipment Market -
Cost and supply pressure: Volatility in steel and aluminum prices and rising wage costs are compressing margins for OEMs and operators alike. The result is accelerating demand for capital equipment that both reduces operating expense and improves throughput.
-
Channel and aftercare as profit pools: With hardware commoditizing in many categories, aftermarket services, consumables, and equipment-as-a-service business models are becoming primary differentiation and margin drivers.
What PW Consulting’s Report Gives You (Actionable, Not Academic)
This report is designed as a decision-support toolkit for executives who must act in 2026. It deliberately balances strategic depth with confidentiality—presenting the insights you need to make decisions while reserving detailed segment-level datapoints for our subscribers and consulting clients. Key deliverables include:
-
Forward-looking demand model (2026–2032) calibrated to macro scenarios and validated against recent installer and operator data—designed for integration into capital planning models.
-
Scenario playbooks (baseline, accelerated efficiency adoption, and downside) that convert market growth into prioritized investment triggers and KPI targets.
-
TCO and ROI templates for new-build vs. retrofit decisions, including energy, labor, maintenance, and incentive capture inputs.
-
Supplier risk and concentration matrix with mitigation pathways—practical for procurement negotiations and single-supplier contingency planning.
-
Aftermarket commercialization playbook: service tiers, subscription pricing templates, and digital maintenance roadmaps to lift lifetime customer value.
-
Regulatory and incentive checklist: ENERGY STAR alignment, electrical and gas safety compliance, pressure vessel and food-contact standards, and grant/reimbursement pathways for institutional segments.
-
Channel execution templates: distributor segmentation, specification pathways for large operators, and value-based pricing constructs for OEMs and resellers.
Competitive Landscape — What Leading Players Reveal About Strategy
The competitive field combines global platform players with strong brand portfolios and specialist manufacturers with deep technical moats. Several strategic themes emerge from the activities of market leaders:
-
Scale + breadth: Large diversified groups continue to consolidate positions by combining broad channel reach with extensive product suites. This enables one-stop procurement for large restaurant chains and institutional buyers while supporting cross-sell of aftermarket services.
-
Product specialization and premiumization: Firms focused on high-performance cooking systems and precision refrigeration continue to command premium positioning, especially where energy savings or operational consistency directly affect operator economics.
-
Service and solutions orientation: Vendors that pair hardware sales with service contracts, predictive maintenance, and spare-parts logistics are unlocking higher-margin, recurring revenue streams.
Representative company patterns to watch:
-
Leading global manufacturers with extensive brand portfolios are investing in channel density and product breadth to remain buyers’ primary vendors for multi-site operators.
-
Specialist refrigeration and ice-equipment manufacturers are leveraging technical differentiation—particularly around energy efficiency and reliability—to win utility incentives and to penetrate institutional channels.
-
Heavy-duty cooking and food-preparation equipment suppliers emphasize durability and serviceability; they are partnering with nutrition and education-focused organizations to capture institutional grant-funded upgrades.
Recent market actions underscore these dynamics: new product introductions positioned for cost-conscious operators, investments in customer experience and design centers, targeted partnerships to secure institutional demand, leadership changes that signal strategic refocus in major groups, and trade-show presentations that highlight energy-recovery innovations. Each of these moves provides a near-term signal for competitive intensity and capability shifts through 2026.
Industry Headwinds and Tailwinds to Model Into 2026 Plans
-
ENERGY STAR and incentive alignment: As utility incentives increasingly tie to ENERGY STAR and similar certifications, capturing rebates materially improves equipment ROIs—altering procurement windows and upgrade cycles.
-
Materials volatility: Steel and aluminum price swings are an input-cost risk for OEMs; commercial teams should build cost pass-through clauses and alternative-material strategies into longer-term supply agreements.
-
Labor economics: Rising hourly wages in food service elevate the ROI of labor-saving equipment—accelerating replacement cycles for lower-performing units.
-
Regulatory complexity: Compliance across electrical, gas, pressure-vessel, and food-contact regulations is non-negotiable for market access; proactive certification reduces time-to-market and tender friction.
-
Public funding and reimbursements: School and institutional equipment grants are a lever for suppliers that can execute fast and meet program requirements—creating near-term demand pockets.
Strategic Moves for 2026 — A Checklist for Decision-Makers
-
Prioritize energy-compliant SKUs in procurement and product development roadmaps. Model rebate capture in every business case to shorten payback periods.
-
Build modular service offerings and subscription models. Test pilot ‘equipment-as-a-service’ in a focused geography or account set to validate unit economics and channel mechanics.
-
Hedge material exposure via multi-sourcing, forward contracts, and design-to-cost programs. Consider nearshoring critical components where lead time and cost trade-offs justify the investment.
-
Accelerate digitization—remote monitoring and predictive maintenance will be differentiators for multi-site operators and an upsell into aftermarket revenues.
-
Engage with incentive and grant administrators early. For public and institutional channels, administrative friction is often the primary barrier to purchase; vendors who simplify the reimbursement process win.
-
Use scenario planning anchored to the report’s baseline (7% CAGR) but stress-test for faster efficiency adoption and incentive-driven accelerations. Align capex spend to trigger points rather than calendar dates.
-
Formalize M&A and partnership criteria to capture aftermarket capabilities, energy-technology IP, or distribution density—areas where returns are accelerating faster than in commoditized hardware.
Next Steps — How to Use This Research in 2026
Executives benefit most when market intelligence is operationalized. PW Consulting recommends three immediate actions for 2026 planning cycles:
-
Run a 90-day “investment triage” using our TCO templates: identify top 10 upgrade opportunities where energy incentives plus labor savings yield the shortest payback.
-
Initiate vendor scorecards that include service economics, compliance readiness, and supply-risk indicators; deploy these in upcoming RFPs and renewals.
-
Commission a bespoke strategic brief if pursuing M&A or piloting an equipment-as-a-service model; our team can map targets and build integration economics aligned to your balance-sheet objectives.
Pushing decisions without calibrated market insight risks misallocated capital and missed operational savings. PW Consulting’s Food Service Equipment Market study gives you the macro runway, the operational toolset, and the competitive context needed to make confident choices in 2026—while reserving the granular segmentation and customer-level analytics for subscribers and project engagements to preserve commercial advantage.
Contact PW Consulting to arrange a briefing and to access the full dataset, segment-level forecasts, and the decision-support templates that turn this market intelligence into executable boardroom actions.
For detailed analysis of this topic, please visit the official page: Food Service Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com