

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
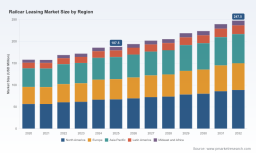
PW Consulting: Railcar Leasing Market to Hit USD 247.5 Million by 2032 (5.5% CAGR)

Railcar Leasing Market 2026: Strategic Outlook for Decision-Makers
As PW Consulting’s Senior Strategic Advisor and Lead Industry Analyst, I present a distilled strategic introduction to our latest Railcar Leasing Market research. This briefing frames the analysis you need to prioritize capital allocation, partnership formation, and regulatory engagement in 2026 — while preserving the granular proprietary insights contained in the full study.
Railcar Leasing Market
Why this research matters in 2026
The railcar leasing market is transitioning from a recovery phase into structurally higher demand driven by supply-chain reshoring, modal shift initiatives and regulatory-driven fleet renewal. For executives evaluating fleet investments, leasing partnerships or market entry strategies in 2026, timely, decision-ready intelligence reduces execution risk and creates windows for disproportionate value capture. Our report synthesizes historical performance (2020–2025), a detailed 2026–2032 forecast, and scenario-based implications calibrated to current regulatory and competitive shocks.
Railcar Leasing Market
Market trajectory at a glance
Key macro takeaways: on a USD million basis the market expanded steadily over 2020–2025 and, using 2025 as the base year, PW Consulting projects compounded annual growth of 5.5% through 2032. By our base-year accounting conventions the market progresses from its mid‑2020s level to materially higher demand by the end of the forecast window. This growth is underpinned by incremental leasing activity, higher replacement cycles and an increasing preference among shippers and operators for flexible, asset-light fleet models.
Railcar Leasing Market
Dynamics reshaping strategy
-
Regulatory squeeze and content constraints. New freight-car safety and domestic-content provisions enacted in recent years affect procurement timelines, eligible supply sources, and total cost of ownership. Compliance timelines introduce procurement bottlenecks for OEMs and lessees, creating near-term arbitrage for lessors who can offer compliant fleets or financing solutions.
-
Consolidation and concentration patterns. Market concentration remains moderate: the combined market share of the top three and top five global players signals an industry with significant scale advantages but still room for regional and specialized challengers. This structure favors firms that can combine scale, maintenance capabilities and financing flexibility.
-
Vertical integration and manufacturing partnerships. Recent strategic alliances demonstrate a push toward integrated manufacturing–leasing–service platforms. These deals shorten lead times, permit better lifecycle cost engineering, and enable captive financing models that appeal to commodity shippers and energy customers with long-term service commitments.
-
Digital and service differentiation. Fleet telematics, predictive maintenance and contract flexibility are moving from ‘nice-to-have’ to table stakes. Operators that package hardware with analytics-driven uptime guarantees and end-to-end logistics services command pricing premiums and deeper, stickier customer relationships.
Regulatory and policy considerations
Policy developments over 2024–2026 materially influence strategic choices. Notably, content‑origin limitations tied to new freight car safety rules impose staged percentage caps on non‑domestic content for cars entering the general railroad system, with tighter thresholds coming into force in later compliance windows. Parallel transparency and competition reviews in European and UK rolling stock markets reinforce the need for clear contractual terms and monitored vertical arrangements.
For executive teams this means three immediate imperatives: (1) build procurement scenarios that reflect tightening compliance windows, (2) prioritize supplier diversity and traceability in the bill of materials, and (3) engage early with regulators to shape implementation guidance and avoid disruptive mid-contract compliance shocks.
Competitive landscape — what to watch
The sector hosts a mix of global lessors, regionally-focused operators and vertically integrated suppliers. A selection of leading firms and recent strategic movements signals where competitive intensity is highest and where partnership opportunities lie:
-
GATX Corporation (Chicago). A premier lessor with broad tank and freight railcar capabilities and deep full‑service maintenance operations in North America. Recent fleet acquisitions have significantly enhanced scale and service footprint.
-
TrinityRail (Dallas). An integrated leasing platform combining a large leased fleet with manufacturing and logistics services — an important model for operators seeking turnkey supply and lifecycle support.
-
VTG Aktiengesellschaft (Hamburg). Europe’s leading private freight wagon lessor with a strong emphasis on multimodal logistics and digital solutions — relevant for cross‑border rail freight strategies.
-
Beacon Rail Leasing (UK) and RAILPOOL (Munich). Full‑service providers active across locomotive and wagon leasing with tailored operating packages that emphasize flexibility and maintenance integration.
-
EUROWAGON (Warsaw). A pan‑European independent lessor focused on modern freight wagons and intermodal services, highlighting the competitive role of agile, regionally deep players.
Two headline developments to factor into competitive positioning:
-
(June 2026) TrinityRail Global’s strategic stake acquisition in an India‑focused railcar leasing platform signals accelerated globalization of the leasing model into high‑growth markets via integrated manufacturing and financing partnerships.
-
(January 2026) A significant portfolio acquisition by a leading North American lessor nearly doubled a major lease fleet, underscoring the role of scale‑driven portfolio plays in capturing network effects and lowering per‑unit maintenance costs.
What the PW Consulting report contains — practical deliverables
Our full study is designed as a playbook for executives, investors and policy teams. It contains:
- Granular historical analysis (2020–2025) and a transparent, model‑backed 2026–2032 forecast calibrated to alternate macroeconomic and regulatory scenarios.
- A competitive intelligence module with vendor profiles, capability maps and scenario-based threat assessments for dominant and emerging players.
- Actionable procurement and contract templates that address compliance clauses, residual value protections and maintenance service level agreements.
- Fleet optimization tools: TCO models, lease-vs-buy matrices, utilization-stress testing and capex/opex impact simulators tailored to railcar types and contract tenors.
- Regulatory impact assessment with implementation pathways for content‑origin rules, transparency orders and cross‑jurisdictional rolling stock governance.
- Investment decision frameworks for private equity and infrastructure investors, including exit-path stress tests and partnership valuation heuristics.
- Digital transformation roadmap: telematics KPIs, maintenance‑as‑a‑service design and supplier integration playbooks.
We deliberately present decision-ready templates rather than generic recommendations; each is accompanied by ready-to-run assumptions and sensitivity ranges so teams can model outcomes without rebuilding from scratch.
Strategic implications and prioritized actions for 2026
-
For lessors: Accelerate investments in compliance-traceability and digital maintenance capabilities. Hedged fleet acquisition, using staged purchases or earn‑outs linked to regulatory compliance milestones, reduces balance-sheet exposure.
-
For OEMs and manufacturers: Reorient supply chains to certify compliant subassemblies and diversify sourcing. Consider JV models with leasing firms to secure long-term demand and smooth production planning.
-
For shippers and logistics operators: Reassess procurement strategies to price in availability risk and maintenance guarantees. Leasing offers a rapid route to compliance while preserving capital for core logistics investments.
-
For investors: Prioritize platforms that combine fleet scale, maintenance capability and financing flexibility. Due diligence should include scenario runs reflecting the staged regulatory content caps and a two‑track exit plan (sale to strategic vs. portfolio monetization via securitization).
-
For regulators and policymakers: Provide clear, forward‑looking guidance on compliance timelines and accepted traceability standards to avoid market fragmentation and unintended supply shocks.
How to use this briefing and the full report
Consider this briefing a strategic lens: it summarizes the macro trajectory, competition, regulatory inflection points and practical levers you can deploy in 2026. The full PW Consulting report converts each theme into executable outputs — model files, contract clauses, vendor scorecards and scenario dashboards — that project teams can operationalize immediately.
If your 2026 priorities include fleet expansion, strategic partnerships in emerging markets, or stress‑testing portfolios for regulatory change, our report is structured to shorten the time from insight to execution.
Next steps
Accessing the detailed models, brokered supplier negotiations playbook and downloadable procurement templates requires the full report. PW Consulting can also run a bespoke 48–72 hour rapid assessment workshop to apply the findings to your specific portfolio and risk tolerance — yielding a prioritized action plan and implementation roadmap.
For executives who must make market entry, partnership, or capital allocation decisions in 2026, this is not a forecast to read; it is a toolkit to act. Engage PW Consulting to convert the projected 5.5% CAGR trajectory and the market’s structural dynamics into concrete, near‑term competitive advantage.
For detailed analysis of this topic, please visit the official page: Railcar Leasing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com