

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: SOI Market Set for 13.5% CAGR (2026–2032)

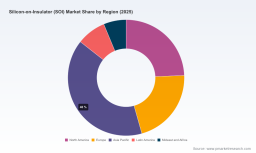
Silicon-on-Insulator (SOI) Market: Strategic Outlook for 2026 Decision‑Makers
Executive summary
The Silicon-on-Insulator (SOI) market is entering a second phase of industrialization that will determine supplier hierarchies, regional resilience, and product roadmaps through the end of the decade. Our analysis shows the market expanding from an estimated USD 0.85 billion in 2020 to USD 1.6 billion in 2025, with a continuation of strong momentum: the SOI ecosystem is forecast to reach roughly USD 3.85 billion by 2032 at a compound annual growth rate (CAGR) of approximately 13.5% over the 2026–2032 period. For executives planning capex, supply agreements, or ecosystem plays in 2026, those headline figures are more than numbers — they are the boundary conditions that should shape your sourcing cadence, inventory strategies, and technology investments.
Silicon-on-Insulator (SOI) Market
Why SOI matters now
SOI is no longer a niche enabling technology; its material advantages — improved RF performance, lower parasitic capacitance, better thermal isolation, and power efficiency — have become central to differentiated solutions across automotive, 5G/telecom, and high-performance consumer devices. These performance gains translate directly into system-level cost and performance benefits for customers who can justify the wafer-premium with higher ASPs or faster time-to-market. That dynamic explains the rapid capacity additions and strategic partnerships observed in the last 24 months.
Silicon-on-Insulator (SOI) Market
Interpreting the growth curve: opportunity and caution
The historic expansion from 2020 through 2025 and the forecast trajectory through 2032 imply a structural market expansion rather than a short-lived spike. Practically, a 13.5% CAGR underpins three strategic realities for 2026 decision-making:
Silicon-on-Insulator (SOI) Market
- Demand predictability is improving, which supports multi-year supply agreements and makes targeted capacity investments defensible — but only if they are aligned with realistic design win timelines and customer qualification cycles.
- Market scale will remain moderate in absolute terms through 2026–2028; the economics of wafer fabs and equipment imply winners will be those who combine capacity scale with process specialization (e.g., RF-SOI, FD-SOI variants), not simply those who expand indiscriminately.
- Mid-term upside concentrated in specific end-markets means product roadmaps must be calibrated to the actual adoption curves of adjacent systems (automotive ADAS electrification, 5G infrastructure refresh, and compact high-performance consumer radios).
Market dynamics and tail risks
Three macro forces will disproportionately influence outcomes in 2026:
- Public policy and investment. Subsidy-driven capacity builds — notably under programs like the CHIPS Act — are reshaping lead-time risk and regional supply security. Since 2020, governments and industry have announced scores of semiconductor projects that collectively represent very large capital commitments. For SOI users, this reduces a key procurement risk but introduces new competitive dynamics as domestic supply options grow.
- Geopolitical friction and trade measures. Tariffs and export controls are elevating the total landed cost of substrates and equipment, driving near-term localization strategies and a reassessment of multi-sourcing versus single-source models.
- Technology commoditization vs differentiation. As 300 mm SOI production scales, certain SOI variants risk commoditization unless paired with process IP, ecosystem lock-ins (foundry design platforms), or bespoke substrate properties. Suppliers investing in both capacity and technology roadmaps will sustain margins; others may see price-led commoditization pressures.
Competitive landscape: players to watch
The SOI market displays measurable concentration: the top three suppliers account for a majority share of accessible capacity, and the top five consolidate an even larger proportion. This concentration reinforces the strategic importance of aligning with the right supplier type — global leaders, regional specialists, foundry partners, or niche innovators — depending on your strategic intent (secure supply vs. best-in-class performance).
Key strategic profiles we profile in the full study include:
- Soitec (Bernin, France): A technology leader with Smart Cut® heritage. Recent manufacturing investments and supply agreements position it to serve automotive and RF applications with a focus on higher-value SOI variants. Its 2026 facility expansion notably increases 300 mm capacity aimed at automotive and RF customers.
- GlobalWafers (Taiwan): Expanding volume capacity across 200 mm and introducing 300 mm capabilities, aiming to capture both established RF-SOI demand and emergent power-SOI needs. Their growth is playing into regional supply diversification strategies.
- Shin‑Etsu Chemical & SUMCO (Japan): These incumbents bring mass-production scale, strong quality control, and established 300 mm platforms, making them natural partners for customers prioritizing throughput and long-term reliability.
- Shanghai Simgui Technology & other regional players: Offering complementary process technologies (SIMOX, bonding variants) and serving local foundry ecosystems, these suppliers are critical for regional resilience strategies in Asia.
- Okmetic, Silicon Valley Microelectronics, Tower Semiconductor: Specialized players and foundry partners provide differentiated offerings — bonded SOI for MEMS, bespoke thin/thick SOI variants, and integrated RF-SOI foundry platforms — enabling system houses and fabless players to accelerate product qualification.
Recent developments that affect 2026 choices
- Capacity expansion announcements signal a short-to-medium-term easing of lead-time pressure for selected SOI variants, but this relief is uneven across wafer sizes and process nodes — careful qualification timelines are still needed.
- Foundry-supplier supply agreements and platform integrations increasingly determine which suppliers secure long-run design wins; firms that can pair substrate supply with foundry support command strategic premium.
- Policy-driven investments have reduced some single‑source vulnerabilities in target markets, but they also increase the speed at which new entrants can scale — accelerating competitive intensity for specialized SOI niches.
What this means for corporate strategy in 2026
Executives should treat SOI strategy not as a single procurement decision but as a multi-dimensional program spanning technology, supply, and commercial partnerships. Practical recommendations for 2026:
- Embed substrate strategy into product roadmaps. Synchronize wafer qualification gates with system-level milestones (design freeze, tape-out, and qualification) to avoid last-minute supplier substitutions that can delay launches.
- Adopt a tiered supply model. For critical product lines (e.g., automotive ADAS, flagship RF modules), secure primary long-term supply agreements with capacity commitments plus one or two qualified secondary suppliers to mitigate single‑site risk.
- Invest selectively in co-development. Prioritize co-investment with suppliers that offer technical roadmaps aligned to your feature roadmap rather than price-only propositions — technical differentiation will protect margin and accelerate time-to-market.
- Use policy levers. Where feasible, leverage regional funding and incentive programs to accelerate local qualification or secure pricing stability, particularly for products with regional certification constraints.
- Prepare for consolidation and vertical integration opportunities. Given the market concentration and specialized pockets of capacity, 2026 is an opportunistic window for acquisitive strategies or strategic joint ventures that lock wafer supply and process IP.
What our full report delivers (practical contents)
We designed this study for decision-makers who need actionable outputs, not academic summaries. The full report—which this piece intentionally withholds in selected granular areas to preserve its strategic intelligence—includes:
- Supply‑side capacity maps and staged build-out timelines for 200 mm and 300 mm platforms.
- Technology roadmaps correlating SOI variants to application adoption windows (RF, FD‑SOI, thin-film, power, MEMS) with recommended qualification lead times.
- Supplier scorecards covering techno-commercial strengths, expansion plans, risk factors, and partnership fit analyses for leading and regional players.
- Scenario-based demand models and sensitivity analyses that translate macro growth into SKU-level wafer requirements under multiple adoption and production yield scenarios.
- Procurement playbooks: contract templates, buffer stock calculators, and negotiation levers tailored to SOI’s capital- and lead-time characteristics.
- M&A and partnership target shortlists built from capability gaps, strategic fit indices, and integration complexity scores.
- Risk heatmaps incorporating geopolitical, raw-material, and equipment‑supply vectors, with mitigation pathways and cost‑to‑mitigate estimates.
- Workshops and governance templates to operationalize SOI strategy across R&D, supply chain, and corporate development functions.
How to use this intelligence in 90 days
To convert insight into impact, we recommend a pragmatic 90-day plan for teams entering or scaling in the SOI ecosystem:
- Week 1–3: Rapid internal alignment — map product roadmaps to wafer requirements and flag single‑point supplier exposures.
- Week 4–8: Supplier engagement sprint — initiate qualification dialogues with two prioritized suppliers, request capacity commitments, and align timelines. Use our supplier scorecards to structure the conversations.
- Week 9–12: Finalize procurement and co‑development strategy — execute a supply agreement for critical lines, secure technical support windows, and open discussions for co-engineering where differentiation is material to your product value proposition.
Closing: why the timing matters
2026 is a hinge year. Market growth provides both room for new entrants and risk of consolidation — capital intensity, lead-time characteristics, and an evolving policy landscape mean that the decisions you take in 2026 will set your relative position across the remainder of the decade. Our market sizing — from USD 0.85 billion in 2020 to an estimated USD 1.6 billion in 2025 and a projected climb toward USD 3.85 billion by 2032 at ~13.5% CAGR — frames the opportunity. But translating that headline expansion into commercial returns requires tactical playbooks, robust supplier partnerships, and a clear view on which SOI variants underpin your differentiators.
For teams preparing 2026 budgets, M&A pipelines, or product qualification plans, the full PW Consulting SOI Market report provides the practical templates, supplier assessments, and scenario models needed to move from aspiration to execution. This briefing intentionally omits granular segmentation tables and SKU-level figures to preserve the actionable intelligence within the full report; clients who need the full dataset, model access, and customized briefings can request the complete study via our research portal.
For detailed analysis of this topic, please visit the official page: Silicon-on-Insulator (SOI) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com