

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Sandals market to reach USD 49,369M by 2032 at 4.52% CAGR — PW Consulting

Sandals Market 2026 Strategic Preview: What Leaders Must Know to Win in the Coming Cycle
As organizations plan 2026 budgets and three- to five-year strategies, a clear-eyed reading of the sandals market is indispensable. PW Consulting’s latest Sandals Market study—based on a 2025 base year and projecting through 2032—unlocks the commercial geometry underlying consumer footwear choices, channel dynamics, product innovation vectors, and competitive positioning. This preview outlines the study’s strategic value for corporate decision-makers while preserving the proprietary granularity that sits behind our full analysis.
Sandals Market
Why the sandals market matters to enterprise strategy in 2026
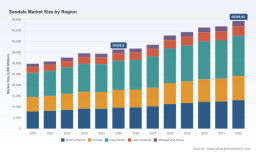
At first glance, sandals may read as a niche category. In practice, it is a high-leverage segment that amplifies trends in casualization, seasonal purchasing, sustainability sourcing, and direct-to-consumer retail models. The category’s macro trajectory is instructive: the market expanded notably through the early 2020s and stood at approximately USD 36.3 billion in 2025. Our forecast baseline, using the study’s rigorous assumptions, projects a steady compound annual growth rate of about 4.52% across the 2026–2032 horizon, taking the market toward the USD 49–50 billion neighborhood by 2032 under the base-case path.
Sandals Market
That growth profile creates specific windows of opportunity. It is large enough to support multi-million-dollar innovation programs, yet fragmented enough that nimble competitors can materially improve their market share through targeted moves—if they act with insight and speed.
Sandals Market
What the PW Consulting study delivers (practical, operational, non-numeric)
- Market architecture and demand drivers: a layered analysis linking macro consumption trends, seasonality, and silhouette-level momentum to consumer cohorts and purchase triggers.
- Commercial playbooks: tactical modules for assortment optimization, pricing ladders, promotional cadence, and inventory profiling tuned to high-turn versus long-tail SKUs.
- Channel and route-to-market frameworks: decision tools for balancing wholesale, e-commerce, DTC, and marketplace strategies, including a financial sensitivity model that quantifies margin and working-capital trade-offs.
- Product and innovation blueprints: prioritization frameworks for material substitution (cost, carbon, compliance), modularity in design, and certification/labelling that unlock institutional and safety-related accounts.
- Supplier and operations diagnostics: checklists and KPIs for supplier resilience, lead-time compression, and nearshoring trade-offs—vital for companies balancing cost and speed.
- Scenario-based strategic planning: three actionable scenarios (base, upside, downside) with trigger indicators and contingency playbooks that translate forecast variance into concrete business actions.
Data-driven insight without the data dump
The study’s value lies in marrying high-fidelity market totals and growth rates with executable guidance. We deliberately avoid turning this preview into a spreadsheet of line-item shares: the core intelligence—from regional and sub-segment volumes to channel-specific unit economics—is reserved for the full report and bespoke advisory engagements. That said, corporate leaders can act on several robust, non-sensitive insights derived from the data:
- Momentum pockets are clearly identifiable by silhouette and channel, with slides and flip-flops showing consistent dollar-and-unit growth in recent quarters according to independent retail trackers. Peripheral silhouettes (mules, clogs, ballerinas) also contributed to category uplift, indicating consumers are broadening the notion of "sandals" into adjacent casual formats.
- The category’s fragmentation—evidenced by low combined shares among the largest firms—creates room for differentiated plays: premiumization, safety-focused niches, or private-label scale in retail partnerships.
- Seasonality remains a planning constraint. Companies that align inventory velocity with promotional windows and that use flexible sourcing frameworks materially reduce markdown risk while improving return on invested working capital.
Competitive landscape: what to watch (profiles and implications)
The sandals market exhibits a dual nature—consumer-facing lifestyle brands coexist with specialized industrial and safety footwear firms. Two firms typifying the latter approach are WorkWay Safety and Hillson Safety Shoes. Both are headquartered in China and have focused product portfolios centered on safety sandals and steel-toe or workshop-ready variants tailored to automotive and manufacturing customers. Their strategic posture offers several lessons for market participants:
- Vertical specialization can be a defensible moat. Safety certifications, industry-spec attachments, and trade-channel relationships create switching costs in non-consumer segments.
- Cross-over potential exists. Industrial-grade technologies (durability compounds, anti-slip outsoles) are increasingly migrating into lifestyle products—creating premiumization opportunities for firms that can translate robust specs into consumer-friendly narratives.
- Market-entry barriers for safety segments are non-trivial but surmountable: firms that invest in certification, field trials, and channel education can command better pricing and more stable reorder cycles.
PW Consulting’s report maps competitive moves—including product launches, partnership signals, and channel expansions—and provides playbooks for responding to emergent threats or partnering with specialist manufacturers to accelerate time-to-market.
Strategic imperatives for 2026 decision-makers
- Prioritize portfolio clarity. Separate high-velocity seasonal SKUs from long-tail innovation bets in budgeting and replenishment models. Use SKU-level lifetime value and contribution-margin metrics to guide SKU rationalization.
- Embed flexibility into sourcing. Build capacity buffers and multi-sourcing arrangements that can be dialed up during peak selling windows to minimize stockouts without bloating inventory.
- Make digital commerce a first-class channel. Consumers are increasingly using rich media, fit guides, and social proof to purchase sandals; brands that master conversion funnels will capture outsized share of online growth.
- Monetize technical differentiation. Safety and durability claims can support higher ASPs in both industrial and premium lifestyle niches—if validated by third-party testing and clear storytelling.
- Invest in sustainable materials where it moves the needle. Not all sustainability investments yield equal returns; target initiatives that reduce cost volatility (material substitution) and enhance brand preference (recyclability, traceability).
Risk vectors and scenario triggers
Key risks include sudden commodity swings in polymer and rubber inputs, climate-driven production disruptions in sourcing geographies, and rapid shifts in consumer preferences away from casual footwear during macroeconomic contraction. We embed these risks into scenario templates with explicit trigger indicators (e.g., a sustained six-month input cost delta, a 10% drop in discretionary spending in priority geographies, or a regulatory change impacting safety certification). Each scenario is paired with a playbook: reprice, hedge, regional pivot, or accelerate product rationalization.
KPIs and monitoring cadence
- Top-line and mix: monthly sell-through by silhouette and channel; SKU-level margin contribution.
- Operational: supplier lead time, on-time-in-full (OTIF), and inventory days of supply (DOS) by cadence.
- Go-to-market: online conversion rate, repeat-purchase rate, and promotional elasticity.
- Brand/innovation: NPS for new silhouettes, conversion lift from technical claims, and partner certification completion rates.
How to use the full PW Consulting study
The preview above is structured to give strategy teams the directional clarity they need for 2026 planning—without disclosing the level of segmentation and company-level detail that underpins executable tactics. The full study supplies:
- Granular regional and channel tables, unit economics, and SKU-level performance histories from 2020–2025.
- Forecasts across multiple segmentation axes with sensitivity runs and probability-weighted outcomes for each scenario.
- Competitive dossiers with product roadmaps, pricing ladders, and suggested countermeasures mapped to each identified competitor type.
- Implementation templates for merchandising, sourcing, and digital marketing designed for rapid deployment.
Executives preparing investment proposals, product roadmaps, or channel realignments will find the full dataset and playbooks immediately actionable. For teams that want tailored guidance, PW Consulting offers scenario workshops that translate the forecast and playbooks into a prioritized project list with estimated ROI and implementation timelines.
Final thoughts: Why act now
The sandals category is neither an archipelago of isolated SKUs nor a utility market dominated by three titans. Its intermediate scale and mid-single-digit growth rate make it an ideal arena for companies to test product innovations, refine omni-channel tactics, and develop capabilities that scale across other footwear categories. The next 12–18 months will reward firms that combine disciplined inventory management with targeted innovation and crisp channel execution.
To access the complete findings, tables, and competitive appendices that inform the strategic levers summarized here, visit our report landing page or contact PW Consulting for a briefing. The full intelligence package is designed to convert the market’s projected 4.52% CAGR and the identified demand signals into a concrete, executable advantage for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Sandals Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com