

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Document Scanner Market to Hit USD 6,680 Million by 2032 at 5.35% CAGR

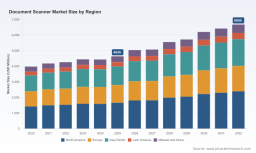
Document Scanner Market 2026: Strategic Imperatives for Decision Makers
PW Consulting’s latest Document Scanner Market study, anchored on a 2025 base year and covering historical performance from 2020–2025 with a forward-looking horizon to 2032, is designed as a decision-grade briefing for executives making capital, procurement, and M&A choices in 2026. The global market is forecast to continue a steady expansion trajectory—we model a compound annual growth rate of 5.35% from the base year, with market value rising meaningfully through the forecast window. That steady growth, combined with shifting regulatory requirements and accelerating adoption of AI-enabled capture, creates a narrow window in 2026 for choices that will materially affect competitiveness over the next investment cycle.
Document Scanner Market
Why this study matters to 2026 decisions
-
Actionable foresight for procurement: Organizations replacing fleets or launching large-scale digitization projects need a market-aware procurement playbook that balances capex, serviceability, and compliance risk. Our study translates growth trends into procurement timing and total cost of ownership (TCO) levers.
Document Scanner Market -
Vendor strategy and partnerships: Vendors and channel partners must recalibrate product roadmaps (device + software) to capture outsized share in growth pockets—especially where AI-enabled capture and cloud-native workflows displace legacy hardware-centric value propositions.
Document Scanner Market -
Investor signalling: Private equity and strategic buyers can identify consolidation targets and software-centric adjacencies where margin expansion and recurring revenue are achievable within a three-year hold.
Market dynamics shaping 2026 choices
The market’s steady mid-single-digit CAGR masks several important inflection points that require careful reading. First, automation and AI are shifting value from raw scanning throughput to capture intelligence—OCR accuracy, document classification, and metadata extraction now determine the marginal value of a scanner deployment. Second, compliance and data sovereignty concerns are rising as governments and large enterprises tighten rules around bulk data transfers and retention practices. Third, labor remains the dominant operational cost in high-volume scanning environments; at scale, marginal improvements in workflow automation directly translate to unit economics improvements.
Illustrative developments underscore these dynamics. Vendors are shipping TAA-compliant models and expanded flatbed options to serve government and regulated verticals, signaling a product-market response to procurement requirements. At the software layer, headless SDKs for server-side capture have been refreshed to support containerized, cloud-native deployments—lowering integration friction for enterprise capture at scale. Conversely, the operational risks of large archival projects are visible in recent government workstreams: a high-profile archival scanning program was discontinued due to low volumes and quality issues, highlighting that scale alone does not guarantee success without robust QA and metadata strategies.
Regulatory and risk considerations
-
Data protection and privacy: GDPR-style obligations continue to require technical and organizational measures (encryption, access control, provenance of metadata) for personal-data processing in scanning workflows. Buyers must require demonstrable controls as part of vendor evaluations.
-
Cross-border data movement: New national-level programs and executive directives impose licensing or restrictions on bulk transfers to certain jurisdictions—affecting how vendors design cloud sync and managed-hosting services.
-
Procurement compliance: TAA-status and government-specific certifications have moved from “nice-to-have” to procurement gating criteria in many public sector tenders.
Competitive landscape: how incumbent and emerging suppliers are positioned
The competitive map includes long-standing device OEMs, software-first challengers, and specialist integrators. Incumbent hardware players continue to leverage enterprise-grade throughput, feed mechanisms, and long-term service networks; at the same time, nimble vendors differentiate through portability, software bundles, and AI enhancements.
-
Fujitsu: Focuses on high-speed sheetfed solutions and enterprise workflow integration through a well-established PaperStream ecosystem—positioned for large workflows where reliability and integration to document management systems are prioritized.
-
Canon: Offers a broad imageFORMULA line, including high-capacity duplex and flatbed models optimized for multi-page office and departmental capture—appealing to organizations that value comprehensive device portfolios and global service coverage.
-
HP: Targets mobile and small-office capture with portable and desktop scanners packaged with WorkScan software—suited to hybrid work environments and distributed capture use cases.
-
Epson: Has advanced its desktop/flatbed offerings and introduced TAA-compliant models aimed at federal procurement; recent launches expand choices for agencies and regulated enterprises.
-
Brother: Competes on compact, high-speed desktop scanners with strong channel presence for SMEs and office environments.
-
Plustek: Differentiates via wide-format and professional scanners coupled with AI-enhanced capabilities—targeting niche verticals and specialist capture tasks.
-
Xerox: Leverages integration with enterprise document-management systems through targeted product lines—appealing to long-term document-centric customers.
-
Visioneer: Focuses on workflow simplicity with OneTouch and network-friendly models for distributed capture, often competing on ease-of-deployment for SMBs and departmental buyers.
Recent product and software moves are instructive: Epson’s mid-2025 product rollouts include TAA-compliant desktop scanners and expanded flatbed capacities, explicitly targeting federal and regulated markets. In early 2026, core SDK suppliers released server-focused SDK updates enabling headless deployments, lowering barriers for enterprise automation projects that prioritize unattended, high-volume processing.
What the PW Consulting report delivers (practical contents)
-
Market sizing and forecast model (2020–2032) with scenario analysis and sensitivity testing.
-
Vendor benchmarking and product-level capability matrices focused on throughput, OCR performance, integration points, and procurement compliance.
-
Procurement playbook and TCO templates that convert throughput, labor, and software costs into per-image economics for RFPs.
-
Regulatory and compliance matrix mapping data protection, export controls, and procurement rules to product and deployment choices.
-
Operational readiness checklist: QA protocols, metadata schemas, and acceptance tests informed by archival program failures.
-
Go-to-market and M&A playbooks for vendors and investors highlighting high-opportunity verticals and partnership archetypes.
-
Case studies and vendor due-diligence templates suitable for enterprise PMOs and private equity teams.
Strategic recommendations for 2026
-
For enterprise buyers: Prioritize scanned-output quality and downstream automation capability over headline throughput numbers. Insist on service-level KPIs for image quality, OCR accuracy, and metadata completeness in contracts. Pilot integrations with a representative document mix before committing to fleet refresh.
-
For public-sector procurers: Require demonstrable compliance (TAA where relevant), explicit data transfer controls, and independent QA protocols. Avoid awarding large archival contracts without staged acceptance criteria tied to objective quality thresholds.
-
For vendors: Invest in capture intelligence (classification, zone OCR, ML-based error detection), harden SDKs for headless/cloud deployments, and expand managed-services offers to monetize recurring revenue. TAA and similar procurement certifications should be treated as strategic investments in key markets.
-
For investors: Target software-enabled services and players with strong channel relationships. Look for targets that combine device economics with SaaS capture or analytics layers—those are the assets most likely to deliver multiple expansion in the near term.
How to use this study
Consider this document a strategic orientation for 2026. The full PW Consulting study contains the granular segmentation, regional and application modelling, and quantitative vendor scorecards that purchasing teams, product strategists, and investors will need to operationalize the recommendations above. If you are preparing an RFP, sizing a deployment, or evaluating acquisition targets this year, the detailed appendices and downloadable TCO models included in the full report will shorten your runway and reduce execution risk.
PW Consulting’s analysis combines market-data rigor with practitioner-oriented tools to bridge strategy and execution: we show where the opportunities are and, critically, what operational changes are required to capture them. For organizations that must decide in 2026 how much to commit to device refresh, where to embed AI capture, and how to structure contracts to reduce regulatory and operational risk, the right intelligence—timely, tested, and prescriptive—will be the difference between a marginal and a transformative program.
To access the full segmentation, vendor scorecards, and downloadable procurement templates, please refer to the PW Consulting report repository. Our team is prepared to walk through the models and tailor them to your specific procurement or investment scenario.
For detailed analysis of this topic, please visit the official page: Document Scanner Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com