

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Hot Water Storage Tank Market to Reach USD 5,510M in 2025, 4.71% CAGR (2026–32)

Hot Water Storage Tank Market — Strategic Briefing for 2026 Decision-Makers
Executive summary
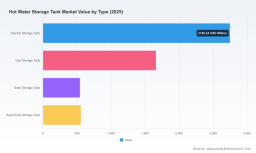
As companies position for the next strategic cycle, the hot water storage tank market is transitioning from a component-driven commodity to a systems-level battleground where regulation, materials science, and distributed-energy integration determine long-term winners. Our latest PW Consulting study (base year 2025) synthesizes a seven-year outlook (2026–2032) and quantifies the market’s trajectory: after recovering from short-term volatility, the global market was approximately USD 5,510 Million in 2025 and is projected to expand at a compound annual growth rate (CAGR) of about 4.71% through 2032, reaching roughly USD 7,565 Million under the baseline scenario.
Hot Water Storage Tank Market
This briefing highlights the study’s strategic value for corporate executives, product teams, and commercial leaders planning resource allocation, M&A, and innovation investments in 2026. It is deliberately a “trailer”: we share frameworks, directional insights and practical recommendations to inform near-term choices while preserving proprietary segment detail for subscribers to the full report.
Hot Water Storage Tank Market
Why this research matters for 2026 decisions
- Regulatory inflection point: New efficiency and standby-loss requirements are accelerating design change and re-certification needs—making compliance a near-term capital and go-to-market issue for manufacturers and specifiers.
- Material- and warranty-driven differentiation: Advances in stainless-steel linings and alternative corrosion strategies are shifting cost structures, aftersales profiles and total cost of ownership (TCO) conversations with customers.
- Energy transition convergence: Storage tanks are no longer passive appendages. They are strategic enablers for heat-pump, solar-thermal, and hybrid electrification architectures that facility managers and OEMs will prioritize over the next procurement cycle.
Market outlook — what the numbers tell you
The market’s headline metrics matter because they frame investment scale, margin opportunities and M&A rationale. From a 2020 baseline through 2025 the market expanded, with a modest downturn visible in 2024 followed by recovery into 2025. Our baseline forecasts show steady growth at ~4.7% CAGR for 2026–2032, with absolute market size moving from just under USD 5.7 Billion in 2026 toward the USD 7.6 Billion range by 2032 under current policy and technology assumptions.
Hot Water Storage Tank Market
Concentration metrics indicate a market where a limited set of incumbents maintain meaningful shares (CR3 ~45.5%; CR5 ~65.0%). That creates a marketplace where scale confers procurement and distribution advantages, yet the residual share is large enough to reward nimble specialists, regional champions, and vertically integrated systems players.
Key industry dynamics shaping competitive advantage
- Regulation and certification: Emerging regulatory requirements (including tightened thermal-efficiency and standby-loss standards) and mandatory third-party certifications are increasing cost of compliance. Tanks above threshold capacities face ASME HLW and potable-water standards such as NSF 61, while plumbing codes demand safety devices and formal approval—delays in product certification can materially delay market access.
- Material choices and TCO: Duplex stainless linings (e.g., AquaPLEX-type solutions) and glass- or cement-lining practices influence warranty terms and lifecycle economics. These choices also alter manufacturing CAPEX, unit cost and aftermarket liabilities—key inputs to pricing strategy.
- System integration and electrification: Heat-pump and solar-integrated storage tanks are becoming strategic product lines. As electric heating electrifies building heat loads and on-site renewables proliferate, storage tanks that optimize thermal stratification, low standby losses and integration interfaces will capture premium positioning.
- Channel and service value: Warranty structures, service networks and aftermarket parts availability have become differentiators, especially for commercial buyers with uptime requirements. Extended service agreements and faster lead times are premium features buyers will pay for.
Competitive landscape — what leading suppliers are doing
The market features a mix of large OEMs and specialized tank manufacturers. Leading U.S.-based suppliers (including heritage water-heater OEMs and specialist ASME-certified tank makers) continue to invest in commercial portfolios and trade-show visibility to secure specification work for large projects. Recent vendor activity exemplifies tactical priorities:
- PVI Industries (Watts Water Technologies) showcased commercial water heaters and storage tank solutions at the major trade event cycle, underscoring trade-show-led demand capture and specification activity.
- Stiebel Eltron has both refreshed its small domestic storage portfolio and used industry trade platforms to highlight indirect solar and geothermal storage options—illustrating a product-development push into integrated, renewables-compatible solutions.
For incumbents, the playbook is clear: protect core channel relationships, accelerate certification where regulation is imminent, and bundle tanks into systems offers with controls and service contracts. For challengers, there are repeatable openings in niche certifiable ASME verticals, hybrid application packages and aftermarket service differentiation.
Actionable strategic priorities for 2026
- Product roadmap alignment: Prioritize development and certification of products that meet imminent thermal-efficiency and standby-loss limits. Fast-track reformulations that eliminate sacrificial anodes via stainless-lining or comparable corrosion strategies if warranty extension is a target.
- Go-to-market and channel optimization: Reassess distributor agreements and commercial-spec channels to ensure project specifiers are engaged early. For manufacturers selling direct to contractors or facilities teams, invest in technical sales enablement emphasizing TCO and integration with heat-pump/solar systems.
- Procurement and cost mitigation: Hedge raw-material exposure on alloys and coatings; evaluate supplier partnerships for high-grade linings and modular tank components to reduce lead times and enable faster certification cycles.
- Service & aftermarket economics: Build modular service plans and remote-monitoring offers. Warranty differentiation tied to certified lining technologies creates higher-margin recurring revenue and reduces end-user resistance to higher initial prices.
- M&A and alliances: Consider tuck-in acquisitions to secure certification stacks, distribution footprints or patented heat-exchange interfaces that accelerate system integration with electrified heating sources.
- Scenario planning and analytics: Run scenario models that stress-test regulatory tightening and rapid heat-pump adoption; maintain flexible capacity plans so you can scale production for opportunistic regional projects without over-committing CAPEX.
What the full PW Consulting report delivers
PW Consulting’s full study is engineered for executable decisions. Subscribers receive:
- Proprietary market-sizing and forecast models (2020–2032) with multiple scenarios and sensitivity analyses to test regulatory and commodity shocks.
- Competitive profiles and capability maps of leading vendors, including strategic positioning, product portfolios, and recent commercial moves.
- Regulatory impact assessment and a certification playbook (ASME HLW, NSF 61, relevant plumbing-code changes), with timelines and cost-to-certify estimates.
- Customer-segment archetypes and procurement evaluation frameworks for residential, commercial and industrial buyers.
- Supply-chain heatmaps highlighting critical material exposures (linings, insulation systems), supplier risk scores and near-term sourcing levers.
- Pricing benchmarks, margin pools, and go-to-market tactics including distributor vs. direct models, specification outreach and service bundling economics.
- Deal pipeline opportunities and diligence checklists for M&A, joint ventures and strategic partnerships, including integration playbooks.
- Implementation templates: product launch checklist, certification timeline tracker, and a 12–24 month commercial activation plan.
How to use this briefing in your 2026 planning
Use these insights to prioritize three immediate actions this quarter:
- Execute a rapid regulatory readiness audit: map which SKUs require recertification, estimate adjustment costs, and assign owners to reduce approval lag.
- Lock in material-supply arrangements for critical linings and insulating components; secure options or forward contracts where feasible to protect margins against alloy volatility.
- Pilot a bundled offering that pairs storage tanks with heat pumps or solar interfaces in one sales playbook—measure buyer willingness-to-pay and service-takeup rates over six months to inform rollout.
Final perspective — defend, extend, or specialize?
Given current market concentration and the pace of regulatory and technology shifts, incumbents should focus on defend-and-extend strategies: defend channel relationships and margins while extending system-level capabilities (controls, integration kits, certified linings). Fast followers and specialists can carve profitable positions by targeting certification-heavy verticals, offering superior TCO through advanced linings, or capturing aftermarket service revenue. Across the board, readiness for regulatory changes and the ability to integrate with electrified heating ecosystems will determine which players convert near-term investments into durable market advantage.
Next steps
This executive briefing outlines the strategic imperatives and operational levers that matter for 2026. For the proprietary segment details, regional breakouts, SKU-level implications and playbook templates, access the complete PW Consulting Hot Water Storage Tank Market report and model pack. Our team is available to support tailored strategy workshops, M&A diligence or implementation sprints informed by the full dataset and scenario models.
For detailed analysis of this topic, please visit the official page: Hot Water Storage Tank Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com