

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Human Rabies Immunoglobulin (IM) Market to Reach USD 527.5M in 2025, 5.5% CAGR

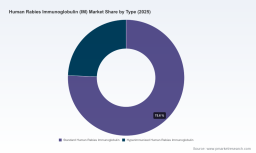
Human Rabies Immunoglobulin (IM) Market — Strategic Outlook for 2026 Decision-Making
As health systems and biopharmaceutical organizations set budgets and strategic priorities for 2026, Human Rabies Immunoglobulin (IM) represents a small but strategically important specialty immunoglobulin market. This briefing synthesizes the high-level market trajectory, the competitive and regulatory inflection points that will matter to executive teams, and the pragmatic intelligence our full PW Consulting study delivers — while intentionally omitting the granular segment-level tables and regional splits that are reserved for the complete report.
Human Rabies Immunoglobulin (IM) Market
Market snapshot: scale, momentum, and trajectory
By PW Consulting’s base-year assessment for 2025, the global Human Rabies Immunoglobulin (IM) market stands in the mid-hundreds of USD Million and has expanded steadily from 2020 through 2025. Our forecast models project continued expansion through the 2026–2032 horizon driven by sustained post-exposure prophylaxis demand, formulation innovation, and selective geographic growth. The modeled compound annual growth rate (CAGR) for the forecast period is 5.5%, yielding a market that meaningfully grows in absolute terms by the end of the forecast window.
Human Rabies Immunoglobulin (IM) Market
Two takeaways flow directly from these macro data points: first, this is a market with predictable, demand-led growth rather than explosive disruption; second, modest CAGR and concentrated supply dynamics create circumstances where tactical moves — securing plasma supply, optimizing dose volumes, or winning procurement tenders — can disproportionately affect commercial outcomes.
Human Rabies Immunoglobulin (IM) Market
Why the 2026 decision calendar must account for this market
-
Operational resilience and procurement: With steady demand and limited number of established producers, procurement teams need scenario-ready supply plans going into 2026 (multiple-supplier frameworks, strategic inventory buffers, and contract flexibility to manage episodic spikes in demand following exposure incidents).
-
Product positioning and formulation strategy: High-potency, lower-volume formulations shift cost-to-deliver and injection logistics; product teams should evaluate dose-volume advantages (and corresponding clinical adoption barriers) when allocating R&D and commercialization budgets.
-
Regulatory and testing readiness: New laboratory capabilities and regulatory approvals for rabies-neutralization testing affect product validation timelines and market access. Organizations must anticipate evolving testing and surveillance standards when planning registration pathways.
-
Investor and M&A prioritization: A market with moderate CAGR but high concentration among core players creates attractive windows for bolt-on acquisitions that deliver distribution scale, plasma-sourcing capability, or fill specific formulation niches.
Core dynamics shaping near-term strategic choices
-
Concentration and competitive structure — a compact field: The market is materially concentrated among a small number of established manufacturers. Our concentration metrics indicate that the leading three and five suppliers together command a significant majority of industry revenues, creating entry barriers but also predictable competitive behavior. For acquirers and suppliers, this translates to clearer counterparty risk and defined targets for partnership or consolidation.
-
Formulation differentiation — potency matters: High-potency HRIG formulations enable clinicians to administer smaller injection volumes for a standardized IU/kg dose, which has real-world implications for outpatient administration, patient comfort, and per-dose logistics. Product teams should quantify how potency differences affect unit economics, cold-chain handling, and dosing protocols when setting 2026 commercialization priorities.
-
Supply-side biology — donor sourcing is strategic: Some HRIG products are derived from plasma of donors who are hyper-immunized with rabies vaccine. Securing reliable donor pools and ensuring compliance with plasma collection standards are strategic assets; they underpin manufacturing continuity and differentiate unit-cost structures.
-
Regulatory and diagnostic inflection points: Recent regulatory and testing milestones shift the market environment. For example, the FDA-approved in-house rabies virus neutralization testing laboratory announced by Kamada in mid-2026 introduces new validation capabilities that can accelerate product development and batch release for manufacturers that integrate advanced neutralization testing. Similarly, public-health guidance updates — such as interim recommendations to optimize HRIG use following exposure incidents — create short-term demand surges and longer-term shifts in usage patterns that companies must model.
-
Market stability vs episodic demand: Public-health authorities report that no HRIG shortage existed in the United States as of July 2025. That baseline stability means manufacturers and suppliers can prioritize efficiency and targeted capacity expansion rather than emergency-scale investment — but they must also design for episodic surges tied to exposure clusters or guidance changes.
-
Commercial traction and reimbursement signals: Company-level performance can identify pockets of commercial strength. For example, specific product franchises reached notable sales levels in 2025, signaling payer acceptance and established clinical uptake. Those revenue signals are critical when evaluating go-to-market investments or pricing strategies for adjacent product launches.
Competitive landscape — what the leading players tell us
The competitive map is anchored by a set of established manufacturers with distinct manufacturing approaches and global reach. Key examples include:
-
Sanofi Pasteur (Cambridge, MA, USA): A long-standing player with marketed HRIG formulations used for post-exposure prophylaxis. Their portfolio and global footprint provide pricing leverage and procurement relationships with health systems.
-
Grifols Therapeutics (Barcelona, Spain): Offers a high-potency HRIG formulation that reduces injection volume. This technical differentiation creates adoption advantages in settings where administration logistics and patient throughput matter.
-
Kedrion Biopharma (Rome, Italy), in partnership arrangements: Manufactures HRIG through donor programs focused on hyper-immunized plasma. Recent developments in the company ecosystem include regulatory and commercial moves that have materially advanced in-house testing and sales momentum.
For strategic leaders, the commercial implications are clear: alliances that secure plasma sourcing, investments in potency-enhancing processes, or capabilities in advanced neutralization testing are high-leverage moves. The market is not a winner-takes-all contest, but the concentrated structure rewards targeted capability builds and distribution relationships.
Report deliverables — what PW Consulting provides (practical and operational)
Our full Human Rabies Immunoglobulin (IM) market study is designed as an executive-to-operational playbook. Highlights include:
-
Base-year market sizing (2025) and year-by-year historical context (2020–2025), plus a transparent forecast model covering 2026–2032 with scenario variants keyed to supply interruptions, potency adoption, and policy shifts.
-
Commercialization roadmaps by market-access environment: reimbursement levers, hospital procurement behavior, and tender dynamics to shape pricing and contracting tactics.
-
Supplier scorecards and manufacturing-onboarding assessments that rate capacity, raw-material risk (donor programs), batch release cadence, and geographic distribution strength.
-
Regulatory and diagnostic intelligence: pathway maps for registration, batch-release testing expectations, and how emerging laboratory approvals influence time-to-market.
-
Operational playbooks for procurement and inventory: recommended contract structures, inventory buffers, and logistics plans to manage episodic demand surges while minimizing working capital drag.
-
Investment and M&A screener: a prioritized shortlist of target capabilities (plasma-sourcing, distribution networks, specialty formulation IP) and valuation sensitivities under several growth scenarios.
-
Risk matrix with mitigation plans for supply disruption, regulatory delays, and reputation incidents tied to exposure events or clinical outcomes.
Note: while the report contains detailed regional and application-level breakdowns and unit-volume tables, those fine-grained splits are withheld in this preview to protect proprietary modeling and to encourage review of the comprehensive dataset available through the full report.
Concrete strategic recommendations for 2026
-
Lock predictable access to plasma and donor programs: execute supply agreements and explore partnership models with collection networks to reduce production volatility.
-
Prioritize formulation advantage in commercialization plans: if your product portfolio includes high-potency variants, build clinical and economic dossiers that quantify the value of lower injection volumes to payers and hospitals.
-
Invest in or partner for diagnostic capacity: integrating advanced neutralization testing shortens release cycles and provides a competitive edge in regulatory submissions and quality assurance.
-
Prepare nimble procurement strategies: design tender responses and pricing proposals that reflect episodic demand patterns and the concentrated supplier landscape; consider multi-year procurement commitments where appropriate.
-
Evaluate targeted inorganic opportunities: prioritize targets that provide plasma sourcing, regional distribution scale, or formulation IP rather than broad-spectrum acquisitions that dilute focus.
How to use this intelligence in your 2026 planning cycle
Executives should use the market-level data and scenario frameworks in three practical ways:
-
Board- and investor-level briefings: translate the report’s forecast and concentration metrics into clear capital-allocation decisions and risk-adjusted return expectations.
-
Operational playbooks: deploy the supplier scorecards and procurement templates to inform contract negotiations and inventory sizing for 2026.
-
Regulatory and product development pipelines: align clinical, regulatory, and testing investments with the diagnostic and potency trends highlighted in the study to accelerate time-to-market for prioritized formulations.
In sum, Human Rabies Immunoglobulin (IM) is a strategically relevant specialty market for 2026: predictable growth, concentrated supply, and discrete technical differentiators mean that well-timed, targeted investments can produce outsized commercial returns. PW Consulting’s full study provides the quantitative detail, supplier assessments, and scenario models necessary to convert these market truths into executable strategies — access to the complete datasets and modeling logic will empower your 2026 planning cycle and tactical execution.
To explore the full dataset, supplier scorecards, and bespoke scenario runs that underpin these conclusions, please refer to the PW Consulting Human Rabies Immunoglobulin (IM) Market report landing page and accompanying appendices.
For detailed analysis of this topic, please visit the official page: Human Rabies Immunoglobulin (IM) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com