

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Animal Stem Cell Therapy Market to Hit USD 375.1 Million by 2032

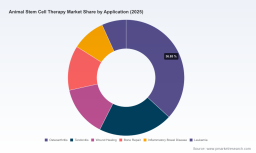
Animal Stem Cell Therapy Market — Strategic Outlook for 2026 Decision‑Makers
By 2025 the commercial market for animal stem cell therapies has transitioned from a niche experimental field into a structured, investible sector attracting both specialized biotechnology firms and larger animal‑health players. Our base‑year analysis (2025) and multi‑year forecast show sustained expansion through the 2026–2032 horizon at a compound annual growth rate of approximately 7.05%, with the overall market more than doubling in value since the start of the decade. For executives planning capital allocation, product prioritization, or M&A activity in 2026, this market is simultaneously an opportunity to capture premium margin streams and a strategic battleground where timing, regulatory clarity, and supply‑chain engineering will determine winners.
Animal Stem Cell Therapy Market
Why this report matters for decisions made in 2026
-
Validation of growth trajectory: Our model reconciles public filings, company disclosures, clinical pipeline events and primary interviews to quantify the addressable market and realistic uptake curves. In plain terms: the market moved from early commercial proofs toward larger volume adoption between 2020 and 2025, and our forecast through 2032 translates that momentum into scenarios that inform resource allocation decisions.
Animal Stem Cell Therapy Market -
Regulatory inflection points are imminent: The U.S. regulatory environment is in active transition. As of early 2025, there were no FDA‑approved ACTPs for veterinary use, yet targeted agency engagements and recent technical acceptances signal a pathway to conditional approvals for a limited set of indications. Our regulatory road‑maps convert public signals into practical timelines and decision gates for clinical development and commercialization.
Animal Stem Cell Therapy Market -
Operational execution will make or break plans: The first commercial deployments of ultra‑low temperature logistics for -80°C cell therapies represent a structural change. Firms that secure cold‑chain capability and clinic‑level cold storage will have an early advantage in delivering “ready‑to‑use” allogeneic products at scale.
What PW Consulting’s report delivers (practical deliverables for 2026)
-
Granular market sizing and high‑confidence forecasts by product type, animal type, application and distribution channel — modeled through 2032 with base year 2025 calibration. (Note: detailed segment tables and downloadable time‑series are available in the full report.)
-
Regulatory playbook: pathway maps for autologous vs. allogeneic approaches, checklist for FDA‑CVM engagements, and a warnings‑and‑mitigation matrix drawing on recent enforcement activity.
-
Supply‑chain and manufacturing diagnostics: gap analysis for GMP cell‑processing capacity, CDMO selection framework, and cold‑chain cost models to estimate incremental COGS and service thresholds for clinic delivery.
-
Clinical evidence and adoption dashboard: catalog of active and planned clinical trials, evidence quality scoring, and the minimum data package required to convert early adopters into mainstream prescribers.
-
Commercial go‑to‑market playbooks: segmentation strategies for companion vs. livestock channels, pricing models, distributor taxonomy and contract templates tailored to veterinary networks.
-
Transaction and partnership intelligence: target shortlist for bolt‑on acquisitions, JV templates for international roll‑out, and a valuation framework linking clinical milestones to enterprise value.
Key market dynamics and implications
-
Regulatory environment: The U.S. FDA‑CVM’s public posture in 2024–2025 confirmed that while pathways to commercialization exist, the agency is enforcing standards. Warning letters issued in 2025 to firms marketing unapproved ACTPs underscore the risk of premature commercialization without adequate evidence or filings. Conversely, targeted technical acceptances for lead programs indicate that conditional approval is achievable with disciplined clinical programs and strong manufacturing controls.
-
Supply‑chain innovation as a competitive moat: One of the earliest strategic moves reshaping the industry was the establishment of clinic‑capable ultra‑low temperature cold chain logistics. Partnerships between therapy developers and veterinary distributors to deliver -80°C products directly to clinics reduce time‑to‑treatment and expand the addressable clinic universe—but they create a tangible barrier to entry for late movers without cold‑chain access.
-
Market structure and concentration: The sector is moderately concentrated: a small set of specialist firms account for a meaningful share of commercial activity and clinical investments, but the remainder of the market remains fragmented and open to consolidation. This mix creates both immediate acquisition targets and greenfield opportunities for new entrants with differentiated clinical data or cost advantages.
-
Clinical and reimbursement dynamics: Veterinary payers and pet owners respond to measurable improvements in functionality and quality of life. Robust, standardized outcome measures—rather than anecdotal evidence—drive willingness‑to‑pay for premium therapies. For livestock applications, pricing sensitivity shifts the decision calculus toward therapies that demonstrably improve productivity per unit cost.
Competitive landscape — strategic takeaways on core players
-
Gallant (San Diego, CA): A leader in off‑the‑shelf allogeneic approaches for companion animals. Their push toward FDA conditional pathways and recent logistics partnership to scale -80°C distribution position them as a commercial first‑mover in ready‑to‑use products. For competitors, Gallant’s model highlights the dual importance of regulatory design and end‑to‑end logistics.
-
VetStem, Inc. (Poway, CA): An established specialist in autologous cell therapies with parallel investments into allogeneic pipelines. Their ability to secure financing to advance an allogeneic orthopedics program demonstrates a hybrid commercial strategy—maintain legacy autologous services while scaling off‑the‑shelf products. Strategic partners should examine VetStem for either distribution tie‑ups or clinical data collaborations.
-
Ardent Animal Health (Nicholasville, KY): A dominant in‑clinic autologous therapy provider. Recent regulatory scrutiny reflected broader sector risks for in‑clinic models that operate without clear approvals. Ardent’s situation illustrates the trade‑off between rapid market penetration and regulatory compliance.
-
VETherapy (San Francisco / Coimbra): Focused on cost‑efficient, time‑effective regenerative solutions. Their approach underscores an alternative go‑to‑market path: prioritize affordability and operational simplicity to access mid‑market clinics that will not bear the premium for complex cold‑chain products.
-
Magellan Stem Cells (Australia): Regional leader in both autologous and donor‑derived MSCs with clinical trial activity underway. For firms targeting Asia‑Pacific expansion, Magellan represents both a technical partner and a model for local regulatory navigation.
Strategic imperatives for executives in 2026
-
Design regulatory‑driven development plans: Build clinical programs around the evidence endpoints that regulatory agencies and practicing veterinarians value most. Prioritize well‑controlled trials with standardized outcome measures to de‑risk commercialization and accelerate payer acceptance.
-
Invest in logistics now or partner: If your product requires sub‑zero storage, establish partnerships or secure internal capabilities for ultra‑low temperature logistics. The incremental cost of cold chain is a defensive investment that preserves market access.
-
Optimize portfolio balance: Maintain a mix of autologous services that generate cash and allogeneic programs that scale. This split helps manage near‑term revenue while funding pivotal trials and manufacturing scale‑up.
-
Pursue clinical data partnerships with leading veterinary centers: Third‑party validation accelerates adoption and provides the evidence base necessary to justify premium pricing.
-
Use M&A selectively: The mid‑market contains acquisition targets with local clinic networks, manufacturing capacity or specialized trial cohorts. Target assets that shorten time‑to‑market or add a defensible distribution channel.
-
Prepare commercial pilots around service economics: Pilot in controlled geographies or partner networks to refine clinic workflows, training, and bundling strategies before wide release.
How different stakeholders will use this research
-
CEOs and corporate strategy teams: to set medium‑term investment priorities and decide whether to build, buy or partner for capabilities such as GMP manufacturing and cold chain.
-
Business development & corporate development: to shortlist targets, structure milestone‑linked deals and price assets using our valuation bridge tying clinical success to revenue trajectories.
-
R&D and regulatory leaders: to map out the minimal evidence package for conditional approval and to design pivotal studies with the highest commercial impact.
-
Manufacturing and supply‑chain executives: to evaluate CDMO partners and calculate the unit economics of different packaging and distribution strategies.
PW Consulting’s Animal Stem Cell Therapy Market study is built to be an operational tool for 2026 decisions. It combines a market model calibrated to real commercial performance in 2020–2025, a forward forecast through 2032, and an executable set of playbooks for regulatory, clinical, manufacturing and commercial execution. We intentionally keep this overview at the trailer level—highlighting where value is created and where risk concentrates—to motivate a deeper review of the full dataset, scenario models and proprietary company dossiers available in the complete report. For teams preparing board materials, investment memos or commercial roll‑outs in 2026, the full study provides the quantitative backbone and tactical templates to move from strategy to execution.
For detailed analysis of this topic, please visit the official page: Animal Stem Cell Therapy Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com