

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Stainless Steel Cookware Market to Reach USD 12,128M by 2032 at 5.6% CAGR

Stainless Steel Cookware Market: Strategic Snapshot for 2026 Decision-Makers
As PW Consulting’s lead industry analyst, I present a focused, executive-grade preview of our new Stainless Steel Cookware Market study. This briefing synthesizes the near-term market trajectory, regulatory and supply-chain shocks, competitive dynamics, and high-conviction strategic moves that should shape boardroom decisions in 2026. Consider this a trailer: enough analytical depth to validate the dataset and reveal the strategic levers, while intentionally withholding the granular segment tables that you will find in the full report.
Stainless Steel Cookware Market
Market trajectory — what the headline numbers tell you
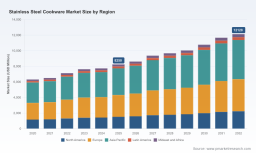
The stainless steel cookware industry entered 2026 having completed a robust expansion cycle: total global revenues grew steadily through 2025 to reach roughly USD 8.25 billion (base year 2025). Our central forecast scenario projects a compound annual growth rate of about 5.6% through 2032, taking the market to just over USD 12.1 billion by the end of the forecast window. That steady mid-single-digit CAGR reflects a mix of continued premiumization among affluent households, recovery and modernization in commercial foodservice, and steady replacement demand in mature markets.
Stainless Steel Cookware Market
Two reading frames are important for executives: first, steady headline growth masks meaningful tactical volatility (raw-material swings, regulatory actions, and import-cost shocks). Second, the market remains commercially fragmented — concentration among top brands is low relative to mature consumer-goods categories — which favors differentiated premium offerings and targeted consolidation plays.
Stainless Steel Cookware Market
Key structural dynamics shaping 2026 decisions
- Premiumization and performance differentiation: Consumers are trading up to multi-ply, bonded stainless constructions and premium finishes that promise durability and induction compatibility. This continues to lift ASPs even as unit-level buying patterns shift toward D2C and online-first discovery.
- Supply-side volatility and raw-material sensitivity: Stainless steel feedstock remains a meaningful cost lever. Recent price snapshots demonstrate materially different cost profiles across grades, creating margin pressure for single-ply producers and opportunity for firms that can secure long-term sourcing or vertically integrate.
- Regulatory and food-safety risk: Public and agency attention to contaminants in cookware has risen. In 2025–26 regulatory actions and public warnings around lead transfer in imported cookware have expanded scrutiny; Washington State’s tightening standards on lead in certain metal cookware (with staged limits through 2028) and U.S. tariff shifts have changed the calculus for where to make and import equipment.
- Fragmented supply and opportunistic capacity expansion: The market’s top-three and top-five concentration metrics remain low, leaving room for nimble players to scale through product and channel strategies or to pursue strategic M&A to build scale quickly.
Recent developments executives cannot ignore
- Regulatory signals: FDA safety notices in 2025–2026 expanded warnings about imported cookware potentially leaching lead — amplifying retailer and distributor due-diligence requirements and raising the bar for testing, documentation, and liability mitigation.
- State-level tightening: Washington State moved to stricter lead limits on certain non-stainless metal cookware, tightening in phases — a precedent that increases the risk of state-by-state regulatory patchworks for manufacturers and importers.
- Trade policy and tariffs: U.S. reciprocal tariff measures enacted in 2025 add an additional layer of import cost exposure for cross-border supply chains that are not fully hedged or localized.
- Capacity shifts: Notable producers in emerging markets signaled ambitious output expansion to meet global demand; such moves can compress prices in the short run and alter OEM contract dynamics.
- Raw-material moves: Grade-specific stainless steel price dispersion can materially alter cost curves for multi-ply versus single-ply manufacturing approaches, rewarding firms that can lock in favorable contracts or redesign for lower-cost grades without compromising performance.
Competitive landscape — who matters and why
The competitive set spans premium U.S. artisan brands, established legacy mass-market names, contract manufacturers, and regionally scaled producers in emerging markets. Key strategic profiles:
- All-Clad: A premium, multi-ply pioneer known for bonded construction and chef credibility. Strengths: brand equity and performance-led product lines. Strategic risks: premium positioning is sensitive to input-cost inflation and inflation-driven downtrading.
- Made In: Positioning around five-ply construction with manufacturing in the USA or Italy supports a “quality and provenance” play — attractive in premium channels but capital-intensive to scale.
- Hestan Culinary: Focused on professional-grade clad lines (ProBond, NanoBond), Hestan competes on product innovation and kitchen-grade durability — a natural bridge to commercial foodservice accounts.
- Tramontina: Global reach with tri-ply offerings positions the firm to defend value and mid-premium segments across markets, benefitting from broad distribution networks.
- Cuisinart and Calphalon: Legacy consumer brands with strong retail relationships; they succeed through breadth, accessible price ladders, and large-scale marketing but must manage complexity across SKUs.
- Zinox / El-Zenouki Group: Emerging as a premium innovator with aggressive production targets — a supplier to watch for volume disruption and price competition in certain channels.
- AXA Cookware, Jiangmen Xinhui, Solamex: China-based manufacturers that compete on manufacturing flexibility and cost; they are central to private-label and volume OEM flows.
- West Bend & contract manufacturers: Critical for buyers seeking domestic capacity or reduced geopolitical exposure; they enable “nearshoring” strategies without the fixed-cost investments of in-house plants.
- Vollrath: Leader in commercial-grade offerings and induction-ready cookware for professional kitchens; an attractive partner for foodservice-focused product lines.
What the full report contains — practical, transaction-ready intelligence
The complete PW Consulting study is structured to move executives from insight to action. Highlights include:
- Methodology and raw dataset: reproducible market-sizing for 2020–2025 and scenario-driven forecasts 2026–2032, including sensitivity tables tied to raw-material and tariff assumptions.
- Demand diagnostics: channel and buyer-behavior frameworks (retail, e-commerce, commercial procurement) and growth levers for ASP and unit velocity.
- Supply-side playbook: supplier maps, cost-to-serve models, and a supplier-risk heatmap incorporating tariffs, lead times, and raw-material exposure.
- Competitive benchmarking: capability matrices for ~12 incumbent and emerging players, with SWOTs, channel footprints, and price-positioning archetypes.
- Regulatory tracker: consolidated timeline and impact analysis for agency actions, product-testing best practices, and a playbook to reduce recall/liability risk.
- M&A and partnership screen: acquisition targets and financial thresholds for roll-up or vertical-integration strategies, plus accretion/dilution models.
- Implementation tools: CFO-ready slide decks, commercial-launch checklists, sample supplier contracts, and an interactive Excel model for scenario planning.
Note: the preview here omits the full segmentation tables by region, type, and application (these are included in the full report and dataset). The omission is intentional: those granular splits unlock tactical decisions (SKU rationalization, channel-specific pricing, and localized manufacturing investments) and are available with the comprehensive purchase.
Practical 2026 playbook — four high-conviction moves
- Prioritize product architecture for margin resilience: Shift portfolio mix toward multi-ply constructions and induction-ready SKUs where performance premiums are defensible. Simultaneously, redesign lower-tier SKUs to reduce raw-material intensity without compromising perceived quality.
- Localize selectively to neutralize tariff and safety risks: Evaluate near-shore or domestic contract manufacturing for flagship lines and high-risk channels. Use contract partners to retain capital flexibility while ensuring traceability and compliance for retail and commercial buyers.
- Institutionalize compliance and testing as brand defense: Invest in validated third-party testing, documented supply chains, and clear on-pack claims. Proactive compliance reduces shelf risk from agency notices and builds trust with large retailers.
- Use M&A and partnerships to scale quickly: In a fragmented market with low top-player concentration, selectively acquire regional brands or contract manufacturers to consolidate distribution, accelerate product development, and capture procurement synergies.
How to use this intelligence right now
Board and commercial teams should immediately run three short exercises using our models:
- Revenue sensitivity test: model the impact of a 5–15% stainless-cost shock and a 10% ad-valorem tariff on blended gross margins across your SKU portfolio.
- Channel reallocation simulation: test profitability and working-capital outcomes of moving 20–40% of premium SKUs to D2C vs. wholesale distribution.
- Make-vs-buy checklist: score potential near-shoring partners for speed-to-market, cost delta, compliance readiness, and capex avoidance.
Final note — why this matters for 2026 decisions
2026 will be a year where everyday purchasing decisions—where cookware is made, how it is certified, and how it is marketed—translate directly into durable competitive advantage or avoidable risk. The stainless steel cookware market’s steady headline growth masks a landscape punctuated by cost shocks, regulatory interventions, and opportunity for consolidation. Executives who combine rigorous cost-sensitivity modeling with nimble supply-chain options and a clear compliance playbook will seize disproportionate share as the market expands toward the USD 12+ billion horizon.
Next steps
For access to the full dataset, granular segmentation by region/type/application, scenario models, and the competitor annex — or to commission a custom strategic workshop that applies these findings to your product portfolio or M&A pipeline — visit the PW Consulting report page or contact our practice lead. The full report delivers the tables and templates you will need to translate this strategic preview into boardroom-ready decisions.
For detailed analysis of this topic, please visit the official page: Stainless Steel Cookware Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com