

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Newborn Screening Instruments Market to Grow at 8.5% CAGR (2026-2032)

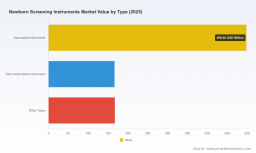
Newborn Screening Instruments Market: Strategic Briefing for 2026 Decision-Makers
As PW Consulting’s senior industry analyst, I present a concise, decision-oriented introduction to our Newborn Screening Instruments Market study. This briefing synthesizes market dynamics, regulatory inflections, competitive posture and practical actions for executives planning capital allocation, product roadmaps and commercial strategies through 2026 and beyond. It is written to demonstrate the depth of our analysis while reserving the detailed segment-level tables and proprietary scenario outputs for the full report.
Newborn Screening Instruments Market
Why this market matters in 2026
Newborn screening is at an inflection point. Advances in mass spectrometry, automated sample handling, molecular platforms and integrated data management are expanding the clinical scope of population screening programs. Coupled with evolving recommended screening panels and renewed reimbursement clarity, demand for instruments and end-to-end screening systems is accelerating. Our base-year analysis (2025) and the six-year forecast horizon (2026–2032) quantify this momentum: the global Newborn Screening Instruments market expands from approximately USD 832 million in 2025 toward a projected USD 1,464 million by 2032, growing at a compound annual growth rate (CAGR) of about 8.5% through the forecast period.
Newborn Screening Instruments Market
What this growth means for corporate strategy
- Market expansion is broad-based, fueled by both programmatic adoption and technological replacement cycles. Executives should treat 2026 as a pivotal planning year to align CapEx offers and upgrade pathways with ongoing public health funding cycles and equipment replacement funds managed at the state and national levels.
- Regulatory developments are increasing required capabilities for screening platforms. Recent additions to recommended uniform screens and FDA guidance on tandem mass spectrometry premarket submissions are raising the bar for analytical scope, traceability and software-enabled result management—areas that favor vertically integrated suppliers and partnerships between instrument makers and software vendors.
- Reimbursement clarity around collection kits and bundled billing codes has reduced commercial uncertainty for certain services and consumables, but variations remain across jurisdictions. Companies must build payer and government engagement into go-to-market plans to protect installed base revenue and accelerate adoption of higher-value assays.
Scope of the PW Consulting report — what you’ll get
The full report is designed as an operational playbook for executives and investment committees. Highlights include:
Newborn Screening Instruments Market
- Market sizing and forecast model with transparent methodology (historical window 2020–2025; forecast 2026–2032; base year 2025; currency USD, revenue in Millions), enabling scenario testing against alternative adoption curves.
- Commercial opportunity maps identifying addressable markets by procurement profile (public vs. private programs), purchase cadence and replacement cycles, with sensitivity levers for panel expansion and reimbursement changes.
- Technology and product roadmaps, assessing analytical platforms (including tandem mass spectrometry, immunoassays, molecular screening and automation ecosystems), consumables demand, and software/data management requirements for large-scale programs.
- Competitive benchmarking and market-concentration analytics, highlighting where scale and service networks create durable advantages and where niche specialists can capture premium margins.
- Actionable go-to-market playbooks: tender and procurement strategies for public health labs, pricing and bundling templates for instrument-plus-consumable offers, and partnership frameworks for assay co-development and lab services.
- Risk matrix and regulatory horizon mapping to inform product development priorities and premarket submissions planning.
Competitive landscape — who to watch
Market concentration is meaningful. The top three players control a substantial share of global revenues, and the top five command an even larger portion—creating both barriers to entry and opportunities for differentiated players able to serve specific clinical or regional needs. Our competitive intelligence focuses on product breadth, installed base economics, consumables margins and software-driven workflow capture.
- Revvity (United States) — Positioned as a systems integrator, Revvity offers end-to-end newborn screening solutions that bundle instruments, reagents, consumables and laboratory software. Its strength lies in capturing lifecycle revenue and in cross-selling into existing clinical laboratory channels. For established vendors like Revvity, the strategic play in 2026 is protecting consumable attach rates while accelerating software-as-a-service offerings for centralized result management.
- Chromsystems Instruments & Chemicals GmbH (Germany) — A technical specialist focused on mass spectrometry-based assays, Chromsystems has extended its assay capabilities to increase analyte panels measured from dried blood spots. Such technical depth allows niche specialists to command premium positions in labs that prioritize analytical breadth and per-test performance. For competitors, the response must combine assay breadth with automation and lab-informatics integration.
- LaCAR MDx (United States) — Targeting automation and workflow simplification, LaCAR MDx focuses on modular machines, tailored reagents and data management that streamline the screening pathway. Their go-to-market advantage lies in workflow integration and rapid deployability to public health labs seeking to scale programs without large capital footprints.
Recent industry signals that change the calculus
- Regulatory expansion of recommended panels has demonstrable commercial impact. Capacity needs increase when new conditions are added to screening recommendations; this drives instrument procurement, assay development and laboratory automation investments. Policymakers’ decisions to add high-profile conditions to screening panels materially alter near-term demand.
- Program launches at the state level continue to drive incremental demand. Announcements from public health authorities indicating the phasing-in of new conditions or expanded screening tests create predictable procurement windows for instruments, kits and informatics services.
- Manufacturers are upgrading assay kits and analytical packages to increase per-sample analyte coverage. Product refreshes that allow simultaneous quantitation of extended analyte panels enhance value propositions for centralized screening labs and regional reference centers.
- Reimbursement rules—particularly those permitting bundled billing for collection kits, postage and associated processing—improve the economics for providers and reduce resistance to new kit-based workflows. Equipment acquisition funds and state-level replacement programs also support buyer readiness for capital refresh cycles.
- Regulatory guidance on premarket expectations for tandem mass spectrometry and related systems continues to shape time-to-market and development spend. Companies must budget for robust analytical validation and software verification pathways as part of commercialization timelines.
Strategic recommendations for 2026
- Prioritize integrated value propositions: Buyers are increasingly buying systems (instrument + consumables + software) rather than point products. Build bundled offerings with clear TCO benefits and contractual consumable commitments to protect margins.
- Align R&D with regulatory trajectories: Invest early in analytical validation resources and premarket planning for platforms supporting expanded panels. Regulatory-readiness shortens sales cycles in public procurements and reduces deployment friction.
- Segment sales motions by procurement archetype: Differentiate strategies for national public health tenders, regional reference labs and private hospital networks. Tailor pricing, service levels and financing options for each archetype to capture more of the acquisition funnel.
- Leverage partnerships for speed-to-market: Co-development agreements with assay specialists, and integrations with laboratory information systems, accelerate adoption while limiting upfront capital exposure.
- Monitor reimbursement and state-level capital programs closely: Reimbursement codes and replacement funds materially influence purchasing windows; active engagement with policymakers and payers can convert technical superiority into faster deployments.
- Consider aftermarket service and software monetization: With market concentration favoring established vendors, aftermarket services and SaaS deployment are viable routes to secure recurring revenue and improve customer retention.
How PW Consulting’s deliverables drive 2026 decisions
Our full study combines the quantitative growth model (historical 2020–2025; base 2025) with actionable go-to-market modules and procurement playbooks. We provide scenario-ready financial models to stress-test alternative adoption rates, and bid/no-bid criteria for tenders aligned to product and service economics. The report’s competitive decks offer win-loss insights and suggested counter-strategies for each major competitor and for regional market nuances.
Importantly, while this briefing outlines the strategic contours and major signals, it intentionally omits detailed segment-level figures and the proprietary scenario outputs that are most valuable to decision-makers. Those detailed breakouts—regional demand curves, application-level forecasts, product-level price elasticities and tender-level unit economics—are accessible only through the full report and the interactive forecast model.
Next steps
- Use this briefing to align internal 2026 planning assumptions around a central case that assumes ~8.5% CAGR through 2032 and the material expansion in addressable instrument spend driven by program additions and replacements.
- Contact PW Consulting to schedule a tailored walkthrough of the full models and a reverse-brief workshop. We will calibrate the forecast to your product roadmap, simulate procurement opportunities and prioritize the top levers to accelerate share gains in the near term.
For teams preparing capital budgets, product launches, or policy engagement in 2026: our Newborn Screening Instruments Market study converts public-health momentum into executable commercial strategies. Request the full report to access the proprietary segment-level intelligence, tender-level economics, and the interactive forecast model that underpin high-confidence investment decisions.
For detailed analysis of this topic, please visit the official page: Newborn Screening Instruments Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com