

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Cellulose Powder Market to Reach USD 276.0 Million by 2032 at 5.48% CAGR

Cellulose Powder Market — 2026 Strategic Preview
As companies prepare strategy and capital allocation plans for 2026, an evidence-based, commercially actionable view of the cellulose powder market is no longer optional — it is mission-critical. This preview frames the key commercial and regulatory inflection points that will shape outcomes over the next investment cycle, and explains how our full PW Consulting Cellulose Powder Market Report can be used as an operational decision tool. The intent here is to demonstrate the analytical depth and executive-grade insight you will find in the complete study, while deliberately withholding core segment-level tables and granular regional splits that are available in the full product.
Cellulose Powder Market
Market snapshot: size, trajectory and structural context
Using 2025 as the base year, the global cellulose powder market has shown steady expansion through the 2020–2025 historical window and is projected to continue growing across the 2026–2032 forecast horizon at a mid-single-digit compounded annual growth rate (CAGR) of approximately 5.48%. To set the strategic baseline: the market expanded materially from the early 2020s into 2025 and, absent major shocks, is expected to approach the high two-hundreds (USD, million) by the end of the 2032 forecast horizon. That pace of growth is sufficient to justify targeted investment but not so rapid as to remove the need for disciplined go-to-market execution and product differentiation.
Cellulose Powder Market
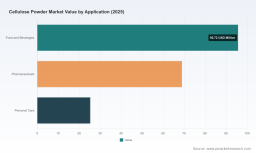
What that growth reflects in practice is a mix of steady demand uplift from established applications (notably processed foods and pharmaceuticals), incremental adoption in personal care and specialty formulations, and higher-value use-cases tied to clean-label and fiber-fortification trends. The aggregate dynamics conceal important heterogeneity across product grades and end-markets — precisely the kind of segmentation our full study models with detailed demand drivers, elasticity analyses and price-path scenarios.
Cellulose Powder Market
Dynamics shaping 2026 decisions
-
Regulatory momentum and compliance timelines — Powdered cellulose remains an accepted food additive under international GSFA rules when manufactured under good practice conditions, but jurisdictional developments are active. Notably, China has advanced a draft national standard for food-contact regenerated cellulose materials (open for consultation through mid-2026), and U.S. food labeling regulations published during 2025–2026 include uniform compliance windows stretching into 2028. For commercial leaders, that means regulatory-readiness is a two-year program that must be resourced now to avoid product delisting or relabeling costs at critical launch points.
-
Clean-label and nutritional premiumization — Reformulation teams continue to substitute synthetic or multi-ingredient stabilizer systems with single-ingredient, plant-derived cellulose grades where possible. This drives incremental demand for food-grade, certified cellulose powders but also raises material-performance expectations (flow, mouthfeel, suspension stability) that favor suppliers with strong application R&D capabilities.
-
Sustainability and supply transparency — Procurement teams are increasingly sourcing based on traceability, lifecycle profiles and certification footprints. Suppliers that can demonstrate responsible pulp sourcing and provide transparent chain-of-custody documentation are winning specification slots with blue-chip packaged food and pharma customers.
-
Moderate fragmentation at the supplier level — The market structure shows room for regional champions and specialist producers. Leading manufacturers focus on food-grade and pharmaceutical-grade portfolios, while mid-sized players and some regional mills concentrate on commodity grades and local channels. This creates opportunities both for differentiated commercial models and for consolidation where scale improves security of supply and technical service reach.
Supply-side view and commercial implications
Raw material dynamics (cellulose feedstock and energy costs), production scale, and technical-grade differentiation are the three levers that determine margin and commercial competitiveness. Successful producers combine: rigorous quality systems that enable food- and pharma-grade certifications; application labs that can field trial grades with major formulators; and flexible manufacturing that supports small-batch specialty runs alongside larger commodity volumes.
From a procurement and operations standpoint, buyers should model a two-track sourcing strategy in 2026: secure core volumes from long-term, fully qualified suppliers to de-risk supply, while using agile, technical partners for innovation-led product introductions. For manufacturers, the inverse is true — protect core book-of-business economics while investing selectively in application development and sustainability claims that unlock premium pricing.
Competitive landscape — what leading players are doing
Our universe of core manufacturers includes global incumbents and regional specialists who have each adopted distinct positioning strategies. High-level takeaways relevant to boardrooms and strategy teams:
-
Producers with strong food-grade pedigrees are competing on both product performance and certification — this is a clear differentiator for suppliers that serve global packaged-food accounts. These firms invest in V&V (verification & validation) for anti-caking, bulking, and texture-modifying applications and provide co-development support to customers.
-
Companies that pair cellulose powder portfolios with adjacent excipient or fiber ingredients can offer bundled solutions that increase switching costs and gross-to-net capture. This breadth of portfolio is strategically valuable for suppliers seeking to move beyond commodity pricing.
-
Regional players retain advantage where logistics complexity, tariff exposure, or local regulatory nuances favor proximity. For multinationals, strategic partnerships or minority investments in regional mills offer faster market entry without immediate capital-intensity.
Illustrative company-level implications (profiles in the full report): suppliers that emphasize food-grade microcrystalline cellulose and powdered cellulose have prioritized application support to win large volume contracts with formulators. Firms with global brand recognition pair manufacturing excellence with customer service and certification credentials. Regional manufacturers often leverage cost or specialty grade claims to serve growing domestic food-processing industries.
Commercial playbook for 2026 — five prioritized moves
-
Institutionalize regulatory and labeling programs: build a cross-functional compliance sprint to align product specs with the latest Codex/GFSA interpretations and the looming U.S. label compliance window. This reduces recall and relabeling risk while preserving market access.
-
Lock in supply and optionality: negotiate supply agreements that include flexible volume bands and price-indexing mechanisms to manage pulp feedstock volatility. Consider dual-sourcing critical grades where single-source exposure is material to production.
-
Invest in application-led differentiation: prioritize R&D that yields demonstrable performance lift in target applications (e.g., shelf-stable beverages, high-protein bars, chewable pharmaceuticals) and convert trials into co-marketed case studies.
-
Commercialize sustainability narratives with evidence: obtain lifecycle and chain-of-custody data to support customer ESG requirements and procurement scorecards — treat these as sales enablement assets, not optional extras.
-
Use M&A and partnerships selectively: deploy capital to acquire capabilities you lack (specialty processing, regional footprint, or certified feedstock access) rather than duplicating generic capacity.
M&A, partnerships and execution screening
For corporates evaluating inorganic routes, the right target checklist includes: proven food- or pharma-grade production, validated application lab capabilities, secure feedstock channels, and customer contracts with long-term purchase commitments. The full report provides a prioritized M&A screen and a short-list of target archetypes based on our commercial valuation model, including accretion scenarios and capex timelines.
What the full PW Consulting report contains (practical outputs)
-
Proprietary demand model and scenario matrix — built from bottom-up application forecasts, validated through primary interviews and manufacturing-side capacity checks. (Note: detailed segment-level figures and regional splits are reserved for the full report.)
-
Supplier landscaping and capability benchmarking — technical scorecards, manufacturing footprints, certification status, and commercial positioning for the key incumbents and emerging challengers.
-
Price and margin trajectories — historical pricing, cost-input sensitivity analyses, and mid-cycle pricing scenarios tailored to raw-material and energy paths.
-
Regulatory impact assessment and compliance playbook — jurisdiction-by-jurisdiction implications and an operational checklist to meet food-contact and labeling timelines.
-
Commercial playbooks and go-to-market templates — account segmentation, value-based pricing frameworks, partnership templates, and a launch-to-scale checklist for new grades.
-
M&A valuation model and target prioritization — synergy analysis, integration risk profiles, and a three-year integration roadmap to support rapid value capture.
-
Interactive dashboards and spreadsheets — downloadable models you can adapt to your internal assumptions and produce board-ready scenarios in hours, not weeks.
How to use this intelligence in 2026 planning cycles
Senior leaders should treat the findings as an actionable bridge between market facts and capital allocation. Three concrete uses in 2026:
-
Board-level scenario stress-testing — use our scenario outputs to stress-test revenue and margin assumptions under alternative regulatory and feedstock-price paths.
-
Procurement and commercial alignment — convert model outputs into negotiation strategies: which grades to hedge, where to confirm long-term contracts, and how to tier customers by value.
-
R&D and product development prioritization — allocate incremental R&D budget toward formulations and grade improvements that unlock the highest willingness-to-pay in target segments.
Concluding perspective
The cellulose powder market in 2026 offers a mix of steady baseline growth and strategic inflection points. Growth alone does not guarantee profitability; rather, profitability will accrue to organizations that execute a coordinated program across regulatory compliance, product differentiation, supply-security and sustainable sourcing. PW Consulting’s full report converts raw market statistics into executable strategies — from supplier selection and R&D prioritization to M&A screens and commercial playbooks — enabling management teams to convert market opportunity into durable competitive advantage.
For executives ready to transform insight into action, access to the full, segment-detailed study (including regional and application-level breakdowns, supplier market shares, and the interactive financial models) is available via our web portal. The preview above maps the strategic terrain; the full report provides the navigational instruments to lead through it.
For detailed analysis of this topic, please visit the official page: Cellulose Powder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com