

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Railway Equipment Market to Hit USD 535.08M by 2032 at 6.45% CAGR

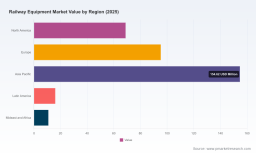
Railway Equipment Market 2026: Strategic Briefing for Executive Decision-Makers
As governments and operators accelerate rail investments to meet decarbonisation, urbanisation and logistics resilience goals, 2026 is a pivotal year for strategic choices across procurement, manufacturing footprint, and technology partnerships. PW Consulting’s Railway Equipment Market research synthesises seven years of historical performance with a forward-looking forecast to 2032, delivering the actionable intelligence leaders need to prioritise investments, de-risk supply chains, and win procurement rounds in a more concentrated, standards-driven market.
Railway Equipment Market
Why this research matters for 2026 decisions
Boardrooms and procurement teams planning capital programmes in 2026 face three intersecting pressures: sustained market growth, tightening regulatory requirements, and an oligopolistic supplier landscape. The market has expanded materially from the start of the last decade and, under PW Consulting’s base-case forecast, continues to grow at a mid-single-digit compound annual rate through 2032. That pace translates into sizeable incremental demand for rolling stock, track infrastructure, signalling and digital systems — creating both scale opportunities for incumbents and entry windows for specialised suppliers. Our study converts these macro dynamics into decision-ready insights: which sub-systems will see the fastest replacement cycles, how standards changes will reshape product roadmaps, and where margin pools will shift between OEMs, systems integrators and aftermarket service providers.
Railway Equipment Market
Market trajectory: headline figures and what they imply
Using 2025 as a base year and a forecast horizon to 2032, the study traces the market’s recovery and structural growth, and overlays scenario paths that reflect alternative macro and policy outcomes. The base forecast implies a steady expansion driven by fleet renewals, network electrification and digital signalling upgrades. For executives this means predictable demand streams for core mechanical and electronic components, while pockets of accelerated spending will emerge where major events, urban programmes or freight modal shifts align.
Railway Equipment Market
Two high-level metrics are critical for strategic planning and are unpacked qualitatively in the report: a clearly rising market scale over the 2020–2025 historical window, and a forecast CAGR that supports multi-year supplier contracts and capacity investments. These macro indicators enable CFOs to model capital allocation under conservative and aggressive uptake scenarios, and allow technology teams to prioritise feature sets that will deliver compliant, upgradable platforms over the next procurement cycle.
What the PW Consulting report delivers (operationally actionable)
- Market sizing and growth drivers: a transparent methodology linking historical shipments and contract pipelines to forward demand scenarios, with sensitivity testing for commodity prices, stimulus packages and modal-shift trends.
- Product and technology roadmap analysis: assessment of mechanical subsystems, signalling generations, power electronics and embedded systems — mapped to regulatory milestones and upgrade windows.
- Supply chain and capability heatmaps: supplier tiering, localisation risk scoring, lead-time baselines, and recommended hedging strategies to secure critical components and testing capacity.
- Procurement playbooks: negotiation levers for long-term service agreements, part-improvement clauses for evolving standards, and contracting templates that protect against obsolescence and interoperability risk.
- Commercial and M&A screening tools: target shortlists and integration checklists for inorganic growth, with play-by-play risk assessments for cross-border transactions and joint ventures.
- Scenario-driven investment models: CAPEX/OPEX modelling templates that allow rapid stress-testing of fleet vs. infrastructure spend mixes and their ROI profiles under alternative policy scenarios.
- Regulatory impact assessment: implementation roadmaps for compliance with emerging standards and certification timelines, including testing regimes and documentation expectations.
- Aftermarket & service strategies: monetisation frameworks for predictive maintenance, retrofits and digital services that extend asset life and capture recurring revenue.
Competitive landscape: positioning the major players
The market remains concentrated: our competitive analysis shows a clear top-tier cluster of global OEMs and systems integrators that collectively capture a dominant share of the available market. This concentration creates distinct strategic implications — from pricing power and the ability to internalise system integration, to the difficulty niche suppliers face breaking into major programmes. Below is a qualitative view of key incumbents and their strategic trajectories.
- Wabtec Corporation — A diversified supplier with strong capabilities across couplers, braking systems and digital fleet management. Recent strategic moves have reinforced its systems integration play and expanded its addressable portfolio in passenger equipment. Wabtec is positioning itself as a go-to partner for operators seeking modular upgrade paths that combine mechanical hardware and software-driven services.
- Alstom SA — Deep expertise in signalling and rolling stock, with an emphasis on integrated solutions for complex network modernisations. Alstom’s certification and programme wins in high-profile markets underscore its ability to translate regulatory compliance into deployable systems at scale.
- Hitachi Rail — Strength in ETCS implementations and high-speed vehicle platforms, with an increasing focus on digital systems that enhance interoperability. Hitachi’s approach favours long-term partnerships with rail operators and large infrastructure programmes.
- Siemens Mobility — A leading provider of train control systems and high-speed equipment, with a bundled offering that combines rolling stock, signalling and electrification. Its strategic alliances in emerging high-speed markets reinforce its ability to win end-to-end contracts.
- CRRC Corporation Limited — A high-volume manufacturer with strong cost competitiveness and breadth across mainline and high-speed rolling stock. CRRC’s scale allows rapid delivery on large fleet orders, making it a natural supplier in price-sensitive mass-transit programmes.
- Progress Rail — Focused on locomotives and infrastructure equipment for freight-dominant markets, with deep local-market expertise and service networks that appeal to regional operators.
- CAF — A specialist rolling stock manufacturer that competes on modular designs and lifecycle maintenance offerings, often chosen for mid-sized fleet modernisation projects and bespoke vehicle platforms.
Across the competitive set, notable themes are consolidation of system-level capabilities, partnerships to validate digital couplers and interoperability standards, and an emphasis on compliance-ready product certification. These dynamics favour firms that can bundle hardware, software and services while navigating evolving certification regimes.
Regulatory and standards pressure: EN 50155:2026 and beyond
A significant regulatory development for 2026 is the updated EN 50155:2026 standard, which tightens requirements for the design, testing and documentation of electronic equipment installed on rolling stock. The standard’s expanded environmental and electromagnetic compatibility requirements, along with stricter testing for temperature, humidity, shock and vibration, reshape supplier product spec sheets and validation timelines. For executives, the practical implications are straightforward: product roadmaps must incorporate higher engineering margins for test and qualification, procurement timelines must allow for extended certification cycles, and suppliers without robust test capabilities risk exclusion from major tenders.
Our report provides an implementation playbook for EN 50155:2026, including recommended test regimes, documentation checklists and supplier audit templates — all designed to prevent last-mile certification delays that can derail delivery schedules and trigger contractual penalties.
Strategic takeaways for executives (how to act in 2026)
- Prioritise strategic supplier consolidation where it reduces TCO without creating single-source exposure. Use staged volume commitments tied to certification milestones.
- Invest in certification and testing capability either in-house or via accredited partners to accelerate time-to-market for new subsystems aligned with EN 50155:2026.
- Allocate a share of CAPEX to modular, upgradeable architectures — this preserves flexibility as signalling and digital standards converge internationally.
- Use scenario models from the report to stress-test procurement strategies under alternative macro paths (e.g., accelerated electrification vs. deferred public investment).
- Embed aftermarket service clauses early in vendor negotiations to create recurring revenue streams and improve lifecycle performance.
Why you should read the full report
This briefing highlights the strategic contours of the Railway Equipment market as of 2026, but the granular intelligence that underpins procurement decisions—detailed demand curves by subsystem, supplier scorecards, bid-analytics, and downloadable financial models—is reserved for the full PW Consulting study. The report is intentionally structured to support rapid executive action: ready-to-use templates, scenario workbooks, and supplier negotiation playbooks cut weeks from typical strategic planning cycles.
For leaders setting budgets, negotiating multi-year contracts, or exploring inorganic growth, the full research provides the data, models and operational checklists necessary to convert market growth into sustained competitive advantage while avoiding the common pitfalls that accompany standards shifts and concentrated supplier markets.
Next steps
- Request the full Railway Equipment Market report to access segmented demand models, supplier matrices and the scenario workbooks referenced here.
- Book a strategy session with PW Consulting’s railway team to translate the forecast into a tailored procurement and investment roadmap for 2026–2028.
PW Consulting’s Railway Equipment Market research is designed to give executives the confidence to act decisively in 2026—balancing growth capture with regulatory compliance and supply-chain resilience. For a deeper dive into the models and supplier-level intelligence that support these conclusions, please consult the complete report.
For detailed analysis of this topic, please visit the official page: Railway Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com