

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Anti-Fog Coatings Market Set to Expand at 3.5% CAGR Through 2032

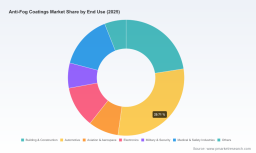
Anti‑Fog Coatings Market 2026: Strategic Signals for Executives — A PW Consulting Preview
Executive snapshot
As companies prepare strategic roadmaps for 2026, the anti‑fog coatings market is transitioning from niche technical applications toward mainstream industrialization. Our latest PW Consulting research — with a 2025 base year and a seven‑year forecast horizon through 2032 — shows a steady expansion at a mid single‑digit compound annual growth rate (CAGR) of 3.5% across the forecast period. After gradual recovery and consolidation during 2020–2025, the market is positioned to grow modestly in both mature and emerging verticals, driven by sustainability mandates, next‑generation optics, and novel application formats.
Anti-Fog Coatings Market
Why this research matters for 2026 decision cycles
-
Capital allocation: The market’s predictable, moderate growth profile favors targeted, risk‑light investments — productization of eco‑compliant chemistries, small‑scale capacity expansions focused on high‑margin end‑uses, and capex staged around validation cycles rather than large single‑phase builds.
Anti-Fog Coatings Market -
Portfolio prioritization: Companies evaluating where to play will need to reconcile legacy glycerol‑ester workhorse chemistries with emerging waterborne silicones, sol‑gel hybrids, and passive thermal anti‑fog concepts. The cost/benefit calculus in 2026 increasingly hinges on regulatory fit and long‑term value capture rather than short‑term share wins.
Anti-Fog Coatings Market -
M&A and partnerships: With supplier concentration low and the top players accounting for well under one‑third of total market value, strategic M&A and alliances remain effective routes to scale in targeted niches (high clarity optical coatings, medical devices, advanced automotive optics) without battling entrenched incumbents across broad geographies.
-
Commercial execution: Pricing, channel strategy, and OEM qualification timelines will dominate commercial returns. Buyers in automotive, medical, and eyewear sectors are shifting toward in‑house or vertically integrated anti‑fog solutions — a trend that demands tighter supplier collaboration and co‑development agreements.
Market trajectory and what the numbers signal (macro view)
From a PW Consulting vantage point, the global anti‑fog coatings market demonstrates resilience: after bottoming and then rebounding through the early 2020s, the market reached an inflection point in 2024–2025 that validates longer‑term demand for optical clarity across multiple verticals. Our top‑line sizing for 2025 provides a concrete planning anchor for corporate finance teams and product roadmaps; layered atop a 3.5% CAGR to 2032, this creates a reliable scenario base for NPV analyses and staged commercial rollouts.
Importantly, the growth is not uniform — it is characterized by pockets of accelerated adoption (advanced optics, medical devices, and certain consumer electronics sensors) alongside slower, cost‑sensitive segments. For 2026, that means tactics should be differentiated: premium R&D and qualification investments in high‑value bays, while cost engineering and supply chain optimization govern lower‑margin, high‑volume applications.
Practical contents of the PW Consulting report
This study is structured as an operational playbook for senior strategy and commercial leaders. Key deliverables include:
-
Top‑down market sizing and scenario models (base year 2025; forecast 2026–2032) with sensitivity testing for raw material price shocks, regulatory accelerants, and OEM qualification lag.
-
Go‑to‑market playbooks for six distinct end‑use archetypes — from high‑clarity optics to food‑packaging films — highlighting required performance thresholds, qualification timelines, and margin expectations.
-
Technology readiness maps: chemistry families, substrate compatibility, application processes (spray, dip, in‑line film coating), and a three‑year innovation pipeline for disruptive entrants.
-
Regulatory and sustainability matrix identifying near‑term compliance triggers, green‑chemistry incentive programs, and packaging/food‑contact certification pathways.
-
Commercial diligence packs (supplier scorecards, OEM procurement checklists, channel‑partner templates) and a prioritized shortlist of M&A and JV targets by strategic objective.
-
Supply chain and procurement playbooks: raw material exposure maps (including glycerol esters and waterborne alternatives), labor cost impact assessments, and cost‑to‑serve benchmarks.
Competitive landscape — who matters and why
The competitive map remains fragmented with several specialized leaders and a vibrant mid‑market focused on regional OEM relationships. Leading firms demonstrate three strategic archetypes: performance leaders with OEM approvals, chemistry innovators pushing durability and optical metrics, and cost‑focused producers serving packaging and general‑purpose films.
-
FSI Coating Technologies (Irvine, CA): Recognized for durable, performance‑based systems validated for aerospace and automotive OEMs. Their Visgard and Vistex lines — with OEM compatibility and NASA approvals — exemplify the premium performance playbook and provide a blueprint for licensing and co‑development strategies.
-
Momentive Performance Materials (Waterford, NY): A materials‑platform player emphasizing silicone‑based SilFORT™ chemistries with long‑term hydrophilicity and optical clarity — well positioned for ADAS, lighting modules, and EV front‑end assemblies where lifetime performance commands a premium.
-
Hydromer, Inc. (New Jersey): Focused on medical and safety devices, their premium hydrophilic coatings highlight the certification depth and stability requirements needed to win in regulated markets; a go‑to example for companies pursuing premium medical or PPE channels.
-
NSG Group (Tokyo): Applies sol‑gel hybrid expertise for camera and sensor optics where water resistance and adhesion on plastics are critical. Their approach is instructive for firms bridging glass and polymer substrate strategies.
-
WeeTect Material (Shanghai): A regional innovator in hydrophilic coatings for plastics and visors, demonstrating how local OEM intimacy and cost‑engineered application processes can win volume business without competing directly on high‑end performance metrics.
Recent industry moves that will shape 2026 tactics
-
Product refreshes and portfolio extension: Notable product brochures and launches from performance leaders signal an arms race in durability and OEM compatibility — an area where early testing and joint validation can become decisive.
-
Packaging and film innovation: New transparent BOPET lidding films with built‑in anti‑fog properties point to adjacency opportunities for film producers and coaters to capture shelf‑differentiation economics.
-
Novel application paradigms: Passive thermal anti‑fog solutions and other non‑traditional approaches are emerging; these technologies may reframe installation and lifetime cost calculations for high‑value optical assemblies.
Market dynamics and risk factors to stress‑test
-
Raw material dynamics: Glycerol esters continue to be the pragmatic chemistry for many applications due to cost and food‑contact acceptance. However, suppliers pursuing waterborne silicones or sol‑gel hybrids benefit from premium pricing and regulatory tailwinds.
-
Regulatory and sustainability imperatives: Growing demand for waterborne and low‑VOC systems — including regulatory programs and government incentives for green chemistry in select jurisdictions — favors suppliers who can rapidly validate eco‑compliant formulations.
-
Labor and manufacturing cost pressure: Expert finishing and proprietary in‑house treatments (notably in eyewear and specialty optics) are increasingly used to reduce outsourced coating costs — a trend that changes the supplier bargaining dynamic.
-
OEM qualification and time‑to‑market: Long validation cycles in automotive and medical segments make early engagement, co‑validation platforms, and shared test benches a competitive necessity rather than a nicety.
Actionable strategic plays for 2026
-
Prioritize dual‑track product development: protect incumbency in glycerol‑ester applications while accelerating modular pilots for waterborne and sol‑gel alternatives targeted at optical and medical customers.
-
Design qualification partnerships: invest in co‑validation agreements with key OEMs and system integrators to compress approval timelines and lock in technical roadmaps.
-
Execute focused M&A or JVs: target bolt‑on capabilities (surface treatment labs, niche substrate competency, regional application centers) rather than broad horizontal consolidation.
-
Develop a differentiated procurement stance: secure long‑term supply agreements on critical raw materials and explore backward integration for coating intermediates where it meaningfully improves margin and reliability.
-
Commercialize verified sustainability claims: certify and market eco‑compliant formulations for regulatory wins and to satisfy large OEMs’ supplier scorecards.
Conclusion — the strategic choice
For executives shaping 2026 plans, the anti‑fog coatings market offers a mixture of stability and selective disruption. The market’s moderate growth and fragmented supplier landscape reward focused plays: invest where technical differentiation meets regulatory impetus, secure OEM validation early, and use targeted partnerships or small‑scale M&A to accelerate market access. PW Consulting’s full market study provides the granular models, supplier due‑diligence packs, and playbooks you need to convert these strategic signals into executable 12‑ to 36‑month programs.
Next steps
Contact PW Consulting to access the complete report, detailed segmentation tables, scenario models, and the supplier scorecards required for commercial diligence and capital planning in 2026. Our deliverables are built to be directly usable by corporate strategy teams, business unit leaders, and M&A desks seeking immediate action items.
For detailed analysis of this topic, please visit the official page: Anti-Fog Coatings Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com