

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Rainwater Harvesting Market Poised for 8.36% CAGR Through 2032

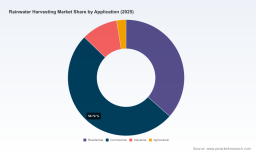
Rainwater Harvesting Market — 2026 Strategic Brief
Executive summary
The global rainwater harvesting market has moved from a niche sustainability play into a mainstream infrastructure and building-services opportunity. Using 2025 as the base year (historical coverage: 2020–2025; forecast period: 2026–2032), PW Consulting models the market at USD 1,160 Million in 2025 and projects growth to approximately USD 2,040 Million by 2032 under a baseline scenario that assumes a compound annual growth rate of 8.36% during the forecast window. That growth reflects accelerating demand across new-build and retrofit segments, rising regulatory and standards activity, expanding commercial and municipal deployments, and improving economics for decentralized water reuse systems.
Rainwater Harvesting Market
Why this matters for 2026 decision-making
-
Timing: 2026 is the inflection point for many organizations — procurement cycles are shortening, public-sector grant windows and rebate programs are being re-scoped, and standards activity is crystallizing technical requirements for rooftop and stormwater capture systems. Decisions made in early–mid 2026 will shape contract pipelines and technology choices through the next five to seven years.
Rainwater Harvesting Market -
Risk and reward: The category is attractive for revenue expansion (driven by hardware, services, and recurring O&M) but exposed to regulatory variability, fragmented channel economics, and pockets of high price sensitivity. Firms that align product, service, and compliance strategies now can capture outsized share as adoption accelerates.
Rainwater Harvesting Market -
Strategic inflection: Standardization, digital enablement, and bundled finance are turning what were once point-product purchases into integrated infrastructure projects — creating larger ticket sizes and longer contract lives for incumbents and new entrants able to deliver end-to-end solutions.
What the PW Consulting report delivers (practical, operational outputs)
-
Top-line market sizing and scenario modeling (base year 2025; historical 2020–2025; forecast 2026–2032), including sensitivity cases tied to regulatory uptake and incentive availability.
-
Driver and barrier maps that link technical, economic, and policy levers to adoption velocity — framed for executive decision use (product roadmaps, regional investment priorities, and sales quotas).
-
Commercial playbooks: go-to-market frameworks by buyer-type, procurement templates for municipal and commercial tenders, and channel partner selection criteria.
-
Technical diligence checklists for tanks, filtration, pumps, and IoT monitoring; lifecycle cost models (CAPEX/OPEX) and maintenance scheduling templates.
-
Competitive benchmarking and M&A screening toolkit that flags integration synergies across manufacturing, services, and digital layers.
-
Regulatory and incentives tracker, continuously updated to inform bid strategy and grant capture efforts.
Competitive landscape — who to watch and their strategic postures
Market concentration metrics indicate a moderately consolidated competitive set (CR3 ~47.1%; CR5 ~52.5%), i.e., a handful of players command material share while a long tail of regional specialists and systems integrators compete on price, service, or niche applications. The field can be segmented strategically into manufacturers of storage and hardware, integrated systems providers, and service-led players — though many firms operate across more than one lane.
-
Kingspan Group plc (Ireland) — Strength: advanced, scalable rainwater and water-management systems positioned at the commercial and multi-residential end. Strategic implication: incumbents with strong building-industry relationships and specification channels will defend large project pipelines but must adapt to service and digital offerings to sustain margins.
-
Watts Water Technologies, Inc. (Massachusetts, USA) — Strength: RainCycle commercial systems geared to capture, treat, and deliver non-potable water. Strategic implication: modular, packaged systems that ease procurement are winning in institutional and commercial tenders; competitors should prioritize plug-and-play compatibility and compliance documentation.
-
GRAF Group (Austria) — Strength: broad portfolio of plastic tanks, filtration, and harvesting packages with a visible sustainability program. Strategic implication: product manufacturers are differentiating through ESG transparency and lifecycle emissions reductions — an increasingly decisive tender criterion.
-
WISY AG (Germany) — Strength: IoT-enabled smart filtration and harvesting solutions. Strategic implication: digital capabilities (remote monitoring, performance guarantees) are emerging as high-margin service enablers and a source of differentiation for mid-sized projects.
-
Premier Tech Water and Environment (Canada) — Strength: end-to-end water and stormwater solutions for domestic, commercial, and infrastructure projects. Strategic implication: full-systems integrators are positioned to capture larger contracts but must demonstrate interoperability and standards compliance.
-
Marsh Industries (UK), Graf UK, Rainwater Management Solutions (US) — Strength: regional and application-focused offerings (pumping, direct harvesting, installation support). Strategic implication: regional specialists with installation, aftermarket, and local compliance expertise remain critical partners for national and global players scaling operations.
Regulatory, standards and incentive signals to monitor in 2026
-
Standards and certification: Industry bodies are moving quickly to codify practices. New standards and in-field certification programs are being launched that will materially affect eligibility for GSA and other public procurement frameworks. Expect compliance to become a pre-requisite for major capital projects.
-
Regulation: Several U.S. states and municipal authorities updated or introduced rainwater/stormwater requirements and design guidance in the 2024–2025 timeframe; these legal changes are driving specification updates across design-build contracts in 2026.
-
Rebates and grants: Targeted rebate programs and conservation grant funds are accelerating retrofit adoption across public and community projects. These funding windows are often bounded by completion deadlines — timely program capture will be a decisive 2026 capability.
-
Industry events and knowledge transfer: Technical symposiums and consensus-body calls scheduled across 2025–2026 are important venues for shaping standards and building the relationships that determine specification lists.
Strategic recommendations for 2026 (prioritized actions)
-
Make compliance and certification a minimum viable requirement for new product introductions — allocate budget and engineering resource for standards-ready releases in H1–H2 2026.
-
Shift sales incentives to land larger integrated contracts (systems + service) rather than one-off hardware sales; design margin plans that recognize lifecycle revenue from O&M and monitoring.
-
Invest selectively in IoT and remote-service capabilities to enable performance contracts and reduce onsite OPEX for clients.
-
Pursue bolt-on M&A targets that add service capacity, regional installation footprints, or digital capabilities — use our M&A screening toolkit to test accretion scenarios.
-
Develop finance-friendly product bundles: structure pricing and delivery to align with grant and rebate calendars, enabling customers to access subsidies and accelerate purchase decisions.
-
De-risk supply chains through dual-sourcing of critical components and by developing local assembly hubs for heavy items such as tanks in priority markets.
-
Engage proactively with standards bodies and public agencies — early input into standards formation yields commercial advantage when mandates roll out.
-
Pilot urban and commercial reference projects that demonstrate emissions, cost, and resilience outcomes; publicize performance data to shorten sales cycles.
Data access and the “trailer” principle
We have intentionally shown the top-line market trajectory, the baseline CAGR (8.36%), and the macro strategic signals that matter for 2026 execution while withholding the granular, segmental revenue tables and regional/application splits in this introductory brief. The full PW Consulting Rainwater Harvesting Market report contains the detailed breakdowns — including type, application, and regional models; competitor revenue and share tables; and downloadable datasets designed for rapid scenario modeling in your planning systems. For procurement teams, product managers, and investors who require the granular numbers to model bids, run valuations, or size service rollouts, the full dataset and our custom advisory add-on are the logical next steps.
How to use this analysis in your 2026 planning cycle
-
Portfolio strategy: Use the topline growth and scenario outputs to set investment thresholds and prioritize which product lines to scale this year.
-
Commercial planning: Align sales territories and channel incentives to the markets and buyer types where integrated solutions are expected to drive the fastest revenue ramp.
-
Risk management: Integrate standards and regulatory timelines into bid gating criteria; avoid winning contracts that will be rendered non-compliant as standards evolve.
-
Investor diligence: Pair the topline projections with our M&A screening templates to stress-test acquisition targets and synergies under different adoption trajectories.
For teams ready to convert the 2026 strategic inflection into tangible growth, PW Consulting’s full Rainwater Harvesting Market report provides the granular inputs, scenario workbooks, and implementation playbooks required to operationalize these recommendations. Access to the complete datasets and our advisory services will accelerate the shift from strategic intent to delivered share.
For detailed analysis of this topic, please visit the official page: Rainwater Harvesting Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com