

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
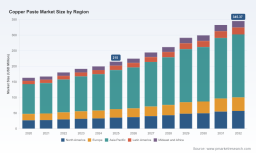
PW Consulting: Copper Paste Market to Reach USD 345.37 Million by 2032 at 7.0% CAGR

Copper Paste Market — Strategic Outlook for 2026 Decision-Makers
Executive summary
As PW Consulting’s senior industry advisory team, we position the copper paste market at a pivotal inflection for corporate strategy in 2026. Using a 2025 base year and a comprehensive historical window (2020–2025), our horizon analysis (2026–2032) demonstrates steady expansion underpinned by technology substitution, electronics miniaturization, and solar-cell metallization trends. The market—measured in USD Million—has expanded materially since 2020 and, under our central scenario, grows at a compound annual growth rate (CAGR) of 7.0% through the forecast window. This trajectory produces a meaningfully larger addressable market by 2032, while market concentration indicators (CR3 ≈ 30%, CR5 ≈ 40%) point to an industry structure that retains room for technology-driven entrants and regional champions.
Copper Paste Market
Why this matters for 2026 decision-making
- Cost-to-serve and raw material exposure: The sharp commodity swings seen into 2025—LME copper spot prices rising ~44% year‑over‑year to roughly $12,823/ton and silver surging past $94/oz—have already changed the economics of conductive pastes. Procurement, pricing, and product-cost models built on 2024 inputs are unlikely to be durable in 2026.
- Technology substitution windows: Rapid scale-up in copper-based metallization for photovoltaic (PV) cells and conductive alternatives across MLCC and PCB applications accelerates migration away from silver. Early movers who convert pilot successes into supply agreements will gain capture advantages.
- Supply-chain regionalization: Tariff regimes and policy actions through 2025 have fragmented sourcing logic. Companies must balance cost arbitrage with tariff exposure, logistics risk, and customer preferences for near-shore supply.
- Competitive positioning and M&A timing: The market’s moderate concentration leaves strategic space for focused M&A, JV structures, and commercial partnerships—especially where a supplier can demonstrate gigawatt-scale production capability or proprietary paste chemistries.
Data-driven snapshot (context, not a substitute for the full report)
From 2020 through 2025 the market expanded consistently, reflecting broad-based demand across electronics and solar applications. The PW Consulting model projects the market to continue growing at ~7.0% CAGR over 2026–2032 under a central-case demand scenario. This projection incorporates commodity price scenarios, adoption curves for copper substitution, capacity ramps among leading suppliers, and an assessment of regulatory tailwinds that favor lower-cost metallization routes. Importantly, concentration metrics indicate that the three largest suppliers control roughly 30% of market revenue—a dynamic that shapes negotiation leverage, technology diffusion, and the feasibility of new entrants achieving scale.
Copper Paste Market
Report contents — practical outputs for executive action
Our Copper Paste Market report is intentionally operational in orientation. Key deliverables include:
Copper Paste Market
- Market-sizing and growth drivers from 2020 through 2032 (base year 2025; currency USD Million), with probabilistic scenarios reflecting commodity volatility and regulatory shifts.
- Demand-by-application and demand-by-technology models (suitable for integration into corporate planning tools)—note: the public summary intentionally withholds the granular segment tables available in the full report.
- Supplier scorecards and capability maps that cover production scale, formulation IP, geographic footprint, working capital profiles, and go‑to‑market strengths.
- Commercial adoption case studies and de-risking playbooks: pilot-to-production conversion templates, qualification timelines, and sample off‑take contracting language for OEMs and materials buyers.
- Price-sensitivity and raw-material-pass-through models, including stress tests under copper- and silver-price extremes and tariff scenarios.
- Regulatory and trade-risk matrix (export controls, tariffs, and environmental compliance), and practical mitigation strategies for procurement and manufacturing leaders.
- M&A and partnership playbooks tailored to acquirers, minority investors, and strategic suppliers—including valuation sensitivities driven by capacity scalability and technology exclusivity.
Competitive landscape — what to watch in 2026
The competitive picture is best described as a mix of specialist formulators, materials producers, and incumbent electronics-materials houses. Our benchmarking emphasizes capability rather than absolute market shares in this public overview; full supplier metrics are reserved for report subscribers.
- DK Electronic Materials Co., Ltd. (Wuxi, China): Notable for recent transition to mass production of high-copper metallization pastes and commissioning of gigawatt-scale manufacturing lines. The supplier’s announced customer adoption in early 2026 for TOPCon production positions it as a potential accelerant for copper uptake in PV.
- Material Concept, Inc. (Japan): One of the earliest commercial suppliers positioning copper paste as a silver-paste alternative for solar cell wires and electrodes—an important proof point for substitution economics in prioritized PV segments.
- Tatsuta Electric Wire & Cable Co., Ltd. (Japan): Offers copper paste variants tailored to PCB EMI shielding, via filling, and cross-over protection—illustrating how application-specific formulations unlock downstream adoption.
- Shoei Chemical Inc. (Japan): Focuses on nickel and copper thick-film pastes for MLCC terminations, highlighting opportunities where paste chemistry intersects tightly with ceramics processing.
- Heraeus Electronics (Germany): Major European player supplying conductor pastes for high-temperature applications—positioned for industrial and power electronics where thermal stability is critical.
- Sumitomo Metal Mining Co., Ltd. (Japan): Supplies fine copper powders and thick-film pastes and remains strategically important for powder supply and upstream integration.
Implications: suppliers with demonstrated scale, validated customer references, and upstream control of powder or paste chemistry will command premium commercial terms. Conversely, chemistry innovators without scale are attractive M&A targets for strategic consolidators seeking differentiated formulations and faster qualification cycles.
Market dynamics and structural risks
- Commodity volatility: The late‑2025 spike in copper and silver prices materially alters substitution incentives. Our models show multiple adoption inflection points where copper becomes the default alternative in specific PV and electronics use-cases as silver and copper ratios change.
- Trade policy and sourcing: Cumulative tariff measures through 2025 have already reshaped logistics strategies; companies face a choice between lowest-cost sourcing and tariff/sovereign risk mitigation via near-shoring or dual-sourcing.
- Qualification timelines: Transitioning from silver to copper in high-reliability segments requires multi-stage qualification and accelerated reliability testing—an often-underestimated time and CAPEX commitment that can create first-mover advantages or delays.
- Recycling and feedstock availability: As demand shifts, recycled copper streams and powders will become a strategic feedstock, with implications for traceability, quality control, and ESG reporting.
Six practical moves for leaders in 2026
- Stress-test product portfolios: Run scenario analyses using our price-sensitivity models to understand margin impact across likely copper and silver price paths; prioritize SKUs for reformulation or hedging.
- Commission targeted pilots with scaled suppliers: Engage partners that can demonstrate gigawatt-equivalent throughput to shorten commercialization cycles—emphasize co-funded qualification programs to share execution risk.
- Restructure procurement contracts: Move from fixed-price raw-material exposure to indexed, pass-through or collar arrangements tied to LME and silver benchmarks.
- Diversify supplier base strategically: Create a dual-sourcing architecture that blends incumbent relationships with smaller, technology-focused suppliers able to supply differentiated chemistry.
- Consider inorganic moves where vertical gaps exist: Target acquisitions that provide filler powders, proprietary formulation IP, or regional manufacturing footprints to neutralize tariff disadvantages.
- Integrate regulatory and ESG screening: Embed trade-risk and environmental compliance checks into supplier selection and product qualification to reduce future non-tariff barriers to market.
Next steps — where to get the full intelligence
This note is a strategic preview. The full PW Consulting Copper Paste Market report contains the granular segmentation tables, regional and application-level demand forecasts, supplier scorecards with quantified capacity and revenue estimates, and downloadable financial and procurement models that operational teams can plug into 2026 planning cycles. For executives preparing budgets, procurement frameworks, or M&A pipelines, the detailed appendices and scenario-models in the full report are purpose-built to shorten decision timelines and reduce execution risk.
In a market redefined by commodity shocks, tariffs, and rapid technology transfer, the right combination of supplier partnerships, commercial terms, and operational adjustments made in 2026 will determine who captures scale and who reacts from a position of vulnerability. PW Consulting’s full study turns these imperatives into step‑by‑step actions, validated supplier assessments, and model-driven decision tools—designed for immediate use in board-level strategy sessions and procurement negotiations.
For detailed analysis of this topic, please visit the official page: Copper Paste Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com