

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Cellulose Acetate Market to Reach USD 8.37 Billion by 2032 at 4.6% CAGR

Cellulose Acetate Market 2026: A Strategic Preview for Decision-Makers
Executive snapshot
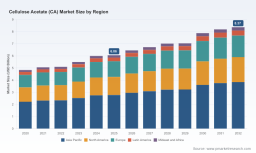
Between 2020 and 2025 the global Cellulose Acetate (CA) market expanded from roughly USD 4.9 billion to just over USD 6.0 billion, reflecting recovery dynamics and shifting end‑use demand patterns. Our 2026–2032 outlook projects the market continuing to grow at a mid-single‑digit pace (a 4.6% CAGR across the forecast period), reaching an estimated market size north of USD 8 billion by 2032. For executives preparing capital allocations, pricing strategies, or M&A plans this trajectory signals steady, structurally supported growth — not a runaway boom — and requires nuanced, targeted responses rather than broad-brush bets.
Cellulose Acetate (CA) Market
Why this study matters for 2026 decision cycles
-
Timing: 2026 is a pivot year where raw material volatility, regulatory shifts, and novel sustainable grades converge to reshape supplier economics and go‑to‑market choices. Decisions made this year on contracts, capacity, and product roadmaps will materially affect unit economics into the early 2030s.
Cellulose Acetate (CA) Market -
Complexity: The CA value chain sits at the intersection of commodity acetyls, specialty cellulose feedstocks, and downstream markets (textiles, filtration, film). That creates multi‑vector risk and opportunity that cannot be managed with a single lever (e.g., price alone).
Cellulose Acetate (CA) Market -
Signal vs noise: Public headlines (raw material spikes, export control notices) are important, but their strategic implications differ by application and region. Our research decodes which signals require tactical responses and which require structural changes.
Market trajectory and structural drivers
Two structural forces underpin the CA market outlook. First, demand diversification: while traditional filament and filter uses remain substantial, increasing adoption in high‑performance textiles and engineered films is raising average selling prices and shifting the product mix toward differentiated grades. Second, supply‑side dynamics: feedstock availability, regional cost curves, and the pace of specialty grade rollouts by incumbent producers are shaping competitive advantage.
The resulting growth profile — modest but persistent — implies that participants who capture differential margin through grade innovation, integrated feedstock strategies, or selective capacity moves will outperform peers that attempt to compete purely on volume.
Key dynamics and near‑term risks
-
Raw material pressure: Acetyl intermediates have recently shown acute price movement in major basins. These oscillations translate quickly into cost‑push pressure for CA producers and create margin squeeze unless pass‑through mechanisms or hedges are in place.
-
Policy and trade uncertainty: Export controls and shifting regulatory settings in supplier countries can reconfigure trade flows on short notice. Scenario planning for both supply interruptions and rapid re‑routing of material flows is now a hygiene factor for procurement teams.
-
Innovation & substitution risks: New sustainable cellulose‑based fibers and bio‑sourced acetate grades are emerging commercially. Early entrants that secure offtake agreements with fashion and high‑performance textile customers can capture premiums but must manage scale‑up and quality consistency risks.
-
Demand composition: End‑market dynamics are heterogeneous. Certain applications exhibit structural decline or substitution risk, while others are expanding. This divergence elevates the importance of SKU and channel‑level profitability analysis.
Competitive landscape — what to watch
The CA market is populated by global chemical majors, specialty cellulose houses, and regional producers with distinct strategic plays. Competitive dynamics are best understood through three lenses: feedstock control and integration, product breadth (commodity vs specialty), and go‑to‑market focus (industrial vs textile vs filtration). Below are strategic profiles of the core participants we track:
-
Eastman Chemical Company — Eastman is moving aggressively into value‑added and sustainable acetate fibers. Their recent launch of a lighter, sustainable cellulose acetate fiber at major textile events signals a deliberate push to capture textile and apparel premium segments. For competitors, Eastman’s combination of brand, distribution channels in specialty textiles, and product innovation raises the bar on performance‑grade offerings.
-
Celanese Corporation — As a major global producer across the acetyl chain, Celanese’s commercial levers include price leadership, scale logistics, and deep exposure to cigarette‑filter supply chains. Recent broad price actions illustrate how vertically integrated players can use commercial policy to preserve margins during raw material stress — a capability that smaller suppliers may lack.
-
Daicel, Solvay, Mitsubishi Chemical — These incumbents compete across specialty fibers, films, and derivatives. Their strengths lie in process know‑how, regulatory compliance in demanding markets, and long‑standing customer relationships. Expect continued emphasis on specialty derivatives and service bundles for automotive, industrial, and high‑end textile applications.
-
Cerdia, Sappi, Rayonier Advanced Materials, Borregaard — Historically cellulose‑focused companies are positioning cellulosic upstream advantages as a differentiator. Their strategic emphasis is on raw material sustainability credentials, traceability, and enabling customers’ circularity targets.
-
Sichuan Push Acetate — Regional champions in Asia remain crucial to global supply balancing. Their cost competitiveness and domestic customer base make them natural swing suppliers in a tight market; however, export policy and feedstock volatility influence their cross‑border role.
Recent commercial moves that matter
-
Price adjustments across the acetyl chain by major suppliers reflect immediate cost pressures and demonstrate how quickly upstream conditions filter into CA pricing.
-
New fiber product launches targeted at sustainable apparel indicate a bifurcation of the market: commodity CA for traditional uses versus premium bio‑sourced and performance grades for apparel and specialty applications.
Strategic playbook for 2026
Leaders should approach 2026 with a balanced set of tactical and structural initiatives. Below are high‑value actions we recommend for executives mapping resource allocation and risk mitigation:
-
Short‑term procurement resilience — Lock in flexible contracts (volume bands with rollback/step mechanisms), expand alternative sourcing options, and implement dynamic hedging linked to regional acetyl indices. Tactical inventory buffers in critical nodes may be warranted where lead times and substitution options are limited.
-
Product differentiation and premium capture — Fast‑track development of bio‑based and high‑performance acetate grades that address textile customers’ sustainability mandates. Invest in joint development agreements with key fiber/textile brands to secure early demand and higher ASPs.
-
Margin management — Deploy SKU profitability assessments to prioritize production toward the most resilient margins; consider selective de‑commoditization of product portfolios.
-
Strategic partnerships — Evaluate downstream partnerships (filament tow producers, apparel brands) to lock in offtake and co‑finance scale‑up of specialty grades. Consider minority investments in upstream cellulose supply to improve feedstock visibility.
-
Regulatory & trade playbooks — Maintain active monitoring of export control developments and design rapid response logistics options. Scenario drills covering short‑term export restrictions or demand shocks should be part of board‑level risk reviews.
-
M&A & capacity moves — Given the moderate concentration and differentiated regional cost curves, selective bolt‑on acquisitions in specialty grades or regional feedstock assets can unlock near‑term synergies. Prioritize deals with clear integration paths and customer retention plans.
What the full PW Consulting CA report delivers (practical, executable content)
Our full study is designed for immediate operational use by strategy, procurement, and commercial teams. Key deliverables include:
-
Proprietary market sizing and forward models with scenario toggles (base, downside, upside) covering 2026–2032.
-
Supply‑chain maps and cost‑curve benchmarks by production basin, and sensitivity analyses to acetyl and cellulose feedstock indices.
-
Price and margin impact calculators you can plug into internal P&L models.
-
Company scorecards and playbooks for the leading suppliers (capability heatmaps, strategic moves, and likely responses to stress scenarios).
-
Commercial playbooks for offtake negotiation, channel segmentation, and value‑based pricing for specialty grades.
-
Regulatory risk register and recommended contingency protocols for trade disruptions and export control scenarios.
-
Technology & sustainability roadmap outlining near‑term commercial readiness for bio‑sourced and recycled inputs.
How to use this preview
This preview surfaces the high‑value signals and strategic implications we believe will determine winners and laggards through 2026 and into the next planning cycle. It intentionally avoids publishing detailed segmentation tables and company volume matrices — those granular diagnostics are included in the full report and accompanying data pack so your team can run tailored financial scenarios and supplier negotiations.
Final recommendation
For executives planning 2026 capital, commercial, or procurement decisions: treat the CA market as a structurally growing sector where differentiation, feedstock strategy, and nimble commercial execution will create disproportionate value. The modest 4.6% mid‑cycle CAGR belies the pockets of premium capture available to firms that align product innovation, integrated sourcing, and customer co‑creation. Use 2026 to lock in optionality — not to place binary bets.
To access the full dataset, segmented models, and operational playbooks needed to convert these insights into concrete actions, consult PW Consulting’s complete Cellulose Acetate Market study and the interactive data workbook accompanying it.
For detailed analysis of this topic, please visit the official page: Cellulose Acetate (CA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com