

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Hemostasis and Tissue Sealing Agents Market Growing at 8.2% CAGR

Hemostasis and Tissue Sealing Agents Market — Strategic Preview for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present an executive preview of our authoritative market study on Hemostasis and Tissue Sealing Agents. This briefing synthesizes the strategic implications of the study for executives preparing 2026 roadmaps—commercial, regulatory, and investment—while intentionally withholding the granular segment tables and proprietary models reserved for the full report.
Hemostasis and Tissue Sealing Agents Market
Why this market matters in 2026
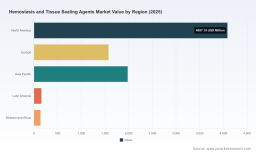
The hemostasis and tissue sealing space has evolved from a niche adjunct to a core component of perioperative and emergency medicine strategy. In our base-year assessment (2025), the global market reached approximately USD 7.94 billion and is forecast to expand at a compound annual growth rate of 8.2% through the 2026–2032 horizon, reaching a multi‑billion-dollar valuation by 2032. That pace of expansion signals a sustained structural opportunity driven by demographic change, surgical volume rebound, expanded minimally invasive care pathways, and continuous product innovation across biomaterials, delivery systems, and endoscopic applications.
Hemostasis and Tissue Sealing Agents Market
Where value pools are forming — strategically, not granularly
-
Technology convergence: Innovations in bioadhesives, fibrin-based sealants, absorbable matrices and hydrogel chemistries are redefining clinical use cases. Products that combine rapid hemostasis with tissue-compatibility and resorption profiles are being prioritized by hospitals seeking to reduce re-operation and complication rates.
Hemostasis and Tissue Sealing Agents Market -
Procedure-driven demand: The interplay between rising surgical volumes (general, cardiovascular, neuro, orthopedic and specialty interventions) and the need for improved intraoperative efficiency is creating differentiated demand for delivery formats—sprays, gels, powders and patches—that influence purchasing decisions and OR workflows.
-
Cost and value debates: While per‑unit pricing differs markedly across technologies, payors and procurement teams are increasingly focused on total episode-of-care economics. Devices and materials that demonstrably shorten length-of-stay or reduce readmission risk are gaining preferred-pathway status in many health systems.
-
Regulatory and reimbursement context: Continued activity on 510(k) clearances and pathway optimization, particularly in the U.S., is lowering time-to-market for iterative improvements. Simultaneously, the common inclusion of hemostats as part of bundled procedural codes alters the commercial calculus—favoring solutions that can generate identifiable downstream efficiencies.
Competitive landscape — leaders, challengers and product playbooks
The market is meaningfully concentrated, with the three largest players commanding a majority share and the top five controlling well over half of the commercial value pool. This concentration creates both barriers and white spaces: sizable incumbents maintain distribution reach, integrated supply chain advantages and broad surgical portfolios, while nimble specialists advance novel chemistries and focused clinical evidence to secure adoption in high‑value niches.
-
Baxter International: A diversified portfolio that spans fibrin sealants, hemostatic matrices and topical thrombin formulations positions Baxter to serve multiple surgical specialties and institutional purchasing models. Their product depth supports cross-selling into existing supply relationships.
-
Johnson & Johnson (Ethicon): With recent launches expanding the fibrin spray and traditional hemostat portfolio, Ethicon leverages broad OR influence. Market entrants should anticipate strong OEM and contracting activity where Ethicon competes.
-
Medtronic: Endoscopic hemostasis systems are a key differentiator—lessons from endoscopy translate to minimally invasive specialties and inform device-plus-consumable business models.
-
Becton, Dickinson and Company: Collagen-based, absorbable matrices are core to traditional hemostatic use-cases; BD’s depth in procedural consumables supports integrated purchasing conversations.
-
Teleflex: Recent regulatory expansion of indications for certain hemostatic devices broadens clinical usage scenarios and underscores the commercial upside of targeted 510(k) strategies.
-
Specialized innovators (e.g., Cresilon, Medcura): New hydrogel and cellulose-derivative platforms, particularly those avoiding animal-derived components, are carving out distinct value propositions in external and temporary bleeding control.
For new entrants and investors, the strategic choice is between (a) partnering with incumbents to leverage distribution and contracting scale, (b) pursuing niche clinical proof and targeted hospital penetration in high-margin use-cases, or (c) building vertically integrated offerings when proprietary delivery systems materially enhance clinical outcomes.
Regulatory, reimbursement and supply fundamentals
-
Regulatory pathways: The U.S. 510(k) pathway remains active for many hemostatic technologies, rewarding incremental innovations that are backed by targeted clinical or bench data. Strategic regulatory planning—sequencing clearances in priority markets and aligning labeling claims with OR practice—is a high-leverage activity.
-
Reimbursement environment: Hemostatic agents are often reimbursed as integral to the surgical procedure under common procedural coding systems. This creates a procurement environment where the burden of proof shifts from fee-for-product to demonstrable contribution to episode value (e.g., reduced transfusions, fewer reoperations).
-
Raw materials and manufacturing risk: Novel plant‑based hydrogels and proprietary cellulose derivatives are attractive on biocompatibility and public-acceptance grounds, but they introduce supply concentration and quality risk. Likewise, animal-derived components present sourcing and regulatory considerations that must be managed through dual-sourcing plans and robust CMC documentation.
Practical, action-oriented contents in the full PW Consulting study
The full report provides the tactical tools decision-makers need in 2026. Highlights include:
-
Scenario-based demand models: Dynamic forecasts across surgical adoption curves under multiple elective‑care rebound and reimbursement scenarios, enabling capital planning and sales-target setting.
-
Commercial playbooks: Product positioning matrices, hospital procurement negotiation guides, and account tiering frameworks for converting OR preference cards into repeat revenue.
-
Regulatory and clinical development roadmaps: Recommended evidence-generation strategies to support label expansion, payer conversations, and faster market acceptance—including suggested trial endpoints tied to episode-of-care economics.
-
Supply chain and manufacturing assessment: Sourcing risk heatmaps for key raw material classes, and scale-up pathways to support both hospital-scale demand and ambulatory procedural growth.
-
M&A and partnership screen: A prioritized list of strategic targets and alliance archetypes—technology enablers, regional distributors, and complementary device platforms—with valuation heuristics and integration risk markers.
-
Pricing sensitivity and procurement modeling: Tools to simulate hospital P&L impacts from various pricing scenarios, enabling commercial teams to craft evidence-based pricing and contracting strategies.
Implications for corporate strategy in 2026
-
For incumbents: Protect and extend clinical leadership through evidence that links product use to measurable reductions in complications and cost-of-care. Use portfolio breadth to bundle offerings and defend hospital formularies.
-
For growth-stage companies: Focus commercialization on discrete, high-value clinical use-cases where your technology delivers unique outcomes. Consider co-development with OEMs to accelerate adoption in endoscopic and minimally invasive procedures.
-
For investors and acquirers: Seek opportunities where product innovation is paired with scalable reimbursement narratives and low-to-moderate regulatory friction. Prioritize assets with defensible IP and a clear path to integration with existing OR procurement workflows.
Signals to watch through 2026
-
Regulatory clearance timelines and label expansions that broaden indications of use—these will change addressable opportunity windows.
-
Hospital procurement behavior shifting from unit-price focus to episode-of-care metrics—early adopters will drive peer-system replication.
-
Clinical data demonstrating meaningful reductions in transfusion, re-bleeding, or re-operation rates—such studies accelerate formulary uptake and payer interest.
-
Supply shocks or raw material cost inflections—companies with resilient sourcing strategies will be advantaged.
Concluding recommendation — align strategy to demonstrated clinical and economic value
In 2026, the Hemostasis and Tissue Sealing Agents market offers a compelling growth runway—our topline forecast shows robust expansion driven by both innovation and procedural demand. Yet, the decisive battleground will not be limited to chemistry or delivery form alone: companies and investors who can translate product performance into quantifiable episode-of-care benefits, navigate regulatory and procurement dynamics, and secure resilient supply chains will capture disproportionate value.
PW Consulting’s full Hemostasis and Tissue Sealing Agents Market report delivers the granular segmentation, competitive share breakdowns, pricing ladders, and executable playbooks that executives need to convert this opportunity into profitable growth. For access to the complete intelligence set—detailed segment tables, proprietary models, and tailored advisory options—visit our report page or contact our research desk to schedule a strategic briefing.
For detailed analysis of this topic, please visit the official page: Hemostasis and Tissue Sealing Agents Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com