

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Anti-Counterfeiting Packaging Market to Grow at 11.79% CAGR (2026-2032)

Anti-Counterfeiting Packaging Market: Strategic Imperatives for 2026 Decision‑Makers
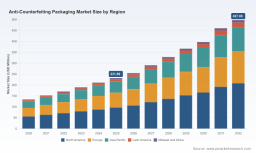
As global supply chains reconfigure and regulatory pressures intensify, anti‑counterfeiting packaging has shifted from a compliance checkbox to a strategic enabler. PW Consulting’s latest market study — anchored on a 2025 base year and a 2026–2032 forecast horizon — reframes how executives must think about product integrity, brand protection, and packaging as a data layer across the product lifecycle. The headline: after a sustained expansion from USD 133.86 million in 2020 to USD 231.89 million in 2025, the market is forecast to continue at a strong compound annual growth rate (CAGR) of 11.79%, reaching an estimated USD 497.86 million by 2032. For corporate leaders formulating 2026 budgets, sourcing strategies, and M&A pipelines, those numbers translate into timing, scale and risk-management imperatives you cannot afford to ignore.
Anti-Counterfeiting Packaging Market
Why this PW Consulting study matters in 2026
- Actionable translation of macro growth into tactical choices: procurement levers, tech pilots, and tier‑one supplier selection criteria linked to ROI models calibrated for a market growing at ~12% annually.
- Regulatory foresight that converts compliance obligations into competitive advantage — identifying where early investment in sustainable, serialized, or tamper‑evident solutions yields long‑term cost avoidance and market access.
- Vendor diligence and partner maps that reduce execution risk when integrating covert/visible security features into existing packaging lines.
- Scenario planning and stress tests that help boards and CFOs evaluate capital allocation under alternative regulatory and raw‑material cost trajectories.
Macro trajectory and strategic implications
The market trajectory is clear. Between 2020 and 2025, the industry roughly doubled in scale, reflecting rising investment by pharmaceutical, food & beverage, personal care and electronics OEMs to protect revenue and manage liability. The forecast through 2032 shows continued acceleration, driven by converging forces: stricter product authentication regulations, broader adoption of smartphone‑verifiable features and digital on‑pack credentials, and growing consumer sensitivity to provenance and sustainability.
Anti-Counterfeiting Packaging Market
For 2026 planning this implies three immediate considerations: (1) allocate a larger, dedicated budget line for anti‑counterfeiting initiatives rather than ad‑hoc funding from packaging or quality teams; (2) prioritize modular, upgradeable security solutions that can be retrofitted as standards (e.g., digital product passports) evolve; and (3) use the market growth curve to justify early pilots with measurable KPIs tied to shrinkage, chargebacks, and recall avoidance.
Anti-Counterfeiting Packaging Market
Demand drivers and inflection points to monitor
- Regulatory tightening: New and expanding EU mandates — from recycled content and EPR schemes to serialization and Digital Product Passport requirements — are reshaping packaging specifications and holding producers accountable for traceability. These rules convert a previously optional brand protection expense into a regulatory and market access prerequisite.
- Technology convergence: Solutions span visible holography, tamper‑evidence, RFID/serialization, forensic markers and emerging quantum‑secure tags. A practical 2026 strategy is to deploy layered defenses rather than one singular technology; digital authentication tied to consumer devices is now table stakes for many segments.
- Sustainability pressures: Material innovation — e.g., recyclable fibre‑based tamper‑evident labels and lightweight closures — forces a trade‑off analysis between security efficacy and circularity. Procurement teams must validate security performance on sustainable substrates and verify compliance with single‑use plastics and recycled‑content mandates.
- Supply‑side dynamics: Raw material innovations and vendor roadmaps are altering unit economics. Brands should expect periodic price and availability shocks for specialty substrates and inks, and incorporate supplier redundancy and long‑lead procurement practices into 2026 plans.
What’s in the PW Consulting report (practitioner‑level detail)
- Executive playbooks: prioritized roadmaps for pharmaceutical, FMCG and durables manufacturers outlining low‑friction pilots, KPIs, and 12‑ and 36‑month deployment sequences.
- Technology decision matrices: comparative frameworks that score security technologies on authentication robustness, cost per pack, scalability, and sustainability compatibility.
- Vendor scorecards and sourcing templates: an actionable shortlist of incumbent and specialist suppliers, negotiation benchmarks, contract clauses for IP and data rights, and transition checklists for packaging line conversions.
- Regulatory impact models: localized compliance matrices that translate new and pending rules into packaging spec changes, cost delta estimates, and time‑to‑market constraints.
- Commercial and M&A playbooks: valuation filters, synergy capture plans, and integration red flags for buyers seeking to acquire capability‑rich security packaging players.
- Scenario analyses and stress testing: downside and upside cases based on regulatory shock, raw material volatility, and rapid tech substitution, with recommended contingency actions.
Competitive landscape — who to watch and why
The sector is characterized by a mix of specialized security innovators, packaging incumbents integrating secure features, and regional players with execution strengths in cost‑sensitive markets. The market concentration remains modest: the top competitors together account for roughly a quarter of the market, indicating opportunity for focused partners and niche innovators.
- AlpVision S.A. (Switzerland) — https://alpvision.com/ Profile: Cryptoglyph and fingerprint‑based covert solutions verifiable by standard smartphones. Strategic takeaway: Ideal for brands needing consumer‑centric authentication layers that do not require specialized hardware; consider pilots for high‑value SKUs where consumer engagement yields direct anti‑counterfeiting ROI.
- Origin Pharma Packaging (UK) — https://originltd.com/ Profile: ISO 15378‑compliant pharmaceutical primary packaging with tamper‑evident and child‑resistant features. Strategic takeaway: A go‑to partner for pharma firms needing regulatory alignment and tight quality control; prioritize for products with strict serialization and tamper‑evidence requirements.
- Quantum Base (UK) — https://quantumbase.com/ Profile: Q‑ID® quantum‑secure optical tags and scanner ecosystem for packaging authentication. Strategic takeaway: Represents leading edge in cryptographic, physically unclonable tags; evaluate for long‑horizon investments where unbreakability and provenance certification are mission‑critical.
- Shosky Security (China) — https://shoskysecurity.com/ Profile: Customized tamper‑evident strips, tapes and bags for high‑security packaging. Strategic takeaway: Competitive cost and customization strengths for mass production; consider as a secondary manufacturing partner to diversify sourcing.
- NovaVision Inc. (US) — https://www.novavisioninc.com/ Profile: Holographic security labels, tamper‑evident tapes and seals. Strategic takeaway: Strong in visible security elements; useful where shelf‑level deterrence and brand perception are priorities.
- Holostik India Limited (India) — https://www.holostik.com/ Profile: Holographic films, tamper‑proof labels, and shrink sleeves. Strategic takeaway: Rapid product innovation and regional market presence make Holostik a candidate for volume programs and sustainability co‑development (see recent eco‑product launches).
- Precintia (Spain) — https://www.precintia.com/ Profile: Passive security seals, tamper‑evident products and traceability solutions. Strategic takeaway: Strong in sealed logistics and traceability for high‑value shipments — useful for cold‑chain and pharma distribution layers.
- ProAmpac (US) — https://www.proampac.com/ Profile: Recyclable secure and tamper‑evident flexible packaging solutions. Strategic takeaway: Combines security with circularity; evaluate for sustainable packaging roadmaps and large CPG rollouts.
Recent industry moves worth noting
- May 2026 — Holostik launched an eco‑friendly Paperogram hologram and showcased sustainable anti‑counterfeiting solutions at major trade shows, signaling accelerated convergence of security and circularity (Holostik press releases, May 2026).
- April–June 2026 — ProAmpac exhibited sustainable secure packaging at Interpack 2026, underscoring a sectoral move to reconcile tamper‑evidence with recyclability (ProAmpac press release, June 2026).
- March 2026 — Holostik updated its product catalog to expand holographic shrink sleeves and mono‑carton anti‑counterfeiting options for pharma and FMCG (Holostik press release, March 2026).
Practical recommendations for 2026 decision cycles
- Establish a cross‑functional anti‑counterfeiting steering team (procurement, quality, packaging, legal, sustainability) to reduce siloed decisions and speed deployments.
- Run at least two technology pilots in 2026: one focused on consumer‑verifiable, low‑cost authentication (smartphone readable), another on high‑security tags for supply‑chain endpoints (forensic/quantum solutions).
- Embed sustainability KPIs into vendor selection — require validated performance on recyclable substrates and compatibility with Digital Product Passport requirements.
- Negotiate supplier contracts with modular pricing and upgrade clauses to avoid vendor lock‑in as standards evolve.
- Use the report’s scenario models to stress‑test CapEx plans against regulatory acceleration or raw material disruption.
- Consider tuck‑ins in regions where local execution and speed to market are decisive; target niche innovators with defensible IP rather than broad‑based packaging incumbents for capability gaps.
How to use the proprietary PW dataset
PW Consulting’s dataset — with annual market sizing from 2020 through a 2032 forecast — is structured for direct use in investment memos, procurement modeling and board presentations. Use the total market trajectory to calibrate TAM/SAM in business cases, apply the technology matrices to lower technology adoption risk, and leverage the regulatory impact models to quantify compliance costs. For granular regional, type and application splits, vendor market shares and the full competitive scoring, consult the complete study — the exact segmental allocations and supplier benchmarks are available exclusively in the full report.
In 2026, choices around anti‑counterfeiting packaging are consequential: they affect market access, brand trust, regulatory compliance and profitability. PW Consulting’s study equips decision‑makers with the quantitative trajectory, qualitative context and executable playbooks needed to convert that risk into sustained competitive advantage.
To access the full report, methodology, and downloadable datasets — including regional, type and application breakdowns and the complete vendor scorecards — please visit our report page or contact your PW Consulting account representative.
For detailed analysis of this topic, please visit the official page: Anti-Counterfeiting Packaging Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com