

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Water Quality Analyzer Market to hit USD 592.24M by 2032 at 4.9% CAGR

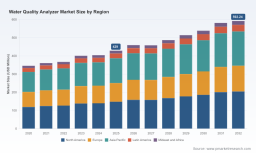
Water Quality Analyzer Market — Strategic Preview for 2026 Decision‑Making
As PW Consulting’s senior industry analyst, I present a concise, strategic preview of our Water Quality Analyzer Market research — a timely briefing designed to shape boardroom choices, procurement cycles, and R&D prioritization in 2026. Built on a 2025 base year and covering historical performance from 2020–2025 with a detailed forecast for 2026–2032, the study models the market’s trajectory (CAGR 4.9%) and provides executable intelligence for commercial leaders operating in monitoring hardware, analytical instrumentation, and services tied to municipal, industrial, and marine water systems. All monetary figures in this preview are reported in USD Million.
Water Quality Analyzer Market
Why this research matters for 2026
-
Momentum and inflection: The global market expanded from approximately USD 345.7M in 2020 to USD 429.0M in 2025, with the model projecting continued growth into the forecast horizon — reaching an estimated USD 459.5M in 2026 and approaching the high‑hundreds by 2032. That trajectory underpins a steady, investible market that rewards differentiation in sensing accuracy, integration, and service economics.
Water Quality Analyzer Market -
Policy and procurement windows: Regulatory updates and public procurement cycles are creating near‑term demand signals (see dynamics section). Firms that align product roadmaps and commercial pipelines to these windows can materially accelerate revenue recognition in 2026.
Water Quality Analyzer Market -
Service as a margin lever: With modest market concentration (the top three and five players together do not dominate the space), there is room for specialized vendors and service providers to capture aftermarket and analytics revenue — a critical consideration for 2026 go‑to‑market playbooks.
Market dynamics shaping 2026 tactical choices
-
Regulatory calibration: The industry is being reshaped by testing standard updates and alternative method approvals. Notably, the U.S. EPA’s approval of alternative testing methods for certain effluent contaminants (effective January 2025) changes compliance verification workflows and can shorten the adoption curve for rapid/field methods.
-
Standards continuity: Key ASTM methods for analytes such as manganese and hardness were reaffirmed in 2025. Vendors that can demonstrate traceable performance against these methods will enjoy a procurement advantage in regulated tenders.
-
Technology push: Suppliers are launching ultra‑trace sensors and more capable multi‑input transmitters (for example, late‑2025 product introductions that push dissolved oxygen sensitivity into sub‑ppb ranges and combine multiple inputs for continuous monitoring). This is accelerating demand for higher‑value sensing platforms and is creating a two‑tier market for basic monitoring versus precision, ultra‑pure and corrosion‑sensitive applications.
-
Digital convergence: IoT‑enabled multi‑parameter devices and cloud analytics are migrating from pilot projects to full deployments. Vendors that combine rugged hardware with a subscription analytics model will be better positioned for recurring revenue in 2026 and beyond.
-
Procurement activity: Recent public tenders and institutional buying cycles indicate pockets of near‑term demand — an important signal for sales planning and production scheduling for Q2–Q4 2026.
What the full PW Consulting report delivers (practical outputs)
-
Rigorous market sizing and time‑series forecasting (2020–2032) with base‑year 2025 calibration and scenario variants for regulatory tightening and accelerated digital adoption.
-
Segmentation frameworks by region, product type (portable, benchtop, online/inline) and end‑use (municipal, industrial/wastewater, marine/offshore) with methodology notes (note: detailed segment worksheets are available in the full report package).
-
Competitive profiles and benchmarking: vendor capability matrices, product roadmaps, distribution footprints, and aftermarket service models for leading and emerging players.
-
Procurement intelligence: tender language templates, unit economics for CapEx vs. O&M procurement choices, and an RFP checklist that aligns testing standards and acceptance criteria with technical specifications.
-
Commercial playbooks: customer journey maps, channel strategy options, pricing archetypes, and an eight‑quarter GTM sprint plan tailored to vendors or buyers.
-
Decision tools: downloadable Excel forecast models, sensitivity analyses, and a priority matrix that ranks growth initiatives by CAPEX, time‑to‑market, and ROI.
-
Risk register and mitigation options covering supply chain disruption, sensor obsolescence, and regulatory non‑conformance risks.
Competitive landscape — focused analysis
-
Market structure: The sector shows moderate concentration; the leading three and five firms together represent a material but not overwhelming share of market revenue, leaving room for specialized entrants and regional champions to scale through focused value propositions.
-
Company spotlights:
-
Hach (Loveland, Colorado): A legacy instrumentation player with a broad offering across multi‑parameter meters and online systems. Their strengths are deep channel relationships with municipal customers and an established chemistry and consumables business that supports recurring revenue.
-
ABB (Zurich): Known for industrial automation and process analytics, ABB has recently expanded its dissolved oxygen sensor family and multi‑input transmitters to address ultra‑precise measurement needs. These product moves are targeted at process industries and ultra‑pure water applications where trace performance and transmitter integration matter.
-
Process Insights (Germany): Focused on online analytics for TOC, COD, BOD, TN and toxicity, they play to the industrial and wastewater segments where continuous process compliance and effluent control are priorities.
-
-
Recent developments and their strategic signals:
-
Late‑2025 ultra‑trace sensor launches reflect a product premiumization trend and point to R&D areas that will command higher ASPs and stickier service contracts.
-
Public tenders issued across government agencies are compressing sales cycles for compliant vendors and elevating the importance of pre‑qualified supplier lists.
-
Smaller vendors updating IoT/multi‑parameter offerings indicate competitive pressure along the digital and connectivity dimension — an axis that often determines selection in decentralized or remote monitoring projects.
-
Actionable recommendations for 2026 planning
-
Product strategy: Prioritize a two‑track roadmap — enhance a core, cost‑competitive line for high‑volume municipal deployments while fast‑tracking an ultra‑precision line (sensors + validated transmitters) for industrial and pharma/microelectronics customers who will pay a premium for trace performance and certification.
-
Commercial alignment: Coordinate tender response capability with manufacturing lead times. For firms pursuing large public contracts, pre‑qualify manufacturing and QC documentation now to meet mid‑2026 bid deadlines and avoid reactive price concessions.
-
Service & software: Build subscription packages that bundle sensors, remote diagnostics, and analytics. This reduces procurement friction for buyers and smooths revenue volatility through recurring income — an attractive outcome for investor‑owned vendors planning funding rounds in 2026.
-
Regulatory & validation: Invest in method validation labs and third‑party certification against ASTM and EPA‑recognized methods; this will materially shorten procurement decision cycles where compliance evidence is a gating factor.
-
Mergers & partnerships: For companies seeking inorganic growth, target service‑heavy players and software specialists to accelerate transition into recurring revenue models rather than only adding hardware volume.
-
Scenario planning: Prepare for a moderate‑growth base case (aligned with the study’s 4.9% CAGR), while stress‑testing for faster digital adoption or accelerated regulatory tightening that could lift demand for higher‑value analyzers sooner than anticipated.
How to use this preview — and where to go next
This briefing is intentionally selective: it demonstrates the analytical depth and the decision support embedded in the full PW Consulting study while withholding segment‑level breakout tables and certain vendor financials to preserve the report’s commercial value. The complete package includes the full segmentation worksheets, interactive Excel models, granular regional and application forecasts, vendor scorecards, and a customizable slide deck for executive briefings.
If your agenda for 2026 includes product launches, public tender capture, M&A evaluation, or a move into subscription analytics for water monitoring, the full report and our advisory services will accelerate actionable choices, mitigate procurement risk, and quantify the ROI of competing strategies. PW Consulting offers tailored briefings and model walkthroughs to help executive teams convert the research into a 90‑day implementation plan.
For pragmatic strategic decisions in 2026 — from R&D allocation and channel coverage to tender readiness and aftermarket economics — this research transforms market signals into concrete actions. PW Consulting stands ready to translate the findings into a bespoke roadmap that secures growth and market differentiation in a steadily expanding Water Quality Analyzer market.
For detailed analysis of this topic, please visit the official page: Water Quality Analyzer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com