

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Ceramic Ferrule Market to Reach USD 363.08M by 2032 (6.5% CAGR)

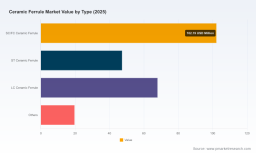
Ceramic Ferrule Market: Strategic Imperatives for 2026 Decision‑Makers
As PW Consulting’s lead industry analyst, I present a focused preview of our full Ceramic Ferrule Market study — a practical intelligence product designed to inform capital allocation, sourcing strategy, and product roadmapping through the critical decision window of 2026. The market for ceramic ferrules has been on a steady growth trajectory: from a market value of approximately USD 176.5 Million in 2020 to about USD 237.0 Million in 2025, and our base model projects an expansion to roughly USD 259.45 Million in 2026, reaching USD 363.08 Million by 2032. That path is consistent with a compound annual growth rate (CAGR) of 6.5% across the forecast period (2026–2032).
Ceramic Ferrule Market
Why this study matters in 2026
- Tactical timing: 2026 is a pivot year for buyers and manufacturers. Capex cycles started earlier in the decade are yielding capacity effects, while demand-side inflections — in datacenter densification, broader deployment of high‑speed access networks, and automotive optical sensing — are accelerating premium ferrule requirements.
- Supply‑chain dynamics: Zirconia remains the material of choice for high‑precision ferrules. Raw material markets were relatively stable in early 2025 with a modest uptick driven by recovering automotive and electronics demand; simultaneously, policy signals (notably U.S. critical mineral programs in 2026) are reshaping incentives for regional zirconium investment and downstream localization.
- Competitive balance: The market is neither hyper‑fragmented nor tightly monopolized; a modestly concentrated top tier controls meaningful share, creating incentives for both cooperation (supply agreements, standards) and consolidation (M&A, capacity aggregation).
- Technology push: Connector miniaturization and increased fiber counts per connector are forcing tighter tolerances and different manufacturing approaches — from raw ceramic formulation to polishing and metrology — shifting value to firms that combine materials science with precision manufacturing and automated inspection.
What the report delivers — practical, actionable components
We designed this study for executives who must convert market signals into executable strategies during 2026. The full deliverable contains:
Ceramic Ferrule Market
- Robust market-sizing and trend models: Time‑series demand modeling (2020–2025 historical, 2026–2032 forecast) with scenario layers (baseline, accelerated demand, supply disruption) that quantify revenue and capacity needs under each posture.
- Technology and production playbook: Deep dives on zirconia variants, sintering profiles, CNC and polishing tolerances, metrology methods, and yield improvement levers — including recommended investments and expected ROI timelines.
- Supply‑chain map and supplier archetypes: From upstream mineral sources to finished‑goods assemblers, with risk scoring for single‑sourcing, nearshoring, and regulatory exposure. (Note: granular regional and application breakdowns are reserved for the full report.)
- Commercial strategy templates: Pricing sensitivity matrices, contractual clauses for material-price pass‑throughs, and procurement playbooks for negotiating capacity reservations and quality SLAs.
- Scenario and stress testing tools: Interactive dashboards that let you re-run forecasts under variations in raw‑material cost, connector adoption rates, or sudden capacity additions from tier‑1 incumbents.
- Risk and compliance checklist: Actionable items to align sourcing and manufacturing with evolving mineral‑policy landscapes and traceability expectations.
Competitive landscape — reading the moves and the motives
Our report profiles the competitive field with emphasis on capabilities, strategic intent, and near‑term actions. Four representative firms illustrate the range of strategic postures in the market:
Ceramic Ferrule Market
- Orbray Co., Ltd. (Tokyo, Japan) — A specialist in zirconia and custom ferrules, Orbray combines materials expertise with higher‑mix, lower‑volume custom work. In April 2026 they announced a plan to relocate their headquarters to Yuzawa, Akita, scheduled for December 2026 — a move that signals a long‑term strategy to consolidate R&D and precision manufacturing in a region with skilled ceramics supply chains.
- T&S Communication Co., Ltd. (Shenzhen, China) — A high‑volume producer focused on SC/LC/MPO ferrules and aggressive product launches. T&S leveraged trade shows such as APE 2026 (March 2026) to showcase high‑density interconnect solutions, underlining their orientation toward datacenter and telecom OEM partnerships.
- ChaoZhou Three‑circle (Group) Co., Ltd. (Chaozhou, Guangdong, China) — A domestic manufacturing champion with scale advantages and government‑aligned positioning. Their strengths lie in cost‑efficient volume production and vertical integration of ceramics processing.
- Kyocera Corporation (Kyoto, Japan) — A global leader in fine ceramics, Kyocera represents the high‑reliability, premium end of the market, supplying customers that demand rigorous quality control and longevity for critical optical systems.
These firms illustrate the strategic tradeoffs: scale vs. customization; regional supply security vs. global reach; low‑cost manufacturing vs. premium capability. Our benchmarking framework in the full report scores players across manufacturing footprint, material sourcing, quality systems, and go‑to‑market channels — enabling buyers and investors to identify the most relevant partners or targets.
Key strategic implications for 2026 decision‑makers
- Prioritize supply resilience: With material inputs and policy shifts in play, create dual‑sourcing strategies and evaluate capacity reservation agreements. Suppliers with integrated zirconia supply or long‑lead relationships warrant premium consideration.
- Invest selectively in precision capability: The growth trajectory (6.5% CAGR) favors firms that can produce tighter tolerances at scale. Capital deployed to automated polishing, inline metrology, and yield analytics tends to pay back faster than broad, undirected capacity expansion.
- Forge product‑level differentiation: For OEMs, partnering with ferrule suppliers to co‑develop connector assemblies (where ferrule specification is a system enabler) reduces integration risk and shortens time‑to‑market.
- Use commercial terms to share risk: Incorporate indexed pricing and volume flexibility clauses to manage raw‑material fluctuations and demand seasonality, while protecting suppliers’ margin to secure capacity.
- Screen M&A and alliance candidates: A moderate top‑tier concentration suggests opportunities for bolt‑on acquisitions and strategic partnerships that can consolidate technology stacks or regional presence — but perform rigorous due diligence on production yield histories and IP ownership.
- Align with regulatory trends: Traceability of mineral inputs and compliance with regional critical‑mineral initiatives are emerging procurement filters for large OEMs; early alignment can be a competitive differentiator.
How to apply our forecast model in your 2026 planning
The report’s forecast framework is intentionally modular. The baseline path reflects the 6.5% CAGR across 2026–2032 and the market values noted earlier; layered scenarios let you evaluate the impact of:
- Accelerated adoption of high‑density connectors in datacenters and next‑generation access networks;
- Raw‑material shocks or price escalations from supply disruptions; and
- Strategic capacity additions by a tier‑1 supplier or a rapid push into nearshore manufacturing.
For procurement, finance, and product leaders, the model enables stress‑testing of purchase commitments, capital plans, and pricing strategies. For investors and corporate development teams it provides an M&A screening tool that highlights where consolidation could unlock margins or market access.
Concluding guidance — what to do next
Our preview surfaces the strategic contours: a healthy growth market, a material‑intensive supply chain under evolving policy pressure, and a competitive set that is balancing scale with specialization. The clearest near‑term advantage goes to organizations that treat ferrules not as commodity parts but as system‑enabling components — investing in supplier relationships, production quality, and scenario planning in 2026.
PW Consulting’s full Ceramic Ferrule Market report includes the withheld granular segmentation, detailed supplier scorecards, and interactive models referenced above. If your 2026 roadmap will hinge on procurement commitments, capex, or M&A moves in this value chain, accessing the complete dataset and playbooks will materially sharpen those decisions.
Contact the PW Consulting insights team to request the full report, access interactive dashboards, or arrange a bespoke briefing tailored to your organization’s position in the ceramic ferrule value chain.
For detailed analysis of this topic, please visit the official page: Ceramic Ferrule Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com