

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Screw Press Market to Expand at 7.5% CAGR Through 2032

Screw Press Market — 2026 Strategic Briefing
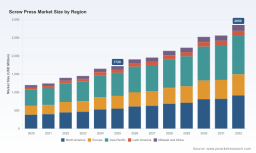
As PW Consulting’s Lead Industry Analyst, I present a focused strategic preview of our Screw Press Market study (base year 2025, historical window 2020–2025, forecast horizon 2026–2032). The market’s macro trajectory is clear: total industry revenues expanded from approximately USD 1.2 billion in 2020 to about USD 1.72 billion by 2025, and our modelling projects a continuation of robust expansion to roughly USD 2.85 billion by 2032, driven by a 7.5% CAGR across the 2026–2032 forecast interval. For executives planning capex, M&A, or go‑to‑market moves in 2026, the strategic choices you make this year will determine margin capture throughout the cycle. This briefing summarizes the report’s strategic value, highlights the dynamics that matter most, and explains how to use the full study as an operational playbook.
Screw Press Market
Why this study matters for 2026 decision-making
-
Timing: 2026 is the inflection point where tightened environmental standards, energy performance expectations, and circular‑economy priorities converge with a buyer market that is cost‑sensitive and increasingly focused on lifecycle outcomes rather than capital price alone.
Screw Press Market -
Evidence based: Our study combines historical demand patterns (2020–2025), primary vendor intelligence, and scenario modelling to quantify the value pools that will be most accessible to equipment manufacturers, system integrators, and service providers during the 2026–2032 growth window.
Screw Press Market -
Decision utility: The research is purpose‑built to translate market forecasts into concrete operational choices — procurement timing, specification trade‑offs, aftermarket pricing, and partnership strategies — with tools and templates designed for immediate use.
What the PW Consulting report delivers (practical, deployable outputs)
-
Market sizing and forecast methodology: transparent assumptions, sensitivity tables, and scenario paths so leadership teams can stress‑test strategy under different regulatory and energy‑price environments.
-
Buyer’s playbook: procurement checklists, technical specification templates, and TCO calculators that convert performance claims into net present value differences for common municipal and industrial procurement cases.
-
Vendor scorecards and selection matrix: comparative evaluation criteria across engineering quality, energy efficiency, service footprint, supply‑chain resilience, and retrofit capability.
-
Operational KPIs and retrofit roadmaps: step‑by‑step guidance for plant managers to reduce OPEX via optimized screw press selection, predictive maintenance, and process integration.
-
M&A and partnership decision framework: value levers, integration pitfalls, and three acquisition archetypes that create near‑term cash flow lift versus long‑term platform value.
-
Commercial models and aftersales monetization: pricing playbooks for spare parts, refurbishment cycles, and remote‑monitoring subscription services that materially improve aftermarket margin.
Core market dynamics shaping strategy
-
Regulation and compliance are dominant growth multipliers. European and U.S. policy drivers have directly accelerated installations: public sources indicate strong adoption of screw press systems in EU countries and substantial upgrades across U.S. municipal plants in recent years. These regulatory forces translate into predictable procurement pipelines for suppliers focused on municipal wastewater and regulated industrial discharges.
-
Energy and lifecycle economics are reshaping procurement criteria. Leading models now emphasize electrical efficiency and solids capture as primary buyer metrics, not just capital cost. Equipment that demonstrably reduces electricity and disposal costs alters the TCO calculus and shortens payback horizons.
-
Material and fabrication realities: wetted components are commonly specified in stainless steel, while structural elements use carbon steel — a detail that affects unit cost, corrosion management, and long‑term maintenance budgets. Sourcing strategies and supplier certifications matter more now than before.
-
Adoption barriers among smaller operators persist. Industry surveys and Commission analyses show meaningful portions of SME operators cite high initial capital and installation costs as hurdles to adoption; financing structures and service‑based models will therefore be decisive in unlocking these pockets of demand.
-
Product innovation is bifurcating the market. Vendors competing on energy efficiency, throughput for high‑solids feedstocks, and enclosed low‑odour designs command procurement preference when lifecycle metrics are emphasized.
Competitive landscape — what leaders are doing
The market exhibits moderate concentration: the top three suppliers account for a material but not dominant share of industry revenues, and the top five collectively represent a majority stake — a structure that creates opportunity for both scale consolidation and differentiated niche leadership. The report’s vendor benchmarking goes deeper; below is a directional view of the competitive archetypes you’ll find analysed in the full study.
-
FKC Co., LTD. — Port Angeles, WA: a global leader with thousands of installations and strong pedigree in municipal wastewater and thickening applications. Their installed base gives them an outsized advantage in aftersales and retrofit offerings.
-
Vincent Corporation — United States: specialized engineering and manufacturing focus with product portfolios tuned to squeezing liquids from organic material; their strengths include process integration and custom engineering for complex feedstocks.
-
BDP Industries — Greenwich, NY: U.S. manufacture and enclosed designs that emphasize low energy and reduced maintenance; positioned for customers prioritizing compact footprints and reduced plant disruption.
-
HUBER Technology — Germany: notable for machines that exceed electric motor efficiency standards and for a technology narrative centered on maximizing electrical efficiency and solids throughput.
-
ANDRITZ AG — Austria: offers large‑scale systems and separation expertise; attractive to buyers seeking integrated systems and global service networks.
Our analysis includes a comparative matrix that maps these vendors across technical performance, aftermarket reach, pricing posture, and suitability for retrofit or greenfield projects. We also model where consolidation or strategic partnerships are most likely to unlock value for incumbents and challengers alike.
Strategic implications for 2026 — priority actions
-
For equipment OEMs: prioritize energy‑efficient drive systems, materials sourcing resilience, and modular designs that reduce installation complexity. Embed service contracts and remote monitoring to shift revenue mix toward higher‑margin aftermarket streams.
-
For utilities and large end users: reframe procurement around TCO and regulatory risk mitigation. Consider staged rollouts with performance‑based payments or O&M bundling to lower adoption barriers for internal stakeholders.
-
For private equity and corporate development teams: target assets that provide aftermarket scale (installed base, service organization) or proprietary technology that materially reduces lifecycle costs. Use our M&A valuation templates to separate headline multiples from true integration value.
-
For service providers and integrators: develop retrofit offerings that convert legacy dewatering assets to higher‑efficiency configurations — these are high‑velocity opportunities where paybacks are short and budgets are available.
How to use the full PW Consulting study as your playbook
-
Scenario testing: use the included demand scenarios to stress‑test backlog, supply chain risk, and pricing enhancements against alternative regulatory and energy price outcomes.
-
Procurement execution: apply our RFP templates and vendor scorecards to accelerate vendor selection while protecting TCO objectives.
-
Commercialization: implement the report’s pricing ladders and aftermarket subscription frameworks to lift margin without sacrificing installations.
-
Organizational alignment: leverage our one‑page executive dashboard to synchronize engineering, procurement, and finance teams around common KPIs for any given project.
What we intentionally withhold here — why you should read the full report
This briefing showcases the study’s strategic depth while protecting the proprietary, granular intelligence that gives clients a competitive edge. The full report contains detailed segment‑level revenue splits, regional and application breakout models, product‑type economics, vendor market shares at granular levels, and downloadable TCO calculators — all necessary to execute complex procurement, investment, or product strategies. If your team needs those worksheets, the vendor comparison matrices, or the full scenario datasets for board‑level decisioning, the full study is the next step.
Next steps — practical engagement options
-
Download the comprehensive report for full data access and appendices, including the vendor scorecards and financial templates.
-
Commission a tailor‑made workshop with PW Consulting to translate the study into a 12–24 month execution roadmap for procurement, engineering, or M&A teams.
-
Request a vendor deep‑dive: we provide bespoke diligence on selected suppliers, including factory visits, supplier audits, and integration playbooks.
In 2026 the screw press market offers both predictable demand uplift and meaningful differentiation opportunities for those who act on lifecycle economics, retrofit pathways, and service‑led growth. Our report is designed to convert the market’s macro momentum into executable strategy: if your organization faces a procurement, product development, or investment decision this year, use the study as the operational bridge from insight to value capture.
For detailed analysis of this topic, please visit the official page: Screw Press Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com