

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Serial Device Server Market to Reach USD 317.3M by 2032 at 6.5% CAGR

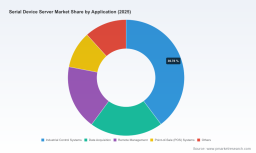
Serial Device Server Market: Strategic Preview for 2026 Decision-Making
As enterprises accelerate legacy-to-IP transformations across industrial automation, transportation, and critical infrastructure, the Serial Device Server market is experiencing measured but durable expansion. PW Consulting’s forthcoming Serial Device Server Market study synthesizes five years of historical performance (2020–2025) and a seven-year forecast (2026–2032) to deliver the market intelligence leaders need to act decisively in 2026. This preview outlines the study’s strategic value, highlights market dynamics and competitive moves, and frames the practical levers executive teams should prioritize — while reserving the detailed segment-level tables and vendor scorecards for the full report.
Serial Device Server Market
Market snapshot: growth trajectory and concentration
The market has moved from modest scale in 2020 through steady growth into the 2025 base year. Our topline metrics capture that momentum: the market expanded meaningfully over the historical window and is projected to continue growing at a compound annual growth rate of approximately 6.5% across the 2026–2032 forecast interval. By the start of the forecast period, PW Consulting places the market at a clear inflection point, with continued adoption driven by legacy device modernization, regulatory-compliant deployments in transportation and hazardous environments, and renewed investment in remote management and data-acquisition infrastructures.
Serial Device Server Market
Market structure matters. The competitive footprint is moderately concentrated, with the top three vendors controlling a material share of industry revenue and the top five firms capturing roughly two-thirds of the market. That concentration profile creates both predictable supply channels for buyers and opportunity windows for challengers who can deliver differentiated security, certification, or integration capabilities.
Serial Device Server Market
Why this study matters to 2026 strategic decisions
- Procurement and vendor selection: Buyers moving from bespoke legacy bridges to managed, secure serial-to-IP gateways will need granular cost and certification comparisons to justify multi-year replacement plans. Our study provides procurement-ready evaluation criteria and procurement risk matrices aligned to 2026 budget cycles.
- Product and roadmap prioritization: Hardware vendors and OEMs must choose between incremental product refresh and platform shifts (e.g., edge compute-enabled serial servers, modular SFP-based bridging). The report models the commercial upside of both approaches under multiple adoption scenarios.
- M&A and partnership screening: With mid-sized incumbents and specialist providers occupying defensive positions, strategic acquirers will seek assets that unlock vertical integrations (transportation, utilities, retail POS). The study highlights value-creation archetypes and integration risk contours.
- Compliance and go-to-market readiness: Regulatory obligations — from FCC Part 15 compliance in the U.S. to CE marking within the EEA and NEMA TS2 for transportation-grade solutions — are increasingly non-negotiable for cross-border deployments. We map certification timelines and readiness gaps that should inform 2026 product launches.
Dynamics shaping supply, demand, and pricing
- Legacy modernization as the base case: A substantial portion of near-term demand will come from brownfield projects replacing aging RS-232/422/485 links with managed serial device servers that preserve control-system investments while enabling centralized monitoring.
- Security and management expectations: Encrypted serial tunneling, centralized device management, and hardened authentication are baseline requirements for enterprise-grade deployments. Recent supplier updates underscore an industry-wide upgrade toward SSL/SSH management and centralized provisioning.
- Certification as market access: UL safety listings, hazardous-location approvals, and transport-specific certifications (NEMA TS2) are now decisive procurement filters for infrastructure buyers. Non-compliant vendors risk exclusion from critical tenders.
- Infrastructure cost drivers: Network interface modules, fiber-optic trunking, and industrial Ethernet components continue to represent primary deployment costs. These elements materially affect TCO calculations and the economic argument for edge-enabled vs. centralized deployment models.
What the full PW Consulting report delivers (practical, operational content)
- Topline market sizing and trend analysis (historical and forecast) with clear methodology notes and risk-adjusted scenarios designed for CFO review.
- Vendor competitive benchmarking and scorecards covering product breadth, certifications, software management capabilities, channel strength, and innovation score.
- Go-to-market playbooks for vendors and systems integrators: pricing strategies, vertical prioritization, and partnership models tailored to 2026 procurement cycles.
- Procurement risk matrix and buyer’s guide: contract clauses, service-level expectations, and field-certification checklists to accelerate deployment approvals.
- Deployment cost models and TCO calculators that capture infrastructure drivers (Ethernet NICs, fiber runs, environmental protection) and permit scenario comparison under varying scale assumptions.
- Regulatory and certification matrix: timelines, test protocols, and vendor readiness assessment for FCC, CE, UL, and NEMA-related approvals.
- M&A and product-roadmap playbooks that map valuation multipliers to strategic value drivers such as IP, certifications, and channel access.
These components are structured for direct handoff to product leaders, procurement teams, and corporate development units preparing 2026 commitments.
Competitive landscape—profiles and recent moves
The market combines large industrial automation players with specialist networking firms. Below are strategic observations on a selection of active players whose actions will shape the 2026 competitive picture.
- Pepperl+Fuchs (Mannheim, Germany): Known for DIN-rail industrial offerings, their ICDM-RX/TCP series targets transportation and heavy industrial installations with NEMA TS2 positioning. Recent family extensions reflect a deliberate move to secure transportation tenders where environmental and spectrum compliance are decisive.
- Comtrol / Pepperl+Fuchs Comtrol (Twinsburg, OH, USA): The DeviceMaster family targets secure serial-to-IP gateways with enhanced encryption and management suites. Product updates adding SSL/SSH and encrypted serial streams point to a strategy of certifying industrial-grade security for sensitive installations.
- Digi International (Minneapolis, MN, USA): Digi’s Connect series and RealPort integrations emphasize legacy-driver compatibility and centralized device management. Their recent launches of multi-port secure servers indicate an effort to capture scale deployments for systems integrators.
- Moxa (Taipei, Taiwan): With the NPort and IA5000 families, Moxa continues to emphasize ruggedized hardware, surge protection, and hazardous-location certifications — a play that aligns with utilities and process industries seeking resilience.
- Advantech and PLANET Technology (Taipei, Taiwan): Both focus on industrial-grade product lines with LAN redundancy and wide-temperature operation respectively — strengthening value propositions for OEMs and transportation integrators.
- Patton (Gaithersburg, MD, USA): Patton’s SFP-based hot-swappable solutions deliver modularity that appeals to network operators and sectors where in-field replacement and fiber uplink flexibility matter.
- Silex Technology (Tokyo, Japan) and Sealevel Systems (Liberty, SC, USA): These vendors serve niches that require wireless bridging options or high-port-count solutions for DAQ and control systems, underlining segmentation opportunities for specialized players.
Recent product launches and updates across these vendors — from enhanced surge protection to centralized management platforms and SFP modularity — collectively reveal two market imperatives: certification-led differentiation and management/security as the baseline feature set.
Strategic imperatives for 2026
- Prioritize certified platforms: If your deployments touch transportation, utilities, or hazardous sites, only vendors with the requisite certifications should be in shortlist conversations. Certification leads to faster procurement approvals and mitigates deployment delays.
- Design for operational visibility: Centralized device management, encrypted tunnels, and automated provisioning will reduce lifecycle costs and operational risk — convert these into contract-level KPIs when negotiating supplier SLAs.
- Model infrastructure TCO explicitly: Treat Ethernet/fiber costs and interface cards as first-order variables in your ROI models. Small differences in NIC/fiber assumptions will materially shift breakeven timelines for retrofit vs. replacement strategies.
- Defend with product modularity: For vendors, SFP-based or hot-swappable architectures provide an edge in network-operator and telco-adjacent tenders; for buyers, they provide future-proofing and reduced mean-time-to-repair.
- Scan for strategic consolidations: M&A remains an efficient route to obtain certification portfolios or channel access; acquirers should use our strategic playbooks to calibrate price premia against integration risk.
Methodology note and how to access the full intelligence
PW Consulting’s market sizing combines bottom-up vendor shipment estimates, proprietary channel checks, and deployment-cost models, cross-validated by primary interviews and public filings. The forecast uses a risk-weighted scenario approach calibrated to macro supply-chain dynamics and infrastructure spending cycles. To preserve actionable value for subscribers, this preview intentionally omits the granular segment tables, regional and application splits, and the vendor-level scorecards that are available in the full study.
For procurement teams, product leaders, and corporate development executives preparing 2026 commitments, the full report supplies the operational dashboards, downloadable TCO spreadsheets, and vendor negotiation checklists necessary to move from strategy to execution. PW Consulting’s advisory services can also convert the study into a tailored workshop or an executive briefing to accelerate decision timelines.
Contact PW Consulting to request the full Serial Device Server Market report and to schedule a strategic briefing tailored to your organization’s 2026 priorities. The detailed regional, type, and application breakdowns — and our interactive scenario tools — are accessible to subscribers and form the basis for immediate operational planning.
For detailed analysis of this topic, please visit the official page: Serial Device Server Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com