

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: High-Temperature Capacitors Market to Reach USD 254.7M by 2032 at 7.2% CAGR

High Temperature Capacitors Market — Strategic Outlook for 2026 Decision‑Makers
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a concise but deep market context for high temperature capacitors that is designed to inform executive choices in 2026. Our new study uses 2025 as the base year and projects through 2032. The market has expanded steadily from the start of the decade, rising from roughly USD 114 million in 2020 to about USD 157 million in 2025, and is projected to grow at a compound annual growth rate (CAGR) of approximately 7.2% across the 2026–2032 forecast window — reaching roughly USD 255 million by 2032. These headline dynamics matter: they quantify both the near‑term runway and the medium‑term scale that justify investment, qualification programs, and structural shifts in supply chains.
High Temperature Capacitors Market
Why 2026 Is a Tactical Inflection Point
2026 is where technology maturation, supply‑side adjustments and end‑market demand converge. Innovations in high‑temperature film materials (including commercial deployments of films capable of continuous operation at or near 200°C), longer qualification cycles in automotive and aerospace, and expanding electrification in industrial systems are changing supplier economics and product roadmaps simultaneously. For companies deciding on capital allocation, product launches, or strategic partnerships this year, the right moves can lock in multi‑year revenue streams and preferred supplier status; the wrong pace risks being left with underutilized capacity or missed platform positions.
High Temperature Capacitors Market
What the Market Trajectory Reveals for Strategic Choices
-
Steady Base, Accelerating Scale — The high temperature capacitor market has shown consistent growth through 2025 and the forecast projects continued expansion at a mid‑single‑digit CAGR. That combination creates a reliable near‑term market while giving enough long‑term upside to support multi‑year qualification and tooling investments.
High Temperature Capacitors Market -
Technology‑Led Leapfrogs — Material and process breakthroughs (film chemistries, ceramic formulations and hybrid constructions) are unlocking higher operational temperatures and longer lifetimes. These advances are increasingly the determinant of premium pricing and differentiated value propositions in power electronics stacks.
-
Prioritized Applications — Electrification in mobility, higher‑temperature industrial power conversion, and mission‑critical defense and aerospace controls are the principal demand engines. Buyers in these segments are placing a premium on qualified reliability data and lifecycle cost analysis rather than lowest unit price.
Demand Drivers and Technology Pathways
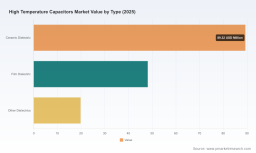
Demand is being pulled by four mutually reinforcing trends: the shift to higher density power conversion (EVs, industrial motor drives, grid‑edge inverters), increased specification ceilings for operating temperature and lifetime in harsh environments, the need for compact, thermally robust passive components to satisfy system‑level thermal budgets, and OEMs’ emphasis on supplier resilience. On the technology side, three material families dominate development activity: advanced film dielectrics, ceramic dielectrics, and engineered “other” dielectrics (including composite and polymer‑ceramic hybrids). Each brings a distinct trade‑off among volumetric efficiency, temperature stability, aging characteristics and manufacturability.
Recent industry moves illustrate these dynamics: volume production of capacitors built with specialized high‑temperature film reached a new milestone in mid‑2025, with commercial lines qualified to operate at temperatures approaching 200°C. Complementing that, several suppliers have introduced series rated for elevated continuous temperatures or extended mission hours in traction and inverter applications during 2025–2026 — a sign that technically mature options are crossing the threshold to commercial adoption.
Supply‑Side Reality: Costs, Lead Times and Capacity Constraints
The supply picture is shaped by several structural frictions that matter for 2026 planning. High‑temperature polymers and specialty ceramics saw material price increases in the recent period; these raw material dynamics translated into noticeable input cost pressure for the industry. At the same time, production of high‑temperature capacitors remains more complex than standard capacitor manufacturing — resulting in materially longer lead times in many factories. Supply chain complexity and component integration challenges affect a meaningful portion of global output, while environmental and regulatory constraints are limiting the pace and location of plant expansions. The net effect: manufacturers and OEM purchasers must balance inventory, dual‑sourcing and near‑shoring considerations against the cost of holding strategic safety stock and the lead time for qualification.
Competitive Landscape — What Winning Looks Like
The competitive environment blends legacy component specialists and new material innovators. Several company archetypes have emerged:
-
Material Innovators partnered with High‑Volume Assemblers — Firms that own or license breakthrough dielectric films and pair them with experienced capacitor assembly partners are moving fastest to commercial scale. The commercialization timeline that reached volume output in 2025 is a direct outcome of such partnerships.
-
Legacy Diversified Electronics Manufacturers — Established conglomerates with broad passive component portfolios are leveraging existing automotive and industrial qualification pipelines to sell high‑temperature lines into OEM programs, using scale and long‑term warranty commitments as competitive assets.
-
Specialist Niche Players — Companies focused on mission‑critical and niche high‑temperature solutions (e.g., for aerospace or specialized industrial controls) continue to command premium ASPs through deep reliability data packages, customized testing, and service‑level agreements.
Representative companies illustrate these archetypes. There are material partners and manufacturers that have brought high‑temperature film to production with partner assemblies; specialist suppliers are shipping product families rated for 175°C and above; global passive conglomerates are expanding their product series and lifetime‑data offerings for industrial and traction markets; and traction‑grade DC filter suppliers have released series with industry‑leading lifetime and standards compliance in 2026. The competitive landscape is becoming more consolidated at the top, while pockets of opportunity remain for focused innovators with robust qualification roadmaps.
Operational and Commercial Playbook for 2026
-
Procurement: Move from spot buying to strategic contracting. Lock multi‑year supply agreements for high‑temperature polymers and specialty ceramics where possible, and build in indexed pricing triggers tied to raw material indices to manage margin volatility.
-
Qualification & Product Roadmap: Start or accelerate multi‑year qualification programs now. The bar for acceptance in automotive and aerospace is rising — lifetime and high‑temperature derating data will determine platform inclusion.
-
Manufacturing Footprint: Use a hybrid approach. Localize final assembly near key OEMs for speed and qualification convenience while keeping large, capital‑intensive film extrusion and ceramic production centralized where scale economics and material sourcing are strongest.
-
Partnerships & IP Strategy: Consider partnerships with film owners or licensing agreements to shorten time‑to‑market. For incumbents, selective acquisitions of niche high‑temperature specialists can buy immediate access to validated designs and qualification artifacts.
-
Risk Management: Implement a tiered inventory and lead‑time mitigation plan. Given that production lead times for high‑temperature products can exceed standard component timelines, early ordering and staged qualification can prevent programme delays.
What Our Report Provides (Practical, Executable)
PW Consulting’s High Temperature Capacitors Market study is explicitly built for executives who must act in 2026. The deliverables are designed to be operationally usable rather than academic:
-
Actionable market sizing with historical trend analysis and a 2026–2032 forecast calibrated to technology adoption scenarios.
-
Supplier scorecards and a competitive benchmarking matrix that assess technology readiness, qualification track record, capacity availability and pricing posture.
-
Manufacturing risk heatmaps and a raw material cost build‑up model that quantify the impact of recent polymer and ceramic price movements on unit economics.
-
Go‑to‑market playbooks tailored for incumbents, entrants and OEM buyers — including partnership strategies, licensing models and M&A decision frameworks.
-
Scenario analyses showing how changes in material prices, lead times and regulatory constraints affect ROI, breakeven timelines and optimal capacity expansion cadence.
To respect the “trailer” principle of this brief, we highlight that the report contains detailed segmentation by region, dielectric type and end‑use application plus unit‑level cost models and supplier revenue share tables. Those granular tables and the underlying data models are intentionally withheld here to preserve our proprietary analysis; they are available in the full study for licensed subscribers and corporate clients.
Immediate Next Steps for Executives
-
Align procurement and engineering roadmaps now — lock tests and qualification windows into 2026 product schedules so components are qualified ahead of vehicle/platform milestones.
-
Pilot partnerships with material innovators — evaluate short co‑development engagements to validate next‑generation film and ceramic options under your in‑system thermal profile.
-
Stress‑test your supply base — model scenarios for material price shocks and extended lead times; prioritize suppliers that provide transparent BOM cost breakdowns and long‑term capacity commitments.
-
Assess strategic M&A or licensing targets — where in‑house development would be slower or more expensive than acquiring validated capability, act decisively in 2026.
Concluding Perspective
The high temperature capacitors market offers a predictable but technically demanding growth opportunity. For 2026 decision‑makers, the critical tradeoffs are between speed (to secure design wins and supply contracts), depth (to accumulate reliability data and differentiate on lifetime), and control (to manage raw materials and manufacturing risk). PW Consulting’s study quantifies these tradeoffs and turns them into executable options — from procurement blueprints to M&A screens and detailed supplier scorecards. If your strategic choices in 2026 are informed by reliable projection, tested qualification pathways and mapped supply‑chain contingencies, you will capture a disproportionate share of the market’s upside as the sector scales through the remainder of the decade.
For access to the full dataset, model outputs, supplier scorecards and the confidential segmentation tables that underpin our recommendations, please refer to the PW Consulting High Temperature Capacitors Market report page.
For detailed analysis of this topic, please visit the official page: High Temperature Capacitors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com